
UK's Promising Penny Stocks With Market Caps As Low As £70M
The UK stock market has recently faced challenges, as the FTSE 100 index experienced a downturn following disappointing trade data from China, highlighting ongoing global economic uncertainties. Amid such conditions, investors often seek out stocks with growth potential and resilience to market fluctuations. Penny stocks, though sometimes seen as a relic term, continue to offer intriguing opportunities for investment in smaller or newer companies that may possess strong financial health and promising prospects.
Let's dive into some prime choices out of the screener.
Concurrent Technologies (AIM:CNC)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: Concurrent Technologies Plc designs, develops, manufactures, and markets single board computers for system integrators and original equipment manufacturers across various international markets, with a market cap of £227.91 million.
Operations: The company generates £47.97 million in revenue from its operations focused on the design, manufacture, and supply of high-end embedded computer products.
Market Cap: £227.91M
Concurrent Technologies has shown stable financial performance, reporting a half-year revenue of £23.16 million and net income of £2.55 million, indicating modest growth from the previous year. The company is debt-free, with short-term assets significantly exceeding liabilities, enhancing its financial stability. Recent guidance suggests stronger revenue in the second half of 2026 due to a record contract win and ongoing demand for its embedded computer products. However, challenges such as component lead times persist. A significant $9.4 million order from a US defense contractor underscores potential for future growth in strategic markets.
- Jump into the full analysis health report here for a deeper understanding of Concurrent Technologies.
- Assess Concurrent Technologies' future earnings estimates with our detailed growth reports.
Hansard Global (LSE:HSD)
Simply Wall St Financial Health Rating: ★★★★★★
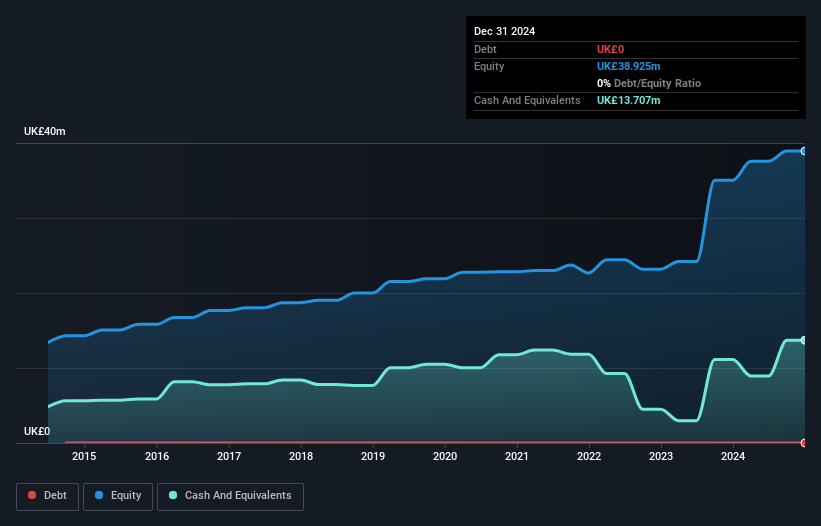
Overview: Hansard Global plc is involved in distributing and servicing long-term investment products across regions including the Isle of Man, the Bahamas, the Republic of Ireland, Malaysia, Japan, and the United Arab Emirates with a market cap of £79.88 million.
Operations: The company generates revenue of £247.6 million from the distribution and servicing of long-term investment products.
Market Cap: £79.88M
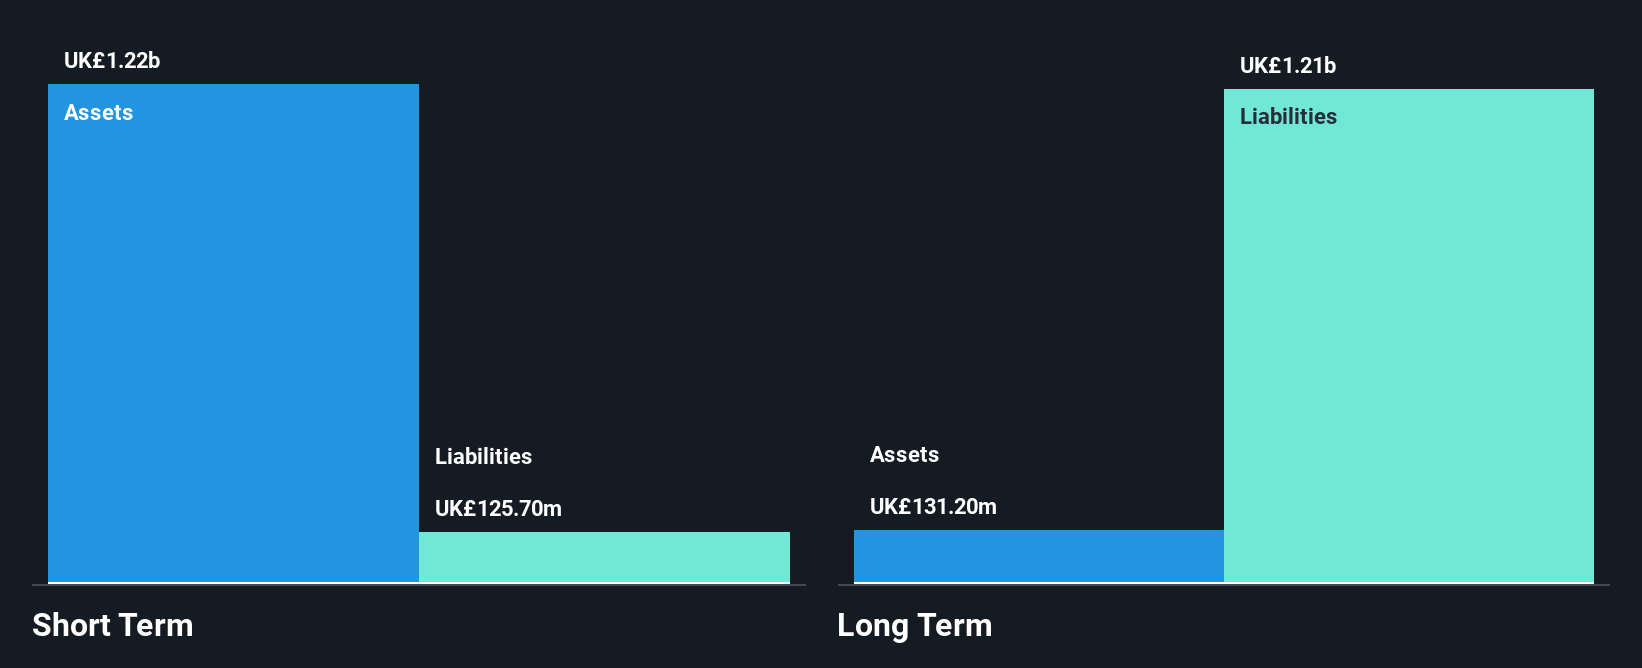
Hansard Global plc, with a market cap of £79.88 million, has demonstrated robust financial growth, reporting a significant increase in revenue to £247.6 million and net income of £6.5 million for the year ended June 30, 2026. Despite its high volatility and earnings impacted by one-off gains, the company remains debt-free with strong asset coverage of liabilities. Its return on equity is notably high at 39.2%, although dividend sustainability is questionable as payouts exceed earnings coverage. Recent executive changes aim to bolster sales strategies across diverse regions while maintaining stable dividends subject to shareholder approval in November 2026.
- Click here and access our complete financial health analysis report to understand the dynamics of Hansard Global.
- Learn about Hansard Global's future growth trajectory here.
LSL Property Services (LSE:LSL)
Simply Wall St Financial Health Rating: ★★★★★☆
Overview: LSL Property Services plc, along with its subsidiaries, operates a business-to-business platform offering residential market services in the United Kingdom and has a market capitalization of approximately £257.60 million.
Operations: The company's revenue is primarily derived from three segments: Financial Services generating £48.19 million, Surveying and Valuation contributing £110.70 million, and Estate Agency (excluding Financial Services) accounting for £26.70 million.
Market Cap: £257.6M
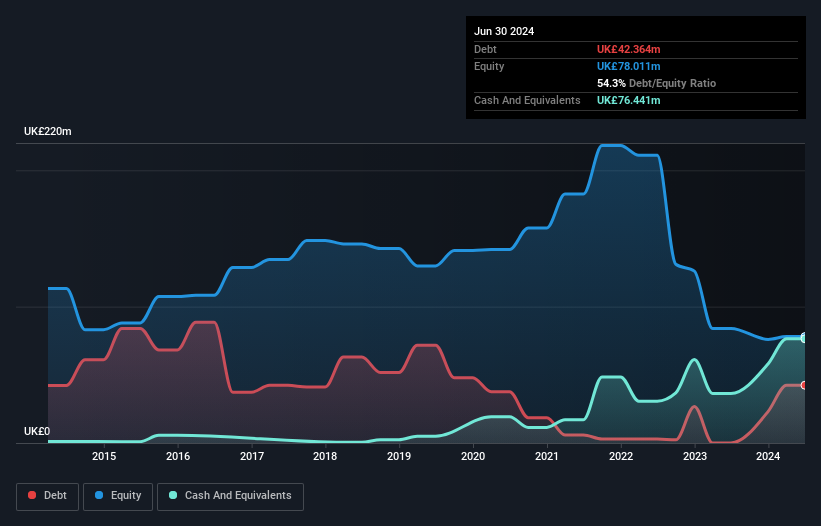
LSL Property Services plc, with a market cap of £257.60 million, has shown stable financial performance despite challenges. Its earnings have grown by 7% over the past year, surpassing its five-year average decline of 16.5% annually. The company maintains high-quality earnings with a return on equity of 21.3% and covers interest payments effectively. While its debt to equity ratio increased to 40.8%, it remains well-covered by operating cash flow (74.7%). Recent inclusion in the S&P Global BMI Index and consistent interim dividend affirmations underscore investor confidence, although management's limited experience may pose risks moving forward.
- Click here to discover the nuances of LSL Property Services with our detailed analytical financial health report.
- Gain insights into LSL Property Services' outlook and expected performance with our report on the company's earnings estimates.
Make It Happen
- Investigate our full lineup of 263 UK Penny Stocks right here.
- Seeking Other Investments? Trump has pledged to "unleash" American oil and gas and these 80 US stocks have developments that are poised to benefit.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com