
Is Revenue Beat Altering The Investment Case For Global Industrial (GIC)?
- Global Industrial reported Q2 revenue of $386.6 million, up 7.7% year on year and 2.4% above analyst expectations, while sector peers also beat consensus revenue estimates.
- The distributor delivered the slowest top line expansion among maintenance and repair peers, yet sector wide demand tied to supply chain reliability and economic cycles provided a stronger backdrop for its core MRO offering.
- This article examines how Global Industrial's investment narrative around higher value accounts and digital execution is affected by Q2 revenue beating expectations.
Scan how Global Industrial compares with peers by reviewing our hand picked list of solid balance sheet and fundamentals (25 results), which may also benefit when maintenance and repair demand stays resilient.
Global Industrial Investment Narrative Recap
For you to support Global Industrial, you need to believe the focus on higher value accounts, broader MRO ranges, and digital execution can continue to translate into healthy revenue and profit trends. The Q2 beat and 7.7% year on year top line growth support that view, even if the pace lagged other distributors, because it still shows customers are spending through the current cycle.
The key near term factor is how gross margins hold up as earlier freight and inventory tailwinds fade and tariff or input cost pressure remains unpredictable. The biggest risk is that a slowdown in North American industrial activity or large account spending would affect this more concentrated customer mix more than in the past.
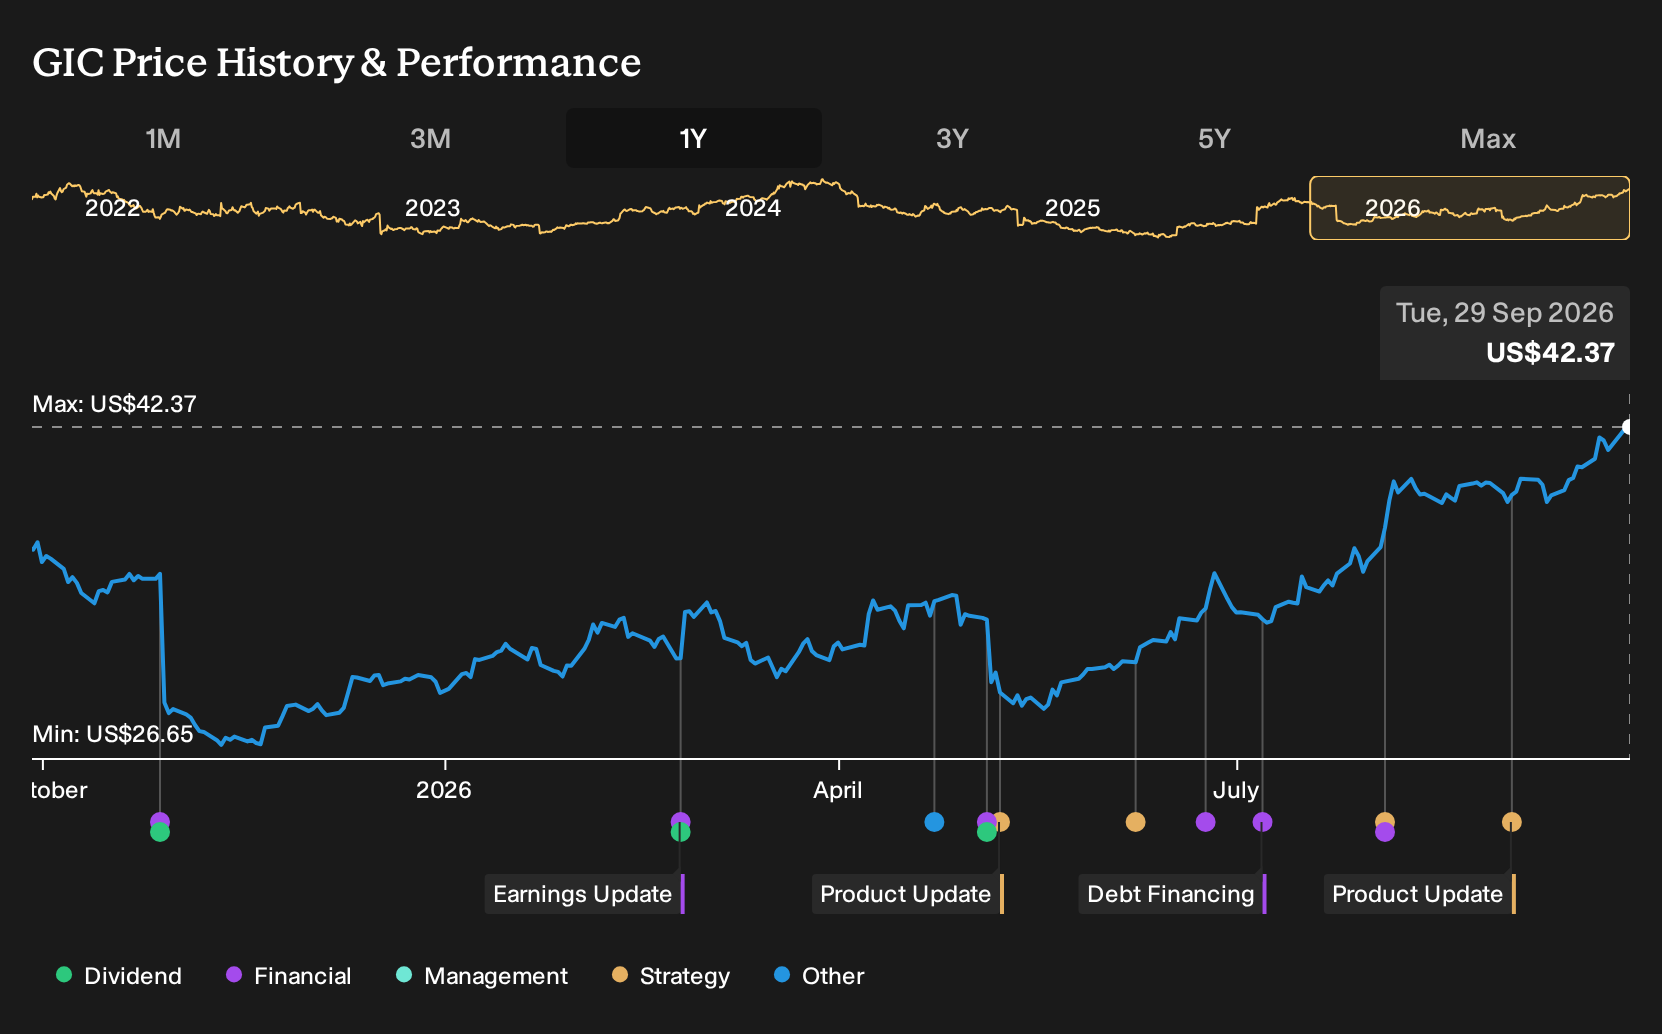
The Q2 update itself is the most recent reference point. Revenue of US$386.6 million, ahead of expectations and up 7.7% year on year, ties directly to the story of Global Industrial focusing on higher value accounts and digital selling. It indicates that salesforce and e-commerce investments are supporting volumes even while peers are also reporting strong quarters.
However, the company still posted the slowest top line expansion among maintenance and repair distributors, which keeps competitive pressure front and center. Looking ahead, investors following Global Industrial may focus on how management sustains growth from strategic accounts while managing gross margin volatility, tariff costs, and rising digital competition so these factors do not offset the benefits of the more focused model.
Global Industrial's narrative projects US$1.6b revenue and US$101.5 million earnings by 2029. This assumes 4.8% yearly revenue growth and an earnings increase of about US$28.6 million from US$72.9 million today.
Uncover why Global Industrial's fair value indicates a 6% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value opinions from the Simply Wall St Community cluster between US$39.62 and US$49.52 per share, with one at the top of that band hinting at limited upside if Global Industrial faces tariff driven cost pressure or a slowdown in large account spending. Use these differing views to test your own thesis before leaning in.
Explore 2 other Global Industrial fair value estimates, including one that suggests potential upside of up to 17% from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Global Industrial research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Global Industrial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Global Industrial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Global Industrial?
If Global Industrial has sharpened your focus on quality and execution, you can use that same lens to scan a wider opportunity set using the Simply Wall St Screener. You can filter by balance sheet strength, income potential, or lower volatility profiles to build a watchlist that matches your own risk and return preferences.
- If you want potential bargains with solid fundamentals, you can start with 32 high quality undervalued stocks that combine stronger cash generation with more conservative balance sheets.
- For investors who care about income resilience, you can consider companies in the 6 dividend fortresses that aim to pair higher yields with sturdier underlying businesses.
- If capital protection is a priority, you can narrow your search to the 32 resilient stocks with low risk scores that screen well on financial strength and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com