
3 Defensive U.S. Stocks to Watch as Rate Cuts Put Quality Back in Focus
Fed officials are sending mixed signals on rate hikes, Treasury yields have eased, and crucial data is about to hit, which puts high quality U.S. large caps in the spotlight. Investors hunting for a steadier ride may not want to wait until the next Fed meeting to rethink exposure. This article walks through three stocks from a defensive screener that appear particularly exposed to the latest rate and inflation twists.
The three examples below only scratch the surface of what this quality screen is turning up, since the full set of filters surfaced 34 more large caps with similarly robust balance sheets and profitability profiles that are not covered here. To see the entire defensive universe in one place, identify candidates that fit your risk profile, and analyze where you want to take your highest conviction, head straight to the U.S. Large-Cap Quality / Defensive Equities screener.
Elevance Health (ELV)
Elevance Health fits the defensive screen because it combines large scale, recurring premium income and disciplined cost control, which can appeal when rate policy feels unpredictable.
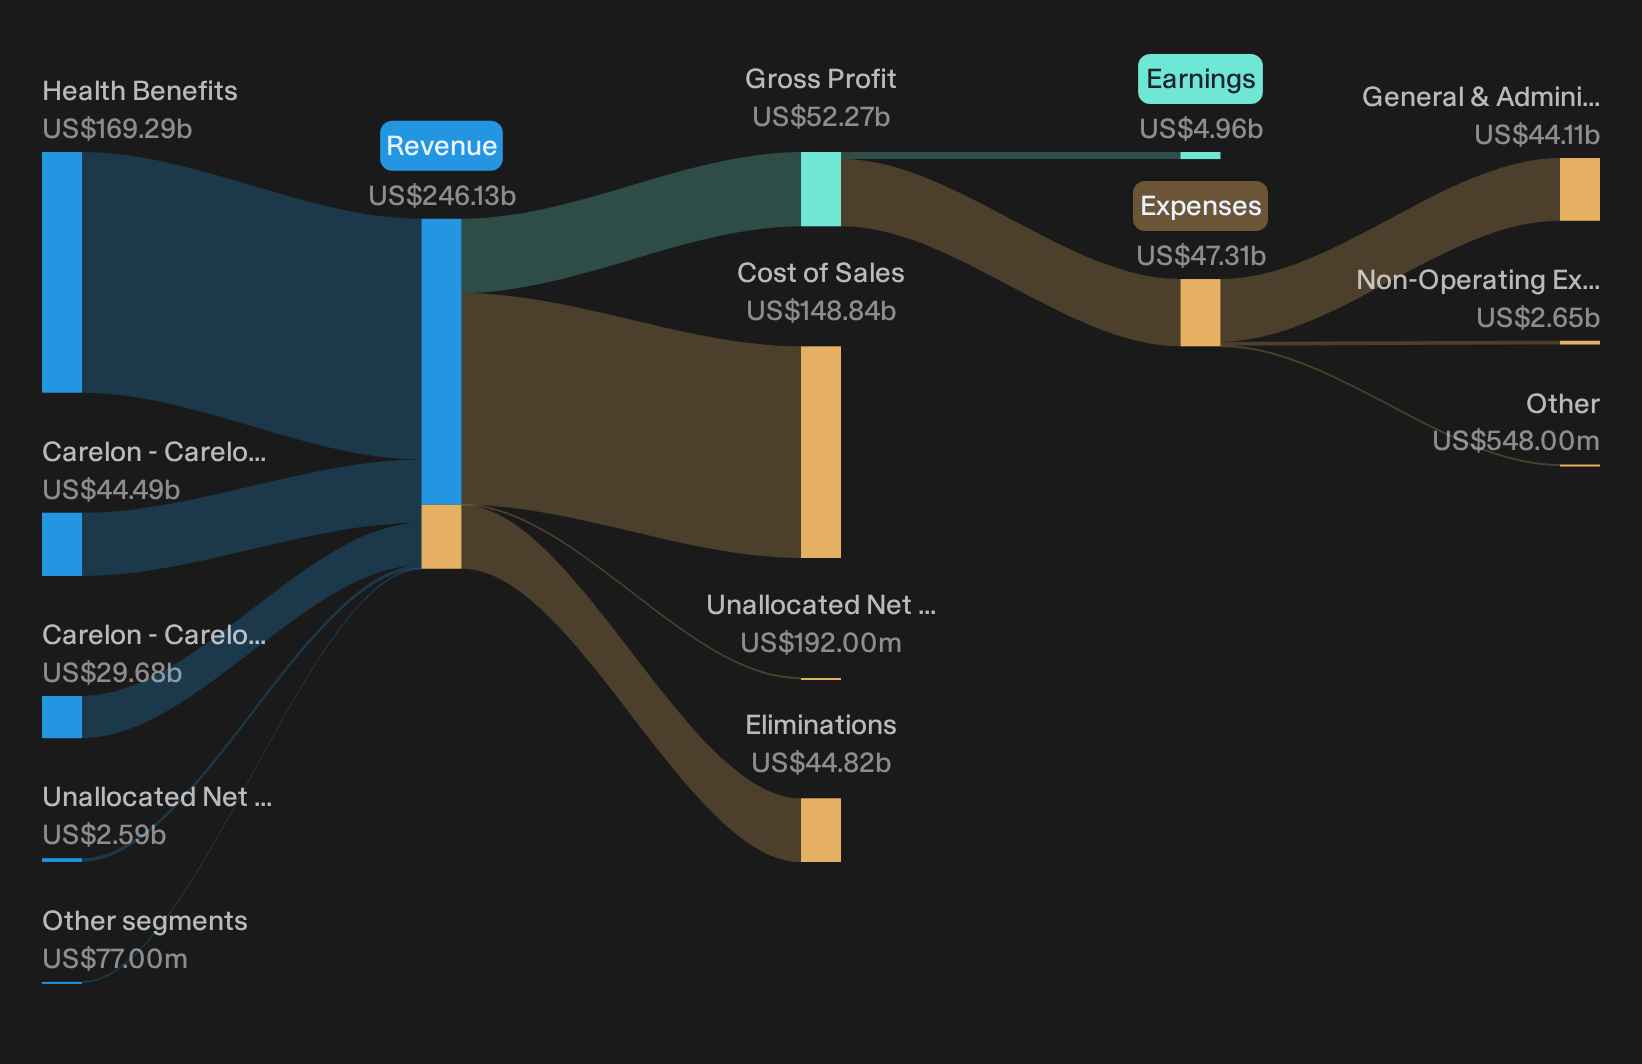
Elevance Health runs a broad U.S. health benefits platform spanning medical coverage, pharmacy services and care management, with Health Benefits generating about US$169.3b of revenue, Carelon Rx US$44.5b and Carelon Services US$29.7b, on a US$85.6b market cap foundation.
"Ongoing deployment of Elevance Health’s AI, analytics and digital platforms such as HealthOS and Sydney Health, including automated prior authorization and earlier visibility into medical cost trends, is expected to tighten medical cost management and support more stable net margins and earnings over time."
What really matters now is how one evolving pressure on its government programs shapes the next leg of its earnings mix.
That pressure point is exactly where the story gets interesting, and the full narrative for Elevance Health shows how Elevance Health could see that risk decouple from its AI gains.
Philip Morris International (PM)
Philip Morris International brings a different type of defensiveness to this screen, with inelastic nicotine demand and cash-rich operations that can help smooth returns when rate debates and growth scares hit sentiment.
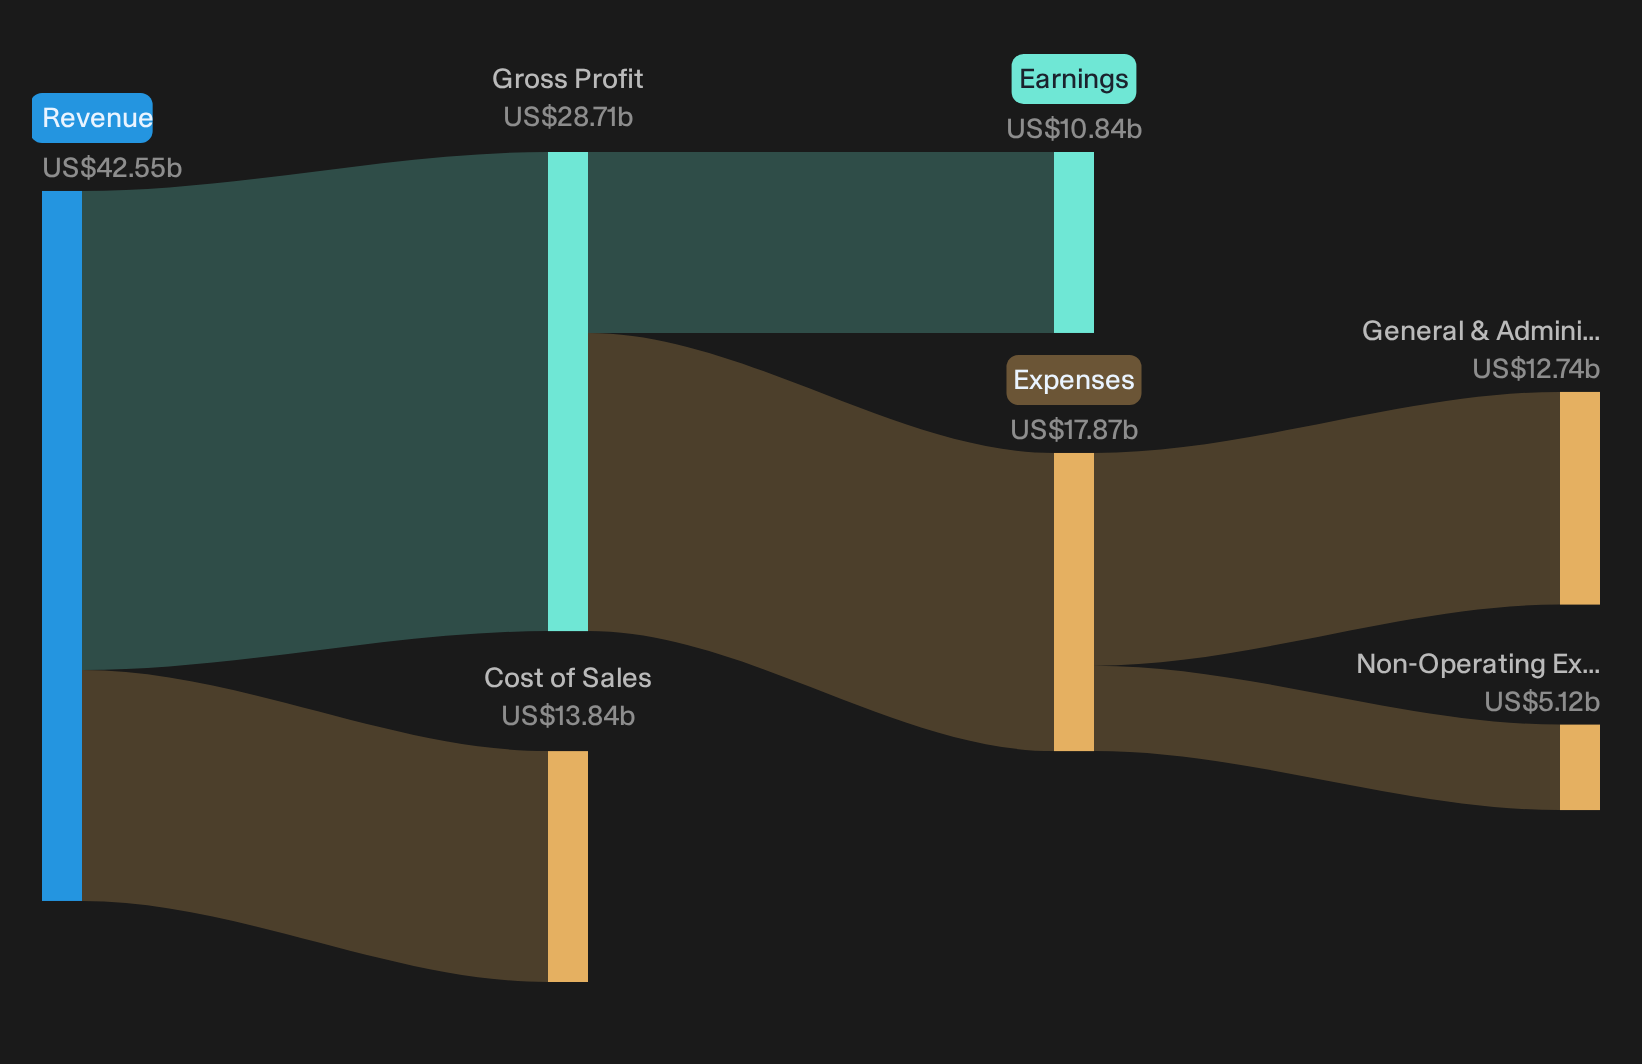
Philip Morris International is a global tobacco group selling cigarettes, smoke free nicotine products, accessories and wellness items to adult consumers, with a market value around US$302b. This fits the screener’s focus on large, profitable, cash generative businesses.
"The near completion of the US$2b gross cost savings program for 2024 to 2026, with more than US$1.8b already delivered and US$300m in savings recorded in the first half of 2026, suggests additional room for operating margin improvement if incremental efficiencies continue beyond the current target window and flow through to earnings."
What matters next is how one unresolved shift in Philip Morris International’s product mix shapes the durability of those earnings gains.
That product mix question is exactly where Philip Morris International gets interesting, and the full narrative for Philip Morris International shows whether cost savings are masking risk or accelerating a cleaner earnings engine.
Altria Group (MO)
Altria Group anchors the defensive screen as a U.S. tobacco heavyweight with long running cash generation that can appeal when rate policy feels unsettled and investors want income that is less tied to the economic cycle.
Altria Group, a US$115.4b tobacco group, sells Marlboro cigarettes along with Black & Mild cigars, Copenhagen and Skoal smokeless products, on! nicotine pouches and NJOY ACE e-vapor, drawing about US$17.7b from Smokeable Products and US$2.7b from Oral Tobacco Products, mostly in the United States.
"Altria faces challenges in the e-vapor category due to the prevalence of illicit products, which constitute over 60% of the market, limiting their ability to generate revenue from legitimate e-vapor products and impacting future revenue growth."
What happens to earnings power if a single regulatory shift changes how that contested corner of the nicotine market is policed and priced?
If that regulatory swing is what you are focused on, the full narrative for Altria Group illustrates where Altria Group’s risk could be masking an accelerating cash engine.

Seeking Alternatives Before The Crowd?
Fresh ideas can move fast. The right watchlist can catch breakouts with real momentum while others are still reacting to dropping prices and stale narratives, and help investors get in early.
- Target resilient income streams by scanning curated high-yield opportunities through the 6 dividend fortresses while they are still under the radar for now, before yields get compressed.
- Chase early upside by reviewing the 17 high quality undiscovered gems that remain largely uncrowded today, before buying interest potentially sends these under-followed stories higher.
- Position for potential infrastructure exposure by checking the 88 AI infrastructure stocks while capital is still rotating in slowly and entry prices remain workable.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com