
What Warner Music Group Stock Leadership Shakeup Means For Shareholders
- Warner Music Group has reshaped its recorded music leadership, appointing Sonny Takhar as chairman and CEO of Warner Music UK & Ireland from January 2027, while expanding roles for senior executives and confirming the upcoming departure of long serving leader Simon Robson.
- This reshuffle concentrates decision making for the UK, Ireland and North America under Val Blavatnik and aligns Warner Music Group’s local artist development, catalog distribution and ADA operations with a single executive layer. This change could influence how capital, technology and AI tools are deployed across key markets.
- We will look at how Warner Music Group's refreshed leadership bench, including Sonny Takhar, may reshape the existing investment narrative.
Scan how Warner Music Group's leadership overhaul compares to peers by lining up other content driven businesses in our hand picked list of 17 high quality undiscovered gems.
Warner Music Group Investment Narrative Recap
To own Warner Music Group, you need to believe the music ecosystem can keep monetising streaming, superfans and catalog in a way that supports both earnings and cash generation. The near term swing factor is whether current cost programs and AI tools like WMG Pulse translate into cleaner, less one off heavy profitability while catalog investments earn their keep.
The biggest risk still sits around execution on returns from past spending and the balance sheet, given debt is not well covered by operating cash flow and the dividend is not fully backed by free cash. The latest leadership reshuffle looks meaningful for governance and accountability but does not by itself change those financial pressure points.
The appointment of Sonny Takhar to run Warner Music UK & Ireland, reporting into Val Blavatnik with an expanded North America and corporate development remit, plugs directly into the core catalysts. The thesis around Warner Music Group leans on better artist development, tighter catalog exploitation and sharper use of AI and data across territories. This realignment pushes all of that under a more unified recorded music structure.
For you as a shareholder, the interest is less about the job titles and more about whether this management bench can turn that structure into a higher margin catalog mix, smoother execution of the Bain funded acquisition JV and more scalable AI driven monetisation from 2027 onward. The operational risk is that complexity rises and that cost savings or AI projects slip, which would matter given already stretched cash coverage of debt and dividends.
Warner Music Group's narrative projects US$8.5b revenue and US$943.7 million earnings by 2029. That aligns with analyst estimates of 5.4% yearly revenue growth and an earnings increase of about US$278.7 million from US$665.0 million today.
Discover how Warner Music Group's fair value points to a potential 34% upside from its current price before other investors act to narrow that gap.
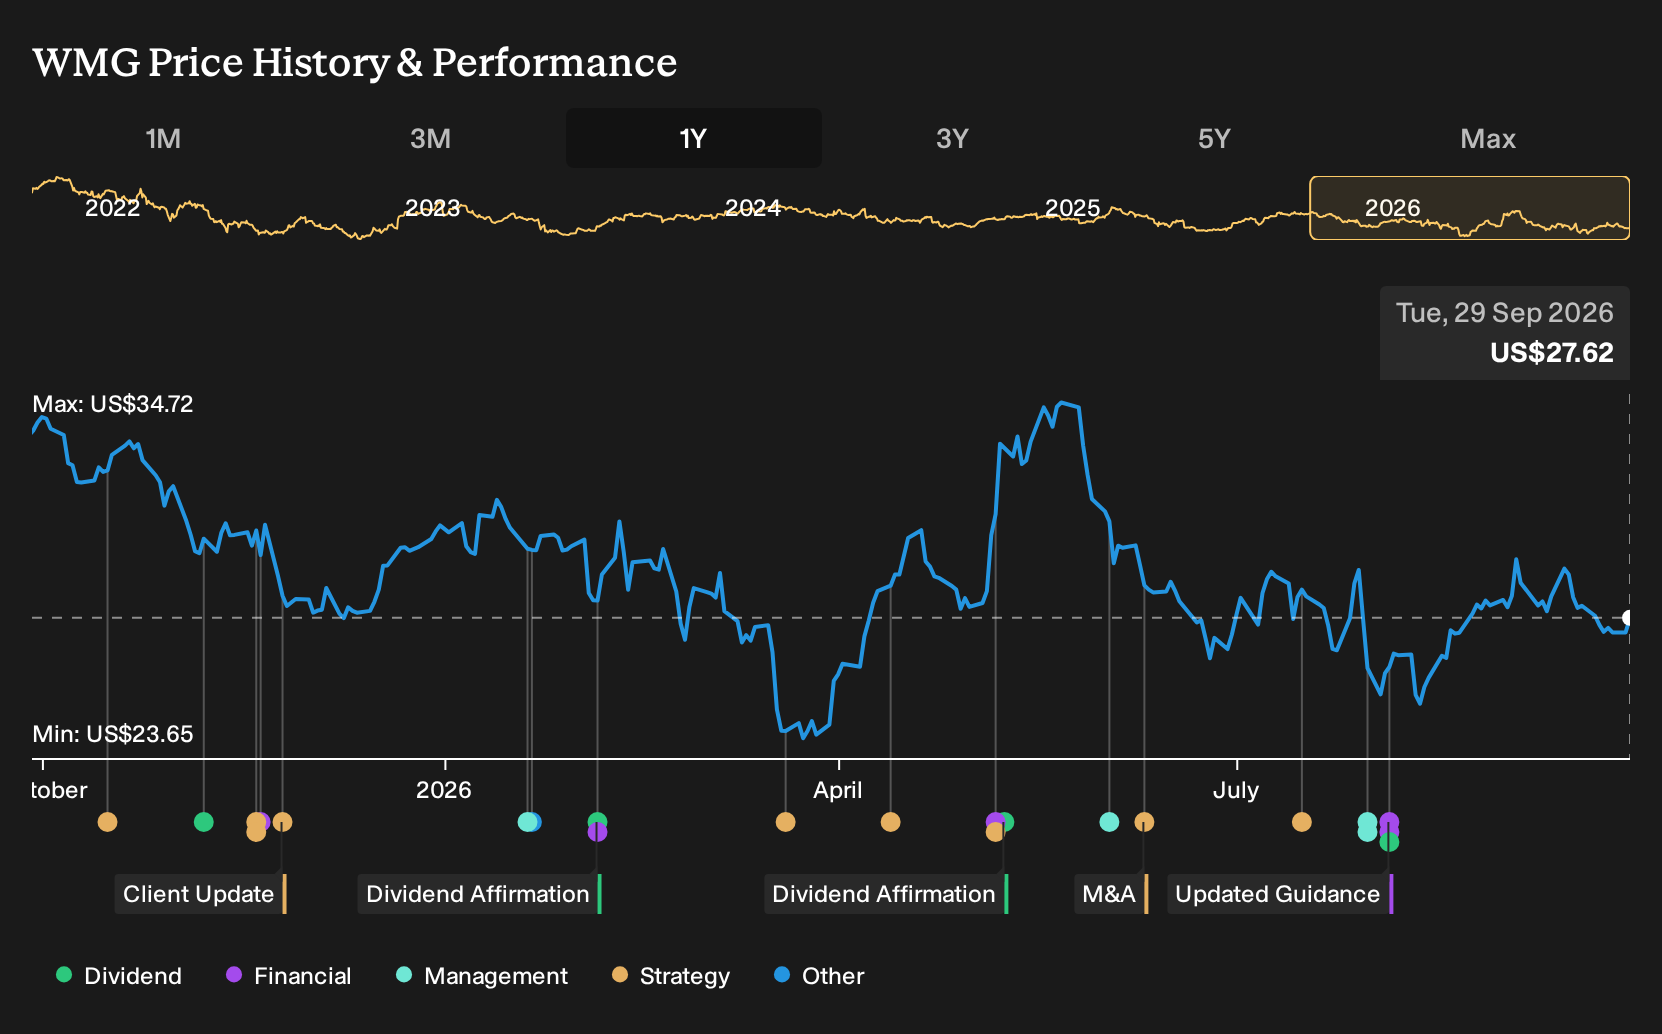
Exploring Other Perspectives
Some of the most optimistic analysts frame Warner Music Group’s AI partnerships as the real swing factor, not just cost cuts or catalog returns. Before this leadership news, that group was already mapping out 6.8% yearly revenue growth and earnings of about US$1.2b by 2029. You can compare those upbeat assumptions with more cautious views and decide which story feels closer to your own reading of the situation.
Explore 2 other Warner Music Group fair value estimates, including one that suggests as much as 60% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Warner Music Group research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Warner Music Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Warner Music Group's overall financial health at a glance.
Looking for more investment ideas beyond Warner Music Group?
Once you have a handle on Warner Music Group, it can help to widen the lens and line it up against other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you quickly scan for stocks that match the kind of balance sheet strength, valuation profile or income stream you want to focus on next.
- If you want income to do more of the heavy lifting in your portfolio, consider screening for companies offering resilient payout profiles using our 6 dividend fortresses.
- If capital preservation and steadier business models sit higher on your list, filter for companies with stronger financial footing through the 32 resilient stocks with low risk scores.
- If you prefer to hunt for underappreciated ideas with solid fundamentals, sort through the 17 high quality undiscovered gems and see which stocks deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com