
Domino's Pizza (DPZ) Leaves FTSE All World Index On A View It Looks Undervalued
Domino's Pizza (DPZ) was removed from the FTSE All-World Index (USD) on 19 September 2026, a change that often prompts institutional rebalancing and can shift trading volumes and liquidity around the stock.
Viewed over the past year, Domino's Pizza has seen its share price retreat sharply, with a year-to-date share price return of down 29.03% and a 1 year total shareholder return of down 28.58%. The recent 30 day share price return of down 13.77% suggests momentum has been fading, despite a 1 day gain of 3.26% and a 7 day share price return of 1.58% into the latest close at US$301.81.
Spot fresh ideas by comparing Domino's Pizza's recent slump and index removal with other consumer-focused businesses in our curated list of 32 high quality undervalued stocks.For Domino's Pizza, a sharp share price slide and index exit can signal deeper cracks in the business, or just sentiment swinging too far. The valuation work starts by separating those two stories.
Most Popular Narrative: 26% Undervalued
On the most followed valuation view, Domino's Pizza is priced below an implied fair value of $408.07, compared with the latest close at $301.81. This frames the recent share price weakness very differently from a simple de-rating story.
Domino's Pizza is a great brand, enjoying a wide moat that results in an operating margin of around ~20%. Given the maturity of the business, its revenue growth is below 10% but still modestly above the economy growth rate. Its franchise business model and disciplined capital allocation decisions also result in a stellar ROIC around 10 times its cost of capital. The reduction in shares outstanding over the last five years has also increased each shareholder's ownership stake ("pizza slice") in the company.
See why 12 investors see Domino's Pizza as 26% undervalued.
Result: Fair Value of $408.07 (UNDERVALUED)
Still, Domino's Pizza faces pressure if franchisees struggle with higher costs or if traffic weakens, which could challenge margins and the wide moat narrative.
Find out about the key risks to this Domino's Pizza narrative.
Another Take On Domino's Pizza Valuation
The SWS DCF model paints a different picture to the popular undervaluation story. On this view, Domino's Pizza at US$301.81 sits slightly above an estimated future cash flow value of US$295.82, which points to a modestly overvalued reading rather than a clear bargain. It raises a simple question for investors: Which cash flow path do you trust more?
Anyone weighing these two signals may want to see how the modeling works in more detail, and how sensitive it is to small tweaks in growth or discount rate assumptions, before leaning too heavily on either result. Look into how the SWS DCF model arrives at its fair value.
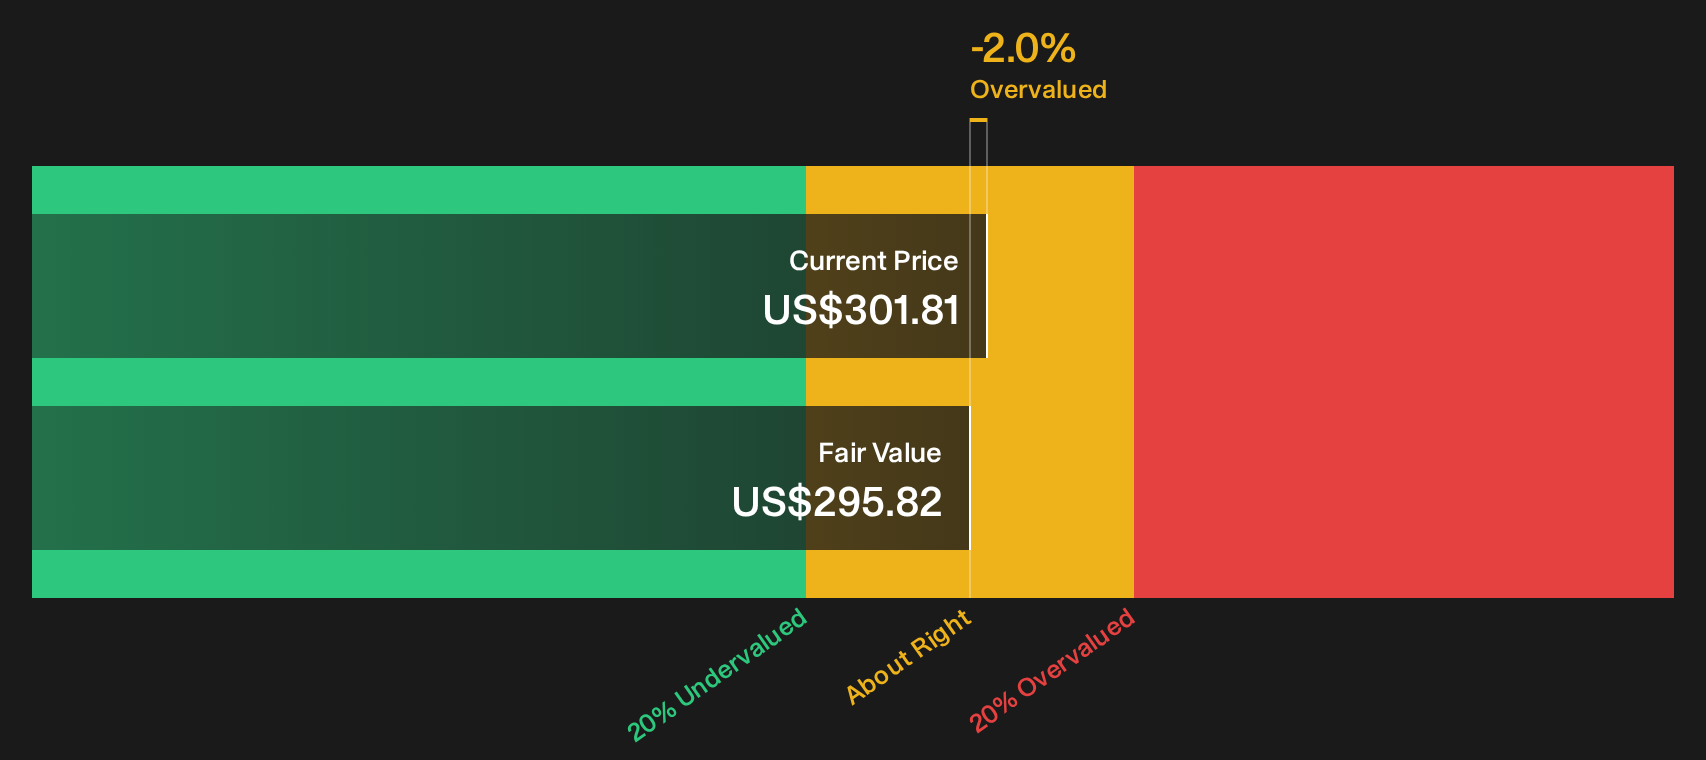
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Domino's Pizza for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between Domino's Pizza looking cheap on one model and stretched on another is normal for this kind of setup. Move quickly to check the underlying data, weigh the 5 key rewards against the 2 important warning signs, and shape your own view with 5 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Domino's Pizza?
If Domino's Pizza has you rethinking your watchlist, use that momentum. Let fresh data driven ideas challenge your assumptions and broaden your opportunity set.
- Target resilient balance sheets by scanning companies on the list of solid balance sheet and fundamentals (25 results) that pair financial strength with room for upside.
- Hunt for mispriced opportunities using the 32 high quality undervalued stocks to surface businesses where fundamentals and market expectations appear out of sync.
- Spot early stage potential by reviewing the 17 high quality undiscovered gems before the crowd pays attention and prices in the full story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com