
Learn Why The Bull Case For Incyte (INCY) Could Change Following Rare Disease Drug Approval
- Mirum Pharmaceuticals and Incyte reported that the FDA approved Atebrioz (zilurgisertib), an oral ALK2 inhibitor for Fibrodysplasia Ossificans Progressiva in patients 12 and older, alongside a Rare Pediatric Disease Priority Review Voucher for Incyte.
- The Atebrioz decision adds a rare disease therapy and a Priority Review Voucher to Incyte’s toolkit, which can influence its product mix, regulatory timing, and long-term capital allocation choices.
- We will now look at how Incyte's investment narrative could be affected by the Atebrioz approval and Priority Review Voucher.
Scan how Incyte’s rare disease win compares with other potential breakout opportunities in 17 high quality undiscovered gems across the market.
Incyte Investment Narrative Recap
To own Incyte, you need to believe that it can turn a concentrated portfolio led by Jakafi into a broader mix of dermatology, oncology and rare disease products that keeps earnings resilient even as key patents age. The Atebrioz approval and attached priority review voucher help that story at the margin, but they do not change the fact that the most important near term catalyst remains execution on existing launches such as Opzelura.
The biggest risk still sits in pipeline delivery and cost discipline. R&D and SG&A are running high, and consensus expects earnings and revenue to decline over the next three years. Atebrioz adds another approved asset, yet it does not remove the pressure on management to convert late stage programs into sizeable, commercially efficient franchises.
The Atebrioz win matters most when viewed next to Incyte’s broader inflammatory and autoimmune franchise around Opzelura and povorcitinib. Data scheduled for EADV 2026 across atopic dermatitis, hidradenitis suppurativa, prurigo nodularis and vitiligo speak directly to whether dermatology can carry more of the load as Jakafi eventually matures. Stronger real world and long term safety evidence can support that shift.
For catalysts, the priority review voucher from Atebrioz gives Incyte more flexibility in timing a future filing, which could influence how quickly a later asset reaches the market. The EADV data set is also operationally important because it touches on treatment durability, quality of life and potential treatment sequencing, all of which shape payer discussions and the profit profile of Opzelura and any follow on IAI products.
Incyte's narrative projects US$5.8b revenue and US$1.2b earnings by 2029. This implies relatively flat annual revenue trends and an earnings decline of about US$400m from US$1.6b today.
Discover why Incyte's fair value indicates a 4% potential upside to its current price that may not last much longer.
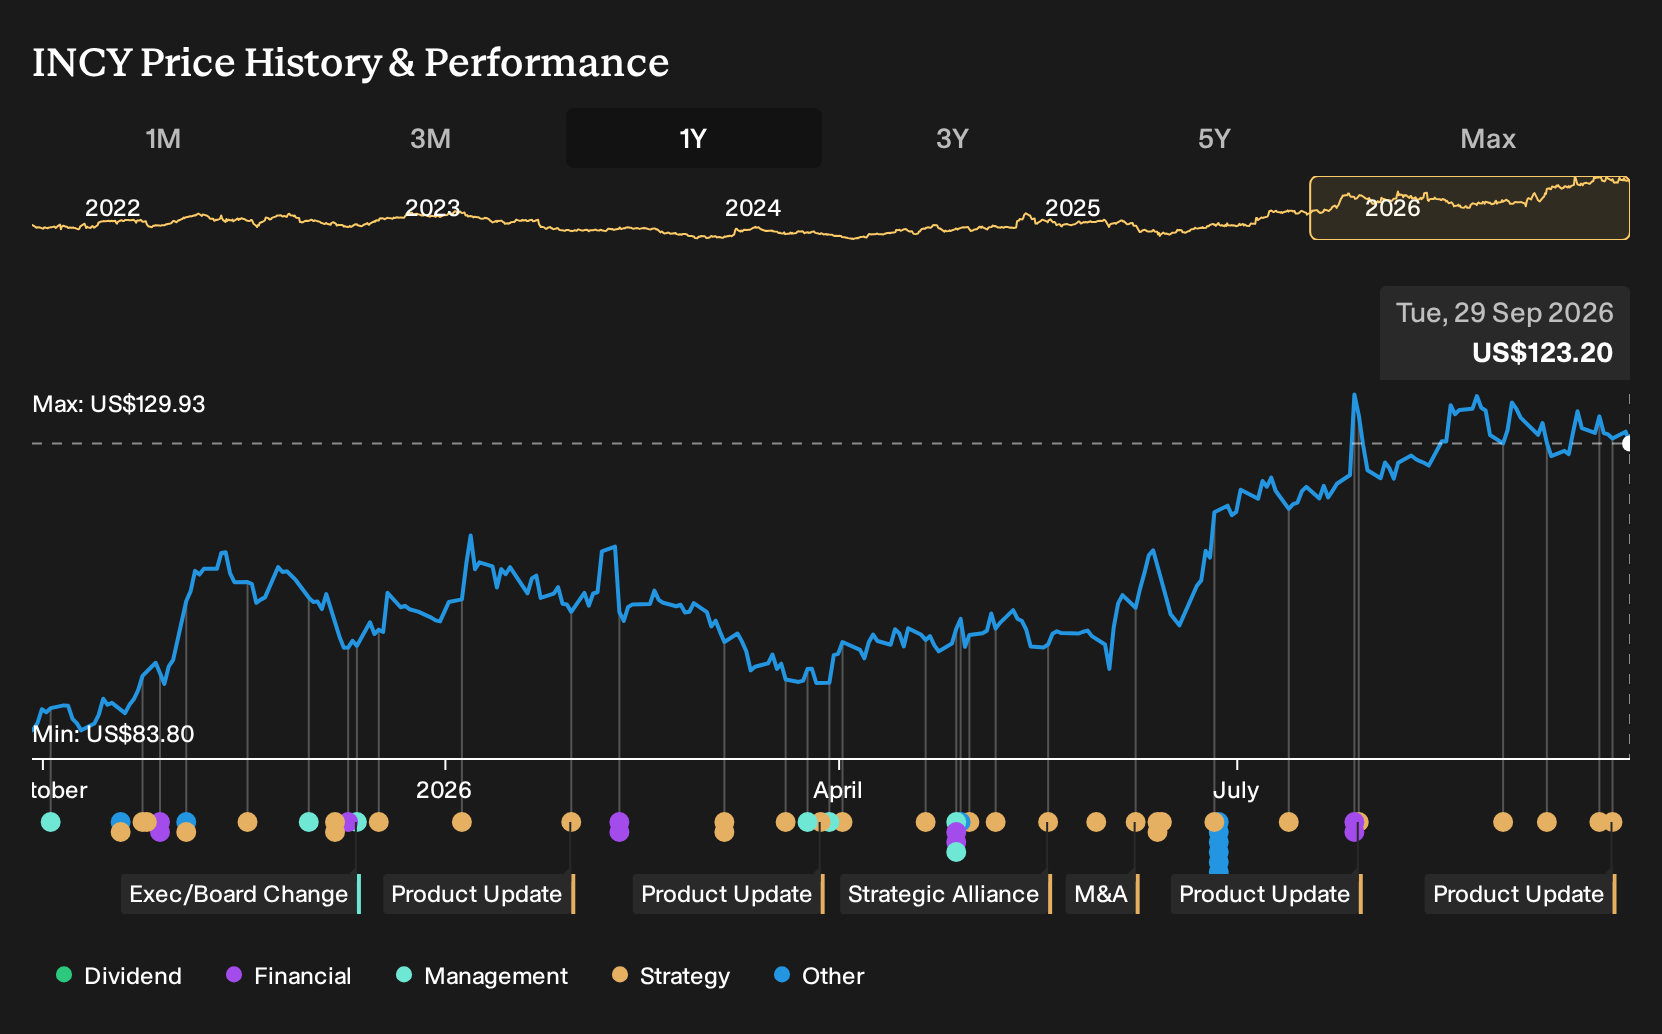
Exploring Other Perspectives
One alternate view on Incyte centers on cost risk. The most pessimistic analysts were already assuming revenue would slip about 2.5% a year and earnings would drift toward US$1.2b by 2029, rather than the US$2.2b some peers penciled in. With Atebrioz and the voucher now approved, those narratives may shift in very different directions. Readers like you can compare both sets of expectations and decide which story feels more realistic.
Explore 4 other Incyte fair value estimates, including one that suggests as much as 25% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Incyte research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Incyte. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Incyte's overall financial health at a glance.
Looking for more Incyte investment ideas and peers?
If the Incyte story has sharpened your thinking but you want a wider watchlist, the Simply Wall St Screener can help you line up other stocks that fit different priorities while keeping the work manageable.
- If resilience matters most to you, start with companies that score well on balance sheet strength by reviewing the list of solid balance sheet and fundamentals (25 results).
- For investors who care about both quality and price, scan a curated set of potentially mispriced opportunities through the 32 high quality undervalued stocks.
- If capital preservation is front of mind, narrow your focus to companies that our model tags with relatively low risk scores using the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com