
Amerant Bancorp (AMTB) Closes $50 Million Note Deal As Fair Value Sits Just Ahead
Amerant Bancorp (AMTB) just closed a US$50 million offering of 7.00% senior notes due 2031, adding a new layer of unsecured funding that could influence leverage, liquidity and share repurchase capacity.
The senior notes arrive after a strong run in Amerant Bancorp’s equity, with the share price delivering an 11.35% 90 day return and a 47.79% year to date share price return. The 1 year total shareholder return of 53.63% points to momentum that investors will now weigh against higher unsecured funding in the capital structure.
Scan how Amerant Bancorp’s new debt stack compares with peers by reviewing our hand picked list of list of solid balance sheet and fundamentals (25 results)
After a rapid share price move and a new 7.00% senior note on the books, Amerant Bancorp now trades between a US$29.13 quote, a US$31.88 target and a deeper intrinsic discount. Where does a reasonable fair value anchor in that spread?
Most Popular Narrative: 9% Undervalued
Amerant Bancorp’s most followed narrative points to a fair value of $31.88, a little above the $29.13 close. This puts the new 7.00% senior notes against a backdrop of earnings recovery and balance sheet work.
Improvement in the net interest margin (NIM) and net interest income (NII), primarily resulting from higher yielding loan production and lower deposit costs, suggests enhanced profitability and operational efficiency, positively impacting earnings. The decrease in higher cost deposits and the strategic replacement with lower-cost funds point towards improved cost management and enhanced net interest margins, further contributing to the bank's profitability.
See why 0 investors see Amerant Bancorp as 9% undervalued.
Result: Fair Value of $31.88 (UNDERVALUED)
Still, rising nonperforming loans and higher provisions for credit losses could quickly challenge the Amerant Bancorp profitability story that underpins the 9% undervaluation narrative.
Find out about the key risks to this Amerant Bancorp narrative.
Another View on Amerant Bancorp’s Valuation
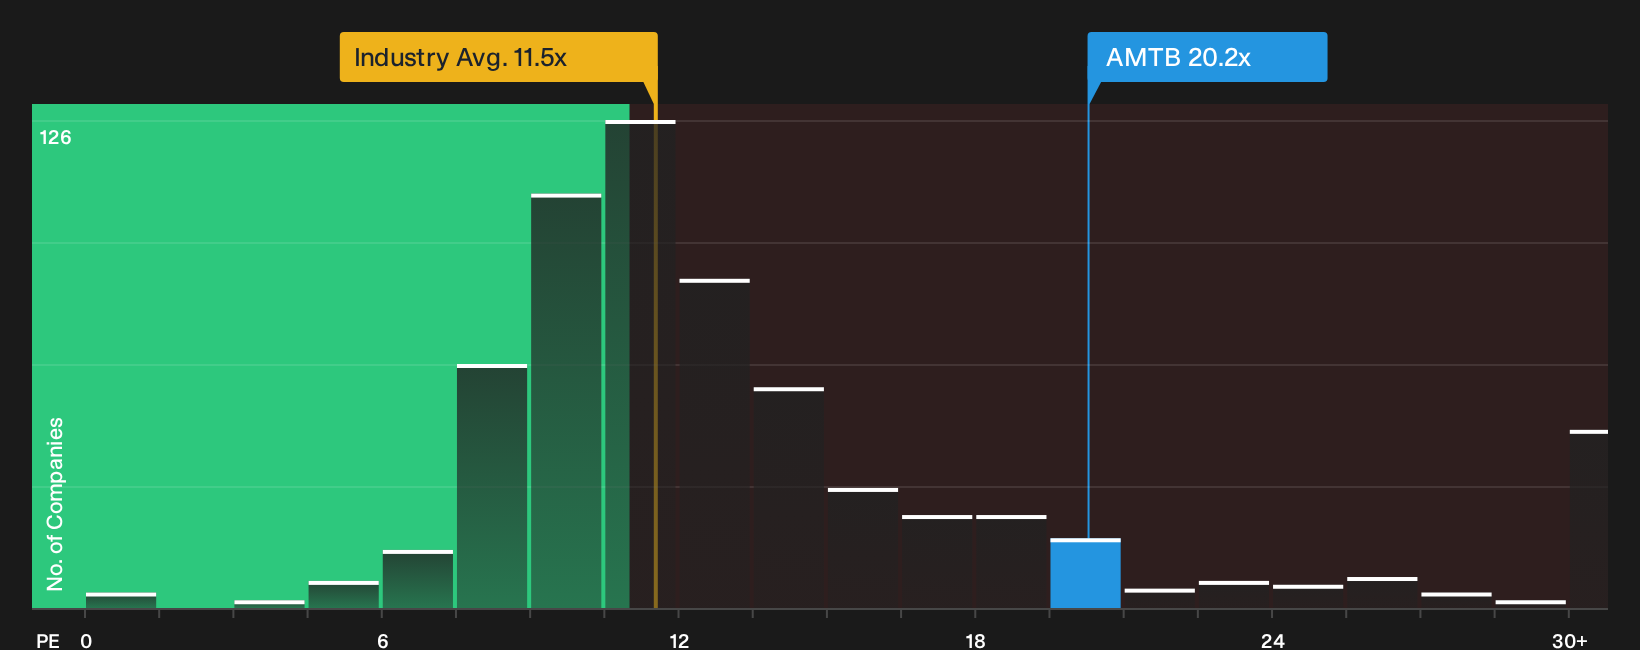
On earnings multiples, Amerant Bancorp looks less generous. The stock trades on a P/E of 20.2x, compared with 11.6x for the US Banks industry and 11.9x for peers, while the fair ratio sits lower at 16.6x. That gap increases valuation risk if sentiment cools.
For a cleaner look at what these earnings multiples imply over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Amerant Bancorp’s value story. If you want to move quickly and form your own view, start by weighing its 3 key rewards and 2 important warning signs
Looking for more Amerant Bancorp investment ideas?
If Amerant Bancorp has sharpened your focus, now is the moment to broaden your watchlist with a few carefully filtered opportunities that fit different objectives.
- Target resilient performers by scanning a curated set of 32 resilient stocks with low risk scores that aim to keep volatility in check while still offering meaningful business exposure.
- Hunt for pricing gaps by reviewing a focused group of 32 high quality undervalued stocks where fundamentals and current quotes appear out of sync.
- Spot future contenders early by tracking a hand picked pool of 17 high quality undiscovered gems before they land on every investor’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com