
How Investors Are Reacting To AMETEK (AME) Mobile Capture Launch
- Manifold Tech Limited recently announced a collaboration with AMETEK's FARO INSIGHT business to launch Rovi i.1, a mobile reality capture device that feeds spatial and visual data into the FARO Sphere XG cloud platform for processing, visualization and collaboration.
- The partnership gives AMETEK another way to integrate its digital reality tools into workflows across construction, industrial facilities, public safety and cultural heritage, which can matter for recurring software usage and data-rich service demand over time.
- This article will examine how AMETEK's investment narrative around high margin digital platforms is shaped by the Rovi i.1 capture launch.
Scan beyond AMETEK and this FARO INSIGHT tie-up by reviewing a curated group of industrial and tech enablers in our 93 robotics and automation stocks that powers automation and spatial computing workflows.
AMETEK Investment Narrative Recap
For an investor to stay with AMETEK, the core belief is that this is a high margin instrumentation and electronics group that can keep compounding through niche platforms, recurring software and disciplined acquisitions. The Manifold Tech and FARO INSIGHT Rovi i.1 launch fits that story, but on its own it does not look like a major near term swing factor.
The more immediate swing issue remains whether execution across AI related data center, defense, aerospace and power infrastructure orders translates into the earnings growth analysts model, against a premium P/E where sentiment can adjust quickly. The main risk is that any slowdown or margin pressure in less discussed legacy areas undercuts that thesis.
The Rovi i.1 collaboration with Manifold Tech plugs into the same digital reality and automation themes that underpin AMETEK’s push in higher value instrumentation and software rich platforms. It supports the idea that AMETEK is leaning into data heavy workflows where recurring usage and integration into customer processes can matter more than one off hardware sales.
Because this device feeds into FARO Sphere XG, it also broadens the Capture, Cloud, Application loop investors already watch as a potential source of stickier software and services revenue. The key execution watchpoints are adoption in core verticals such as construction, industrial facilities and public safety, and whether these digital tools scale fast enough to offset any slower areas in the wider portfolio.
AMETEK's current analyst script points to revenues of $11.3b and earnings of $2.3b by 2029, based on an assumed 12.7% yearly revenue growth rate and an increase in earnings of about $0.7b from $1.6b today.
Uncover how AMETEK's fair value indicates an 11% potential upside to its current price before the market closes that discount.
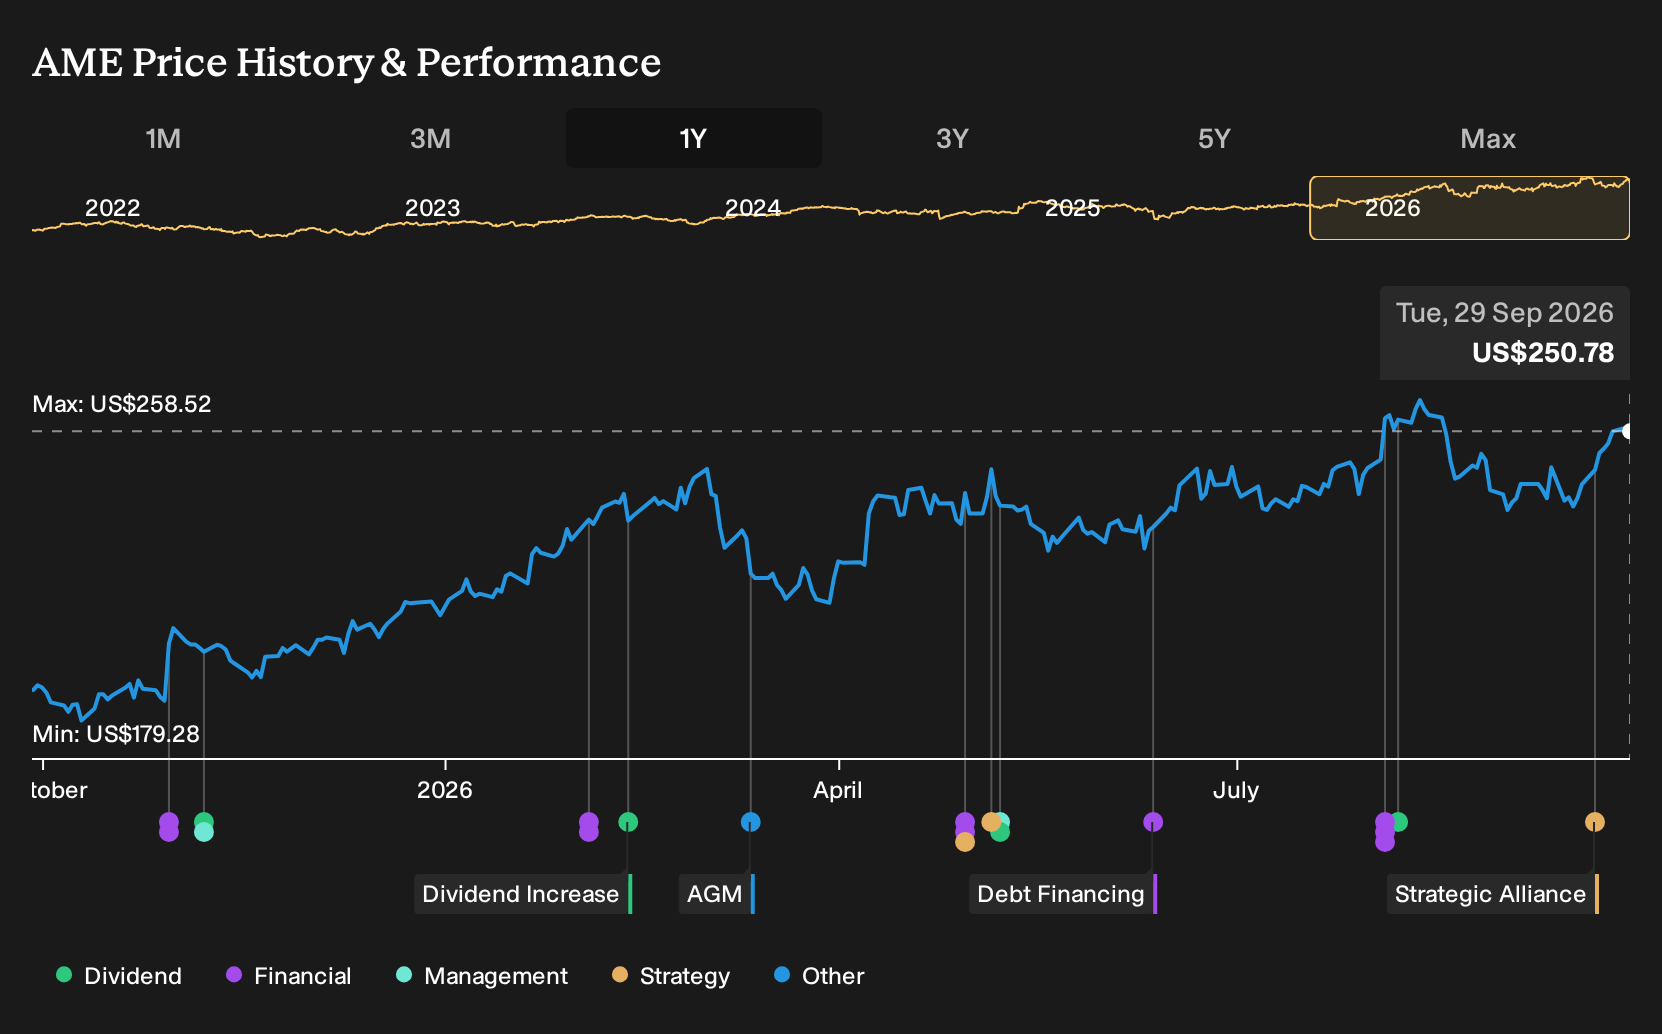
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$183.06 and US$278.33, so some retail investors see AMETEK as close to fully valued, while others price in a far richer scenario. Set that against premium P/E risk and sector wide multiple compression, and you get very different conclusions about upside. Use that spread as a prompt to explore several alternative viewpoints before leaning on any single narrative.
Explore 2 other AMETEK fair value estimates, including one that suggests as much as 27% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Instead, dig into the data and build a conviction that's truly your own.
- A great starting point for your AMETEK research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for AMETEK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMETEK's overall financial health at a glance.
Looking For More Ideas Beyond AMETEK?
If AMETEK has sharpened your thinking about quality, pricing power and recurring revenue, use that same lens to sift through a wider set of opportunities using the Simply Wall St Screener.
- For investors who care about payout strength and consistency, review 6 dividend fortresses that might suit an income focused portfolio.
- If stability and capital protection sit higher on your priority list, consider companies in our 32 resilient stocks with low risk scores to see which businesses align with a lower volatility profile.
- For those searching for potential future leaders before they are widely followed, check our 17 high quality undiscovered gems and see which fundamentals catch your eye.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com