
Did Earnings Estimate Upgrade Just Shift Illinois Tool Works Stock Investment Narrative?
- Illinois Tool Works recently received an analyst ranking upgrade to Zacks Rank #2, following an upward trend in earnings estimates that points to increased confidence in the company’s underlying profit potential.
- The key insight is that improving earnings projections hint at supportive demand and cost execution across Illinois Tool Works’ diversified industrial portfolio, rather than a shift driven purely by sentiment.
- We will now look at how Illinois Tool Works’ investment narrative intersects with the recent improvement in earnings expectations and analyst confidence.
Scan how Illinois Tool Works’ earnings upgrade compares with other industrials by reviewing it alongside hand-picked 32 resilient stocks with low risk scores that analysts currently view as relatively resilient.
What Is Illinois Tool Works' Investment Narrative?
To own Illinois Tool Works, you need to be comfortable with a mature industrial group that leans on disciplined execution more than explosive expansion. The business is diversified across autos, construction, welding, food equipment and more, with earnings forecast to grow 5.5% per year and revenue projected to rise 3.6% per year. That points to a story built on pricing, product mix and cost discipline, not big volume surges. The recent earnings estimate revisions and Zacks Rank upgrade simply echo that view rather than redefine it.
In the short term, the key swing factors look operational. Net profit margins of 19.4% sit below last year’s 21.3%, while earnings over the past year declined 5.1%, even as the stock has trailed the broader US machinery space. You also have a capital intensive model and a high level of debt, with 100% of liabilities from higher risk funding sources. The stock trades on a 23.8x P/E, just under peers, and supports a 2.58% dividend, so the bar on execution stays reasonably high. The analyst upgrade fits into this as a confidence check on that steady compounder narrative rather than a catalyst in its own right.
That said, there is a less obvious pressure point in Illinois Tool Works’ setup that could matter a lot if ...
There's only one way to know the right time to buy, sell or hold Illinois Tool Works. Head to Simply Wall St's company report for the latest analysis of Illinois Tool Works's Fair Value.
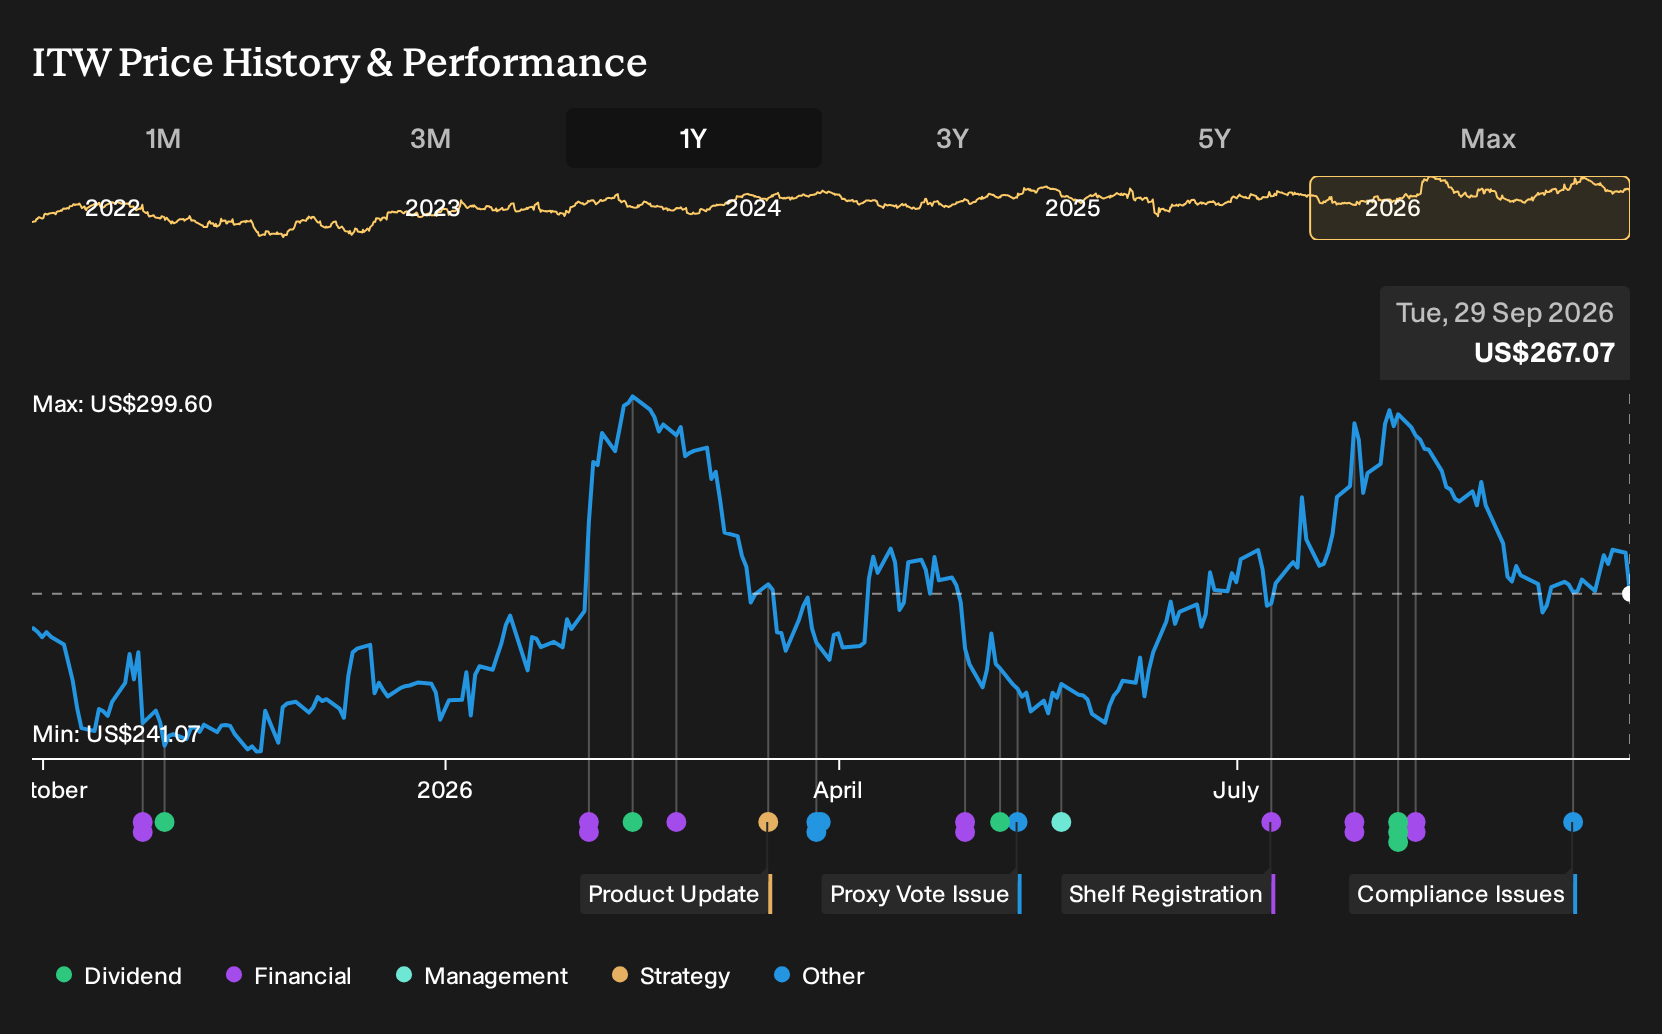
Exploring Other Perspectives
Illinois Tool Works attracts split opinions inside the Simply Wall St Community, with two fair value estimates stretching from US$172.69 to US$302.50. These views were formed before the recent Zacks Rank upgrade, so treat them as a pre-upgrade snapshot and use them as a starting point to explore sharply different valuation angles.
Explore another Illinois Tool Works fair value estimate, including one that suggests as much as 35% downside from the current price!
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Illinois Tool Works research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Illinois Tool Works. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Illinois Tool Works' overall financial health at a glance.
Looking For More Investment Ideas Beyond Illinois Tool Works?
Once you have formed a view on Illinois Tool Works, it helps to compare that thinking with other listed businesses that share similar qualities or offer something very different. The Simply Wall St Screener can surface targeted shortlists so you spend less time trawling tickers and more time weighing the trade offs that matter.
- If you care most about capital preservation and steadier profiles, start with a 32 resilient stocks with low risk scores that filters for resilience and fewer red flags.
- If value is your main angle, review a 32 high quality undervalued stocks that highlights companies with stronger fundamentals than their current pricing suggests.
- If income is front and center in your plan, focus on a 6 dividend fortresses that concentrates on higher yielding payouts screened for durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com