
What Has Actually Changed At Southern Copper?
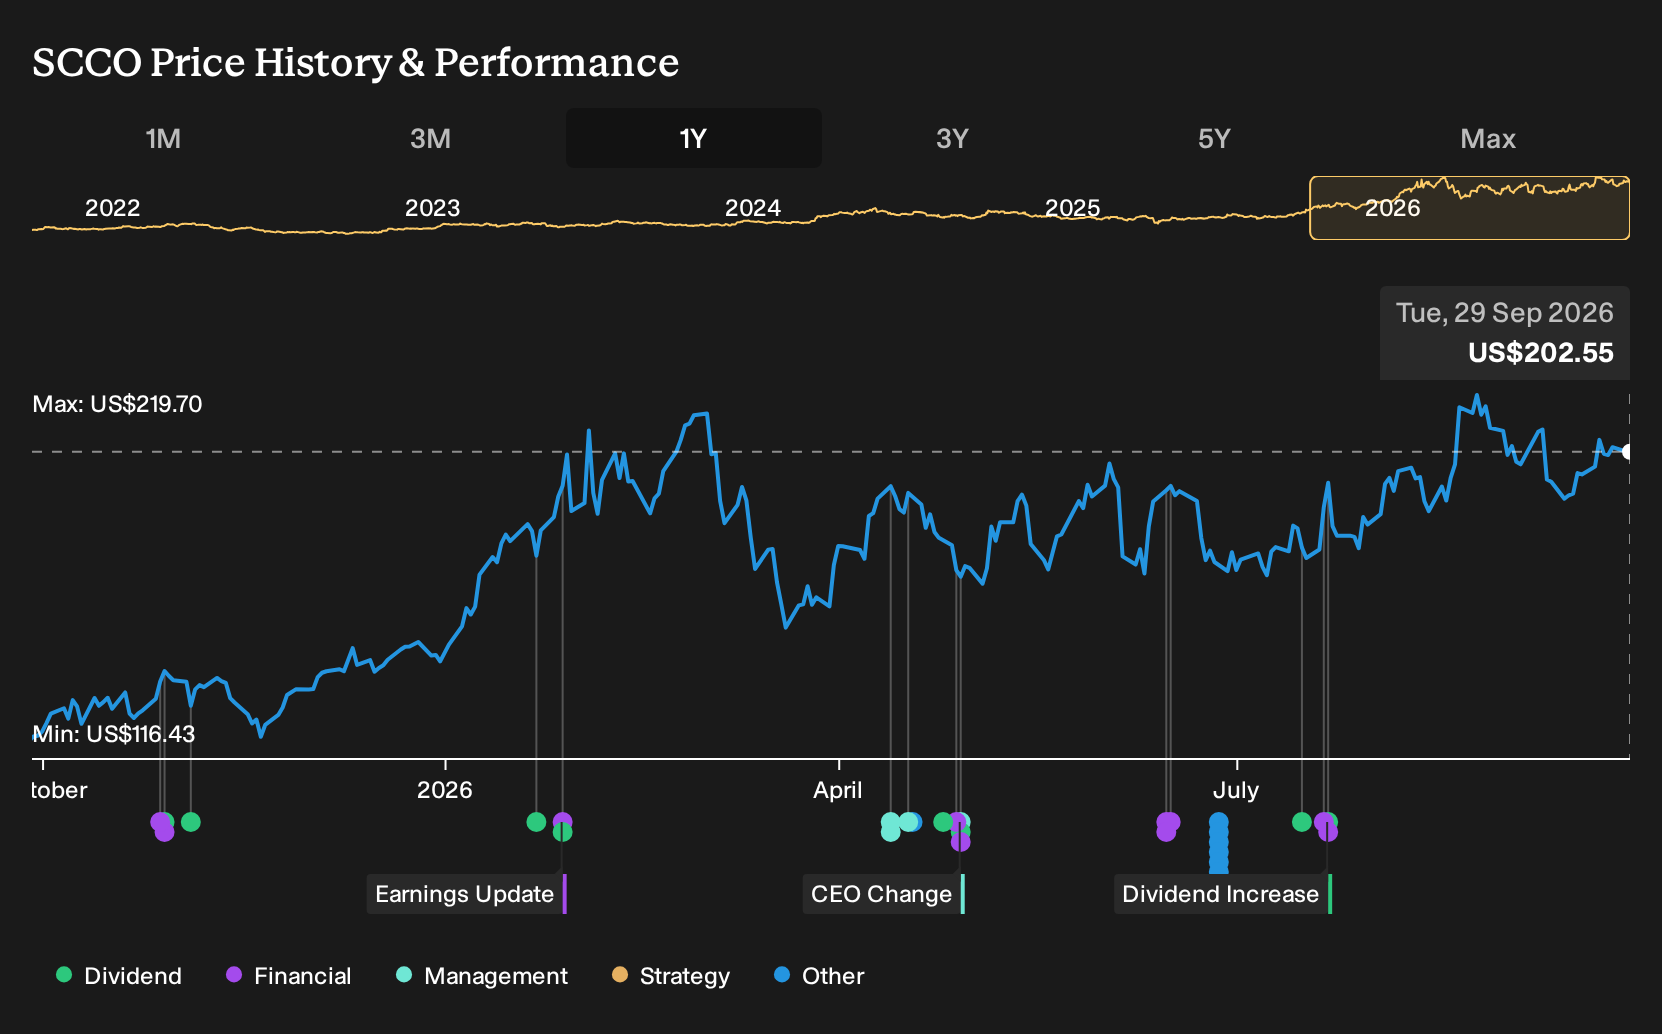
If you only skimmed the headlines about regulatory setbacks in Peru or leadership change at Southern Copper, the recent share move might look puzzling. Investors who held Southern Copper over the past year are up 77.4%, including dividends. If you had been weighing the bullish talk about Tía María and green demand against warnings on tariffs, politics, and rich valuation, what exactly in the record back in late 2025 justified taking that risk?
The move put Southern Copper in the middle of this trade. Scan 17 top copper producer stocks for other companies exposed to it.
The Two Southern Copper Stories Investors Were Arguing About
The shares cost US$121 at the start of the period, and anyone looking at Southern Copper then had to choose which story felt more plausible.
The bullish narrative saw a Fair Value of US$130, a price level that depended on projects like Tía María and Los Chancas lifting copper output and keeping cash costs near US$0.75 to US$0.80 per pound.
The more cautious camp worked off a Fair Value of US$95.69 and focused on risks such as US China trade conflict, potential tariffs, and more than US$15b of planned capital spending in Mexico and Peru.
What The Results Changed For The Southern Copper Debate
Southern Copper beat both narratives on profitability. Revenue moved from US$3,051m in Q2 2025 to US$4,289m in Q2 2026, while net income rose from US$973.4m to US$1,670m and net margin widened from 31.9% to 38.9%. Those figures supported the bullish case on low costs and strong pricing, although ongoing Peru and tariff risks meant the evidence still cut both ways.
The useful takeaway is simple. When a story leans on cost discipline and pricing power, track net margin alongside volume headlines and project news, and then test whether it is actually widening over time.
What Southern Copper's Rally Is Asking You To Believe
Southern Copper now trades at US$203, after a 77.4% gain over the past year, and the selected Narrative’s Fair Value sits below that level. The Narrative frames this gap around how much faith you place in current profitability and copper pricing holding up against tariff noise and project friction.
For today’s price to feel reasonable, you would be assuming that cost discipline, copper demand, and project execution offset weaker molybdenum prices and any future delays in Peru and Mexico.
"Rising copper surplus and weak demand may pressure prices, affecting revenue despite potential economic measures from key consumers. Delays in projects and falling molybdenum prices could hinder Southern Copper's growth and profitability, impacting net margins and revenue expectations."
The price and this Narrative do not agree. → Uncover what this Narrative says Southern Copper is actually worth
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 37% below our estimate - benefits from tight vessel supply as offshore projects require more capacity.
- Company 2 - 29% below our estimate - ramps aluminum flat rolled and recycling operations focused on higher value tariff-protected demand.
- Company 3 - 43% below our estimate - expands alternative payment options enabling large merchants to accept diverse local methods.
That is three of the list. See all 32 potentially undervalued companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com