
Does Pfizer (PFE) Look Fairly Valued As Cancer Data Builds?
Pfizer has delivered a solid 1 year return and continues to feature in headlines, which puts a fresh spotlight on whether the current share price lines up with what its earnings can support. With the stock around US$28.72, the key issue is how that market tag reflects the profitability of the underlying business.
- Over the past 12 months the stock returned 20.6%, which raises the question of whether that gain is already fully backed by Pfizer's earnings power.
- Recent oncology updates, including a slate of data presentations and late stage cancer drug candidates, can shape how investors think about the drug maker's future profit mix and the durability of its earnings base.
- There is a second opinion on Pfizer worth weighing. See what analysts think Pfizer's shares could be worth.
The stock's next move may depend on whether today's valuation multiples on Pfizer are well supported by its current and expected earnings stream.
If you are weighing Pfizer against other opportunities that focus on earnings support, a targeted stock screen built around 32 high quality undervalued stocks can be a useful next step in your research.
Does Pfizer Look Pricey on Earnings?
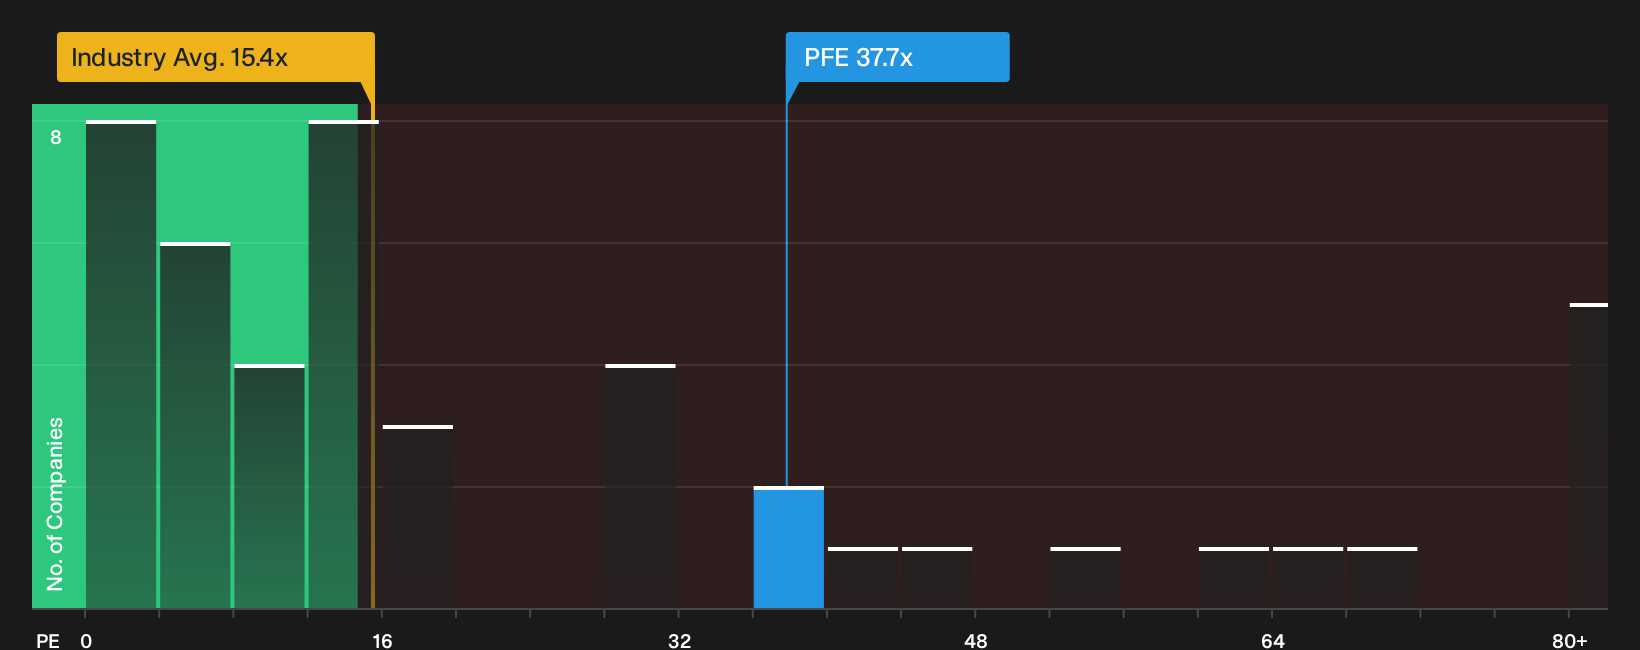
The P/E ratio is a useful yardstick for Pfizer because earnings still anchor how investors judge a large, mature drug maker. At roughly 37.7x earnings, Pfizer trades well above the broader pharmaceuticals sector, where the average P/E is about 15.4x, and it also sits below a peer group average near 56.6x, which often includes higher growth or more specialized businesses.
Despite the recent oncology news that highlights a busy late stage cancer pipeline and keeps attention on future drug launches, the current P/E sits above the level suggested by a tailored fair multiple that factors in Pfizer's profitability profile, size and risk mix. As a result, the shares screen overvalued on this framework. That kind of premium puts pressure on future results to justify the valuation, so anyone considering the stock will likely want to weigh how resilient the existing portfolio looks alongside the odds of that pipeline turning into durable earnings. Explore the numbers behind Pfizer's P/E valuation.
The Pfizer Narrative: What Would Justify Today's Price?
Pfizer's current P/E leaves a clear puzzle, and Simply Wall St Narratives on the Community page are built to spell out what kind of future for growth, margins and earnings would need to unfold for that valuation to look materially higher or lower than today’s price. Each scenario links a fair value estimate to a specific mix of potential catalysts and risks, so you can see which storyline seems closer to how Pfizer's actual results evolve over time.
The community is broadly aligned that Pfizer looks roughly fairly valued today, although the bullish side sees more earnings support in the newer franchises than the cautious camp.
Bull case: roughly fairly valued
"Expansion of launched and acquired products, including Seagen and Biohaven portfolios that generated US$3.2b of Q2 2026 revenue and grew at double digit rates..."
Discover why this Narrative puts Pfizer at roughly fairly valued.
Bear case: roughly fairly valued
"O 'patent cliff' maior se concentra entre 2026-2030, com até US$ 17-18 bilhões em receitas anuais em risco de drogas como Eliquis, Vyndaqel, Prevnar, Ibrance e Xtandi enfrentando genéricos..."
Explore why this Narrative puts Pfizer at roughly fairly valued.
One more Pfizer question before you move on
The people setting Pfizer's priorities, deciding where to spend and how hard to push the pipeline, and the way they are financially rewarded, can be just as important as any multiple or model. See who runs Pfizer and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com