
Corning (GLW) Stock Could Be 22% Undervalued On Fresh AI Connectivity News
Corning has seen its stock price climb sharply in recent years, so the obvious question now is whether the cash the business is expected to generate can really support where the shares trade today.
- Over the past 3 years, Corning has returned about 4.6x, which puts a lot of weight on whether its future cash flows can live up to the expectations now embedded in the share price.
- The recent collaboration with Lumentum and Qualcomm on high density optical interconnects for AI systems may support investor hopes for stronger long term cash generation from Corning's connectivity business.
- If you'd rather focus on earnings, this one's for you. See why Corning's 72.0x P/E tells a different valuation story.
The issue now is whether a Discounted Cash Flow (DCF) view of Corning's cash flows lines up with where the stock currently trades.
If you are weighing Corning's AI connectivity story against other options, a focused stock screen is a useful second reference point, especially one built around 88 AI infrastructure stocks.
Is Corning Still Cheap on Cash Flow?
The Discounted Cash Flow (DCF) model here takes Corning’s projected free cash flows and brings them back to today’s dollars. On the latest twelve month view, the business generated about $2.5b of free cash flow, and the model assumes that figure grows over time rather than shrinking, with 2030 cash flow projections also in the multibillion dollar range.
Those recovering cash flow estimates leave the estimated intrinsic worth meaningfully above the current share price of $158.71. Because the recent AI focused collaboration with Lumentum and Qualcomm has already pushed the stock higher, the remaining gap suggests the cash flow story supporting Corning is still stronger than what the market price reflects today. Find out what Corning could be worth using our Discounted Cash Flow (DCF) estimate.
The Corning Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Corning pick up where the DCF puzzle leaves off and explain what combinations of future growth, profitability and earnings power would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. Each one treats Corning's implied fair value as a thesis about the business that can be tracked over time, rather than as a one-day snapshot.
Community views on Corning are split between those who see AI fiber and solar agreements as upside and those who think policy risk and competition cap that story.
Bull case: 17% undervalued
"Corning's Springboard plan aims to add more than $4 billion in annualized sales by 2026, driven by strong demand in Optical Communications and Solar sectors..."
Discover why this Narrative puts Corning at 17% undervalued.
Bear case: 16% overvalued
"Corning's major growth initiatives are heavily exposed to ongoing trade policy shifts and rising geopolitical tensions, as highlighted by supply chain disruptions and tariff uncertainties..."
Explore why this Narrative puts Corning at 16% overvalued.
One more Corning signal worth checking before you move on
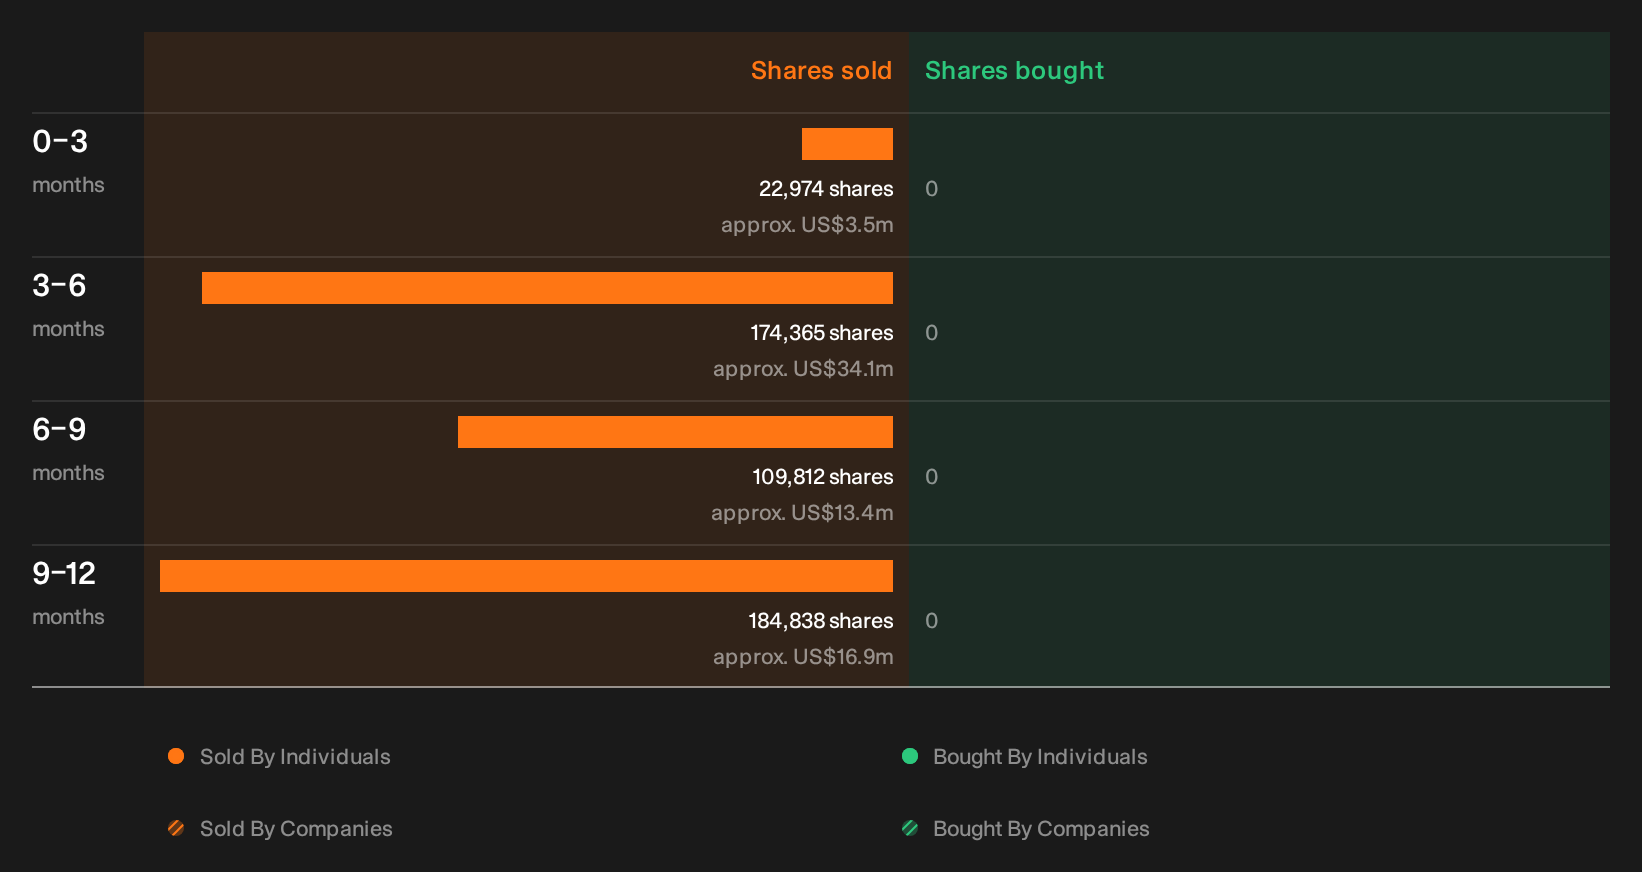
Before you finish forming a view on Corning, it is worth knowing that recent dealing by people inside the business has been flagged by our checks, with the who, how much and why still for you to review. See the recent insider selling flagged for Corning.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com