
Travelers Companies' Q3 2026 Earnings: What to Expect
New York-based The Travelers Companies, Inc. (TRV) is a leading provider of commercial and personal property, and property casualty insurance for auto, home and business. Valued at $75.7 billion by market cap, the company’s diverse business lines offer its global customers a wide range of coverage sold primarily through independent agents and brokers. The insurance giant is expected to announce its fiscal third-quarter earnings for 2026 before the market opens on Friday, Oct. 16.
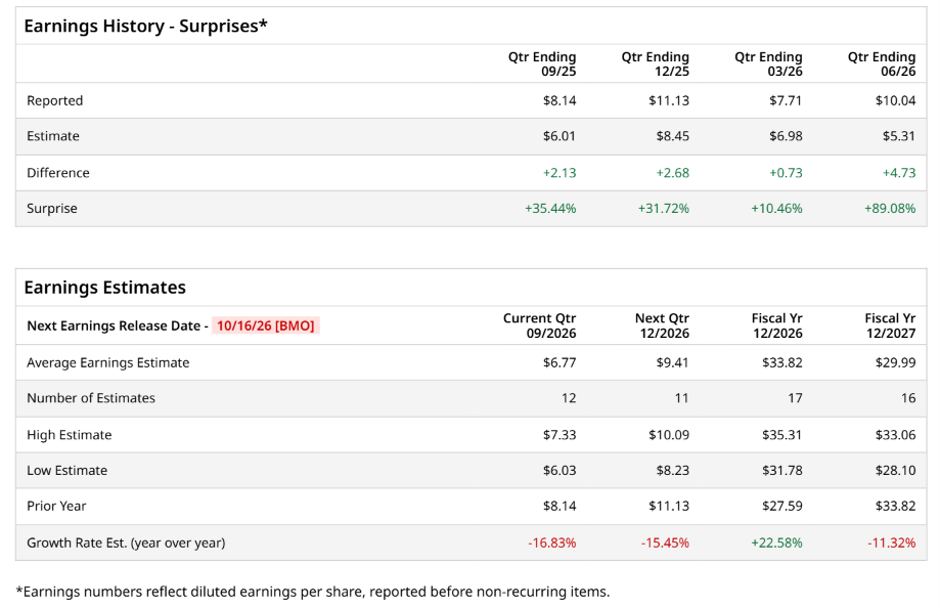
Ahead of the event, analysts expect Travelers Companies to report a profit of $6.77 per share on a diluted basis, down 16.8% from $8.14 per share in the year-ago quarter. The company has consistently surpassed Wall Street’s EPS estimates in its last four quarterly reports.
For the full year, analysts expect Travelers Companies to report EPS of $33.82, up 22.6% from $27.59 in fiscal 2025. However, its EPS is expected to fall 11.3% year over year to $29.99 in fiscal 2027.
TRV stock has outperformed the S&P 500 Index’s ($SPX) 15.2% gains over the past 52 weeks, with shares up 31.4% during this period. Similarly, it outperformed the State Street Financial Select Sector SPDR ETF’s (XLF) marginal losses over the same time frame.
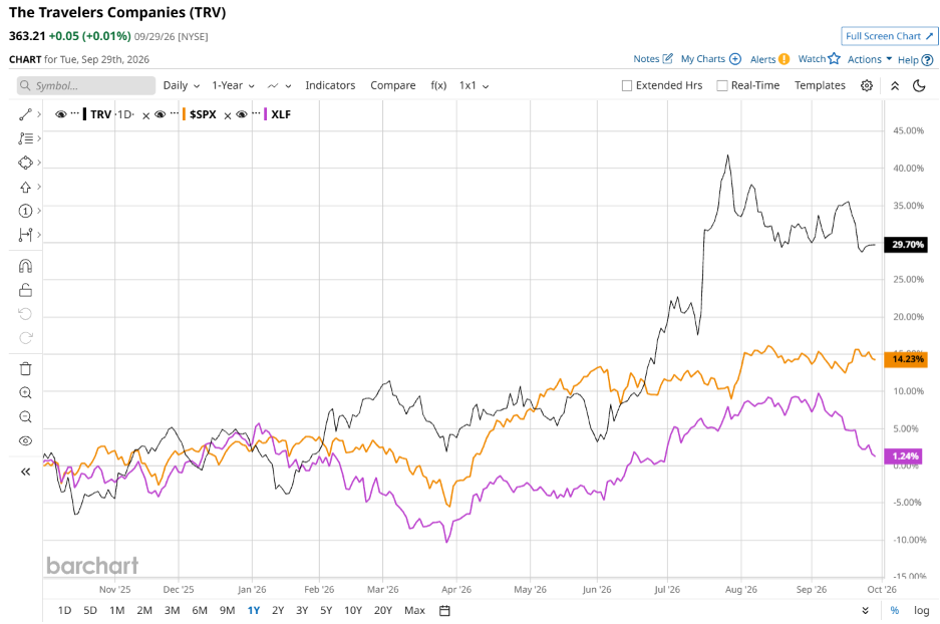
TRV has outperformed the market due to strong operational discipline, rising yields, and tech-driven productivity gains. A major catalyst is its $100 billion investment portfolio, which is heavily weighted in investment-grade fixed income, where reinvesting principal at higher market interest rates drove new money yields roughly 90 basis points above embedded portfolio yields. This reliable multi-year cash flow tailwind effectively subsidized core underwriting while permitting disciplined risk selection. Simultaneously, strategic technology deployments provided immediate operating leverage, with management crediting its AI-driven platform, Travis, for a 0.5-point improvement in the Business Insurance underlying loss ratio by streamlining automated underwriting and claims processing. Coupled with favorable reinsurance restructuring and solid net written premium growth, these combined factors expanded margins organically and generated consistent earnings beats, sustaining high investor confidence.
Analysts’ consensus opinion on TRV stock is cautious, with a “Hold” rating overall. Out of 30 analysts covering the stock, eight advise a “Strong Buy” rating, 17 give a “Hold,” two recommend a “Moderate Sell,” and three advocate a “Strong Sell.” TRV’s average analyst price target is $369.08, indicating a potential upside of 1.6% from the current levels.
On the date of publication, Neha Panjwani did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.