
Can PPL (PPL) Be A Bargain Following Federal Funding And Higher Earnings Estimates?
Why PPL Stock Is Back In Focus
PPL (PPL) has moved back onto investor radar after its utility subsidiary secured up to $71.5 million in federal funding and analysts raised earnings estimates ahead of the next report.
Short term, PPL’s share price has cooled, with a 30 day share price return down 4.7% and the year to date share price return down 7.2%. This has occurred even as recent federal funding news and earnings estimate revisions have improved sentiment. Longer term, total shareholder returns are mixed, with a 1 year total shareholder return down 9.5% but a 3 year total shareholder return up 56.6% and a 5 year total shareholder return up 37.1%, suggesting momentum has been stronger over multi year horizons than in recent months.
Compare PPL’s setup with a curated group of regulated utilities that also screen for resilience, earnings power, and balance sheet strength using our list of solid balance sheet and fundamentals (25 results).
PPL trades near US$32.58 while analyst targets cluster around US$40, and internal value work points much lower. Where does fair value really land in that gap, and how generous is today’s discount?
Most Popular Narrative: 19% Undervalued
On the prevailing narrative, PPL’s fair value sits near $40.33 compared with the last close at $32.58. This frames the current setup as a discount that hinges on big grid and data center plans actually playing through.
The accelerating growth in data center construction and new economic development (particularly in Pennsylvania and Kentucky) is driving unprecedented electricity demand, positioning PPL for outsized long-term rate base and revenue growth as it invests to serve these large new loads.
Major planned grid infrastructure upgrades and generation capacity expansions, totaling $20B through 2028 (with upside from potential data center-driven transmission and new generation projects), set the stage for nearly 10% average annual rate base growth directly supporting higher regulated revenues and future earnings.
See why 16 investors see PPL as 19% undervalued.
Result: Fair Value of $40.33 (UNDERVALUED)
Still, the bullish PPL story depends on regulators approving large capital plans and on data center demand materializing. Both of these factors could ultimately differ from what analysts expect.
Find out about the key risks to this PPL narrative.
Another View On PPL’s Worth
The SWS DCF model tells a very different story for PPL. On this approach, estimated future cash flows line up with a fair value near $19.88 per share, well below the current $32.58 price and far from the $40.33 narrative fair value. Which version of PPL do you trust more?
Look into how the SWS DCF model arrives at its fair value.
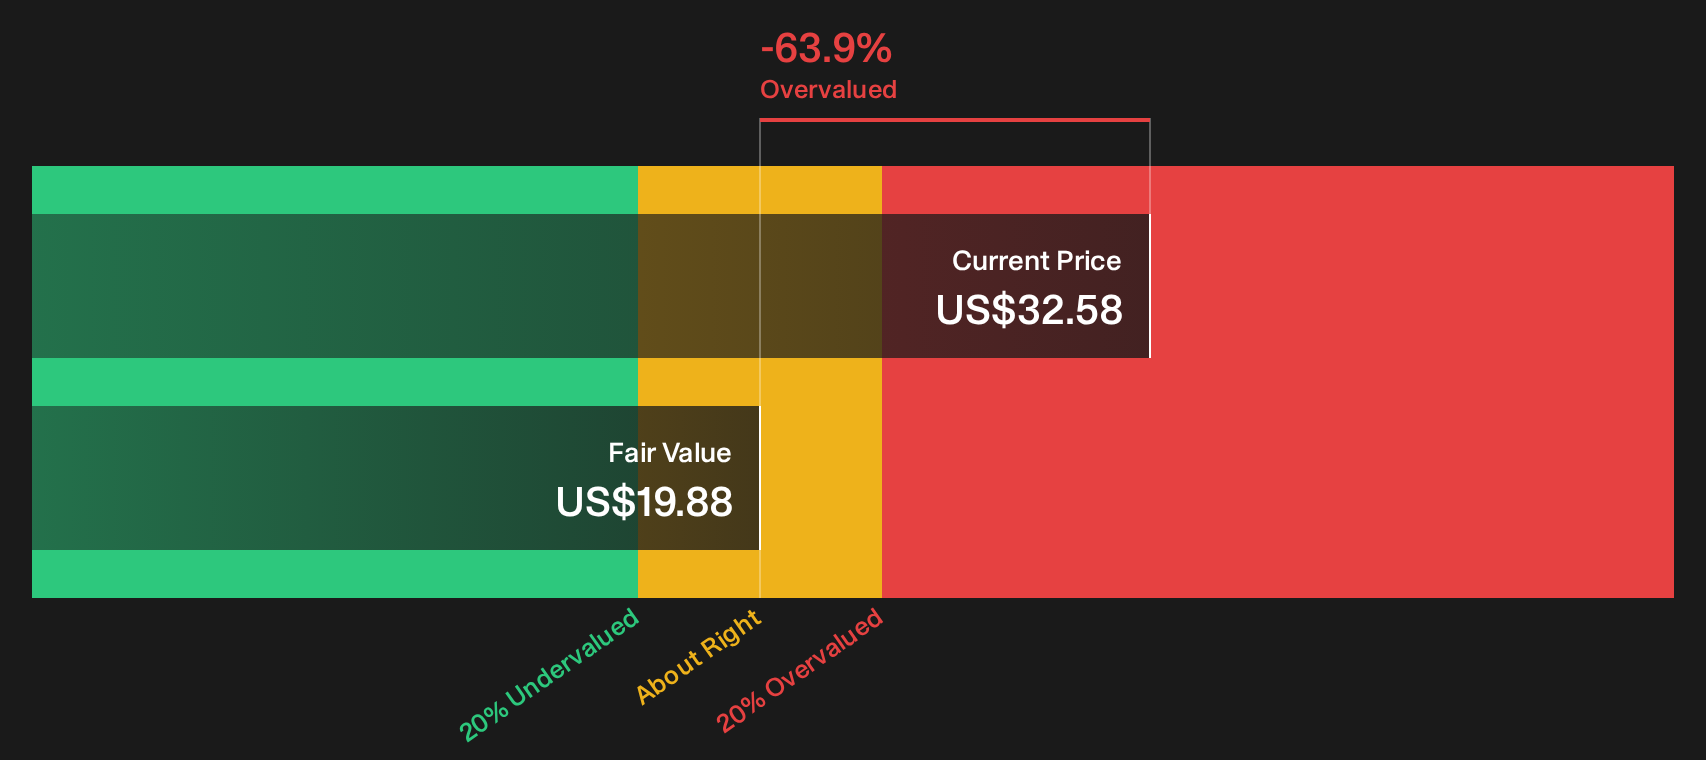
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PPL for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on PPL’s worth and risk profile can feel messy, so move fast, test the assumptions, and pressure check the full picture by reviewing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond PPL?
If you only stop at PPL, you risk missing other setups that could fit your goals even better. Put a few sharper candidates on your radar today.
- Target dependable compounders by scanning for companies with strong cash generation and appealing valuations using the 32 high quality undervalued stocks.
- Lock in potential income streams by reviewing financially robust businesses that show up in the 6 dividend fortresses.
- Prioritize peace of mind by filtering for steadier opportunities with the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com