
Did Battery Storage Launch Just Shift Northland Power's (TSX:NPI) Investment Narrative?
- Northland Power has brought the 80 MW / 160 MWh Jurassic Battery Energy Storage System in Alberta into commercial operation, with the province's largest battery facility completed ahead of schedule and under budget, and supported by a 15-year offtake agreement that covers all its capacity.
- The Jurassic BESS project adds long-term contracted storage revenue to Northland Power's portfolio while highlighting disciplined project delivery, including roughly 75,000 work hours completed with zero lost-time incidents.
- We will now look at how Northland Power's long-term contracted Jurassic BESS project could shape the broader investment narrative from here.
Scan beyond Northland Power and see how other grid and energy storage players stack up using our hand picked 39 power grid technology and infrastructure stocks
Northland Power Investment Narrative Recap
To own Northland Power, you need to be comfortable with a business that leans heavily on large, capital intensive offshore wind projects while trying to smooth that volatility with contracted assets like battery storage. The Jurassic BESS news supports that story, since it adds contracted storage cash flows without introducing new construction risk.
The near term swing factor still sits with execution on Hai Long, Baltic Power and existing offshore wind assets that are sensitive to wind resource and power prices. The biggest risk remains balance sheet pressure, given sizeable debt and capex, so incremental projects matter mainly if they support cash generation and do not stretch funding.
The Jurassic BESS milestone pairs naturally with the earlier progress at the Oneida battery storage project. Taken together, these facilities point to Northland Power building a second leg of operations in grid scale storage, alongside offshore wind and gas. That matters for cash flow mix and exposure to weather driven variability.
For catalysts, investors can watch how consistently these storage assets perform and whether similar long term offtake structures appear on future projects. Reliable contracted revenue could help offset risks from unpaid curtailments, negative power prices in Europe and high leverage, but only if execution on large offshore developments stays on track and operating cash flow strengthens.
Northland Power's current analyst storyline points to CA$2.8b in revenue and CA$433.7m in earnings by 2029, based on 2.9% yearly revenue growth and an earnings swing of about CA$582m from a loss of CA$148.2m today.
Uncover why Northland Power's fair value indicates an 18% potential upside to its current price that could narrow quickly.
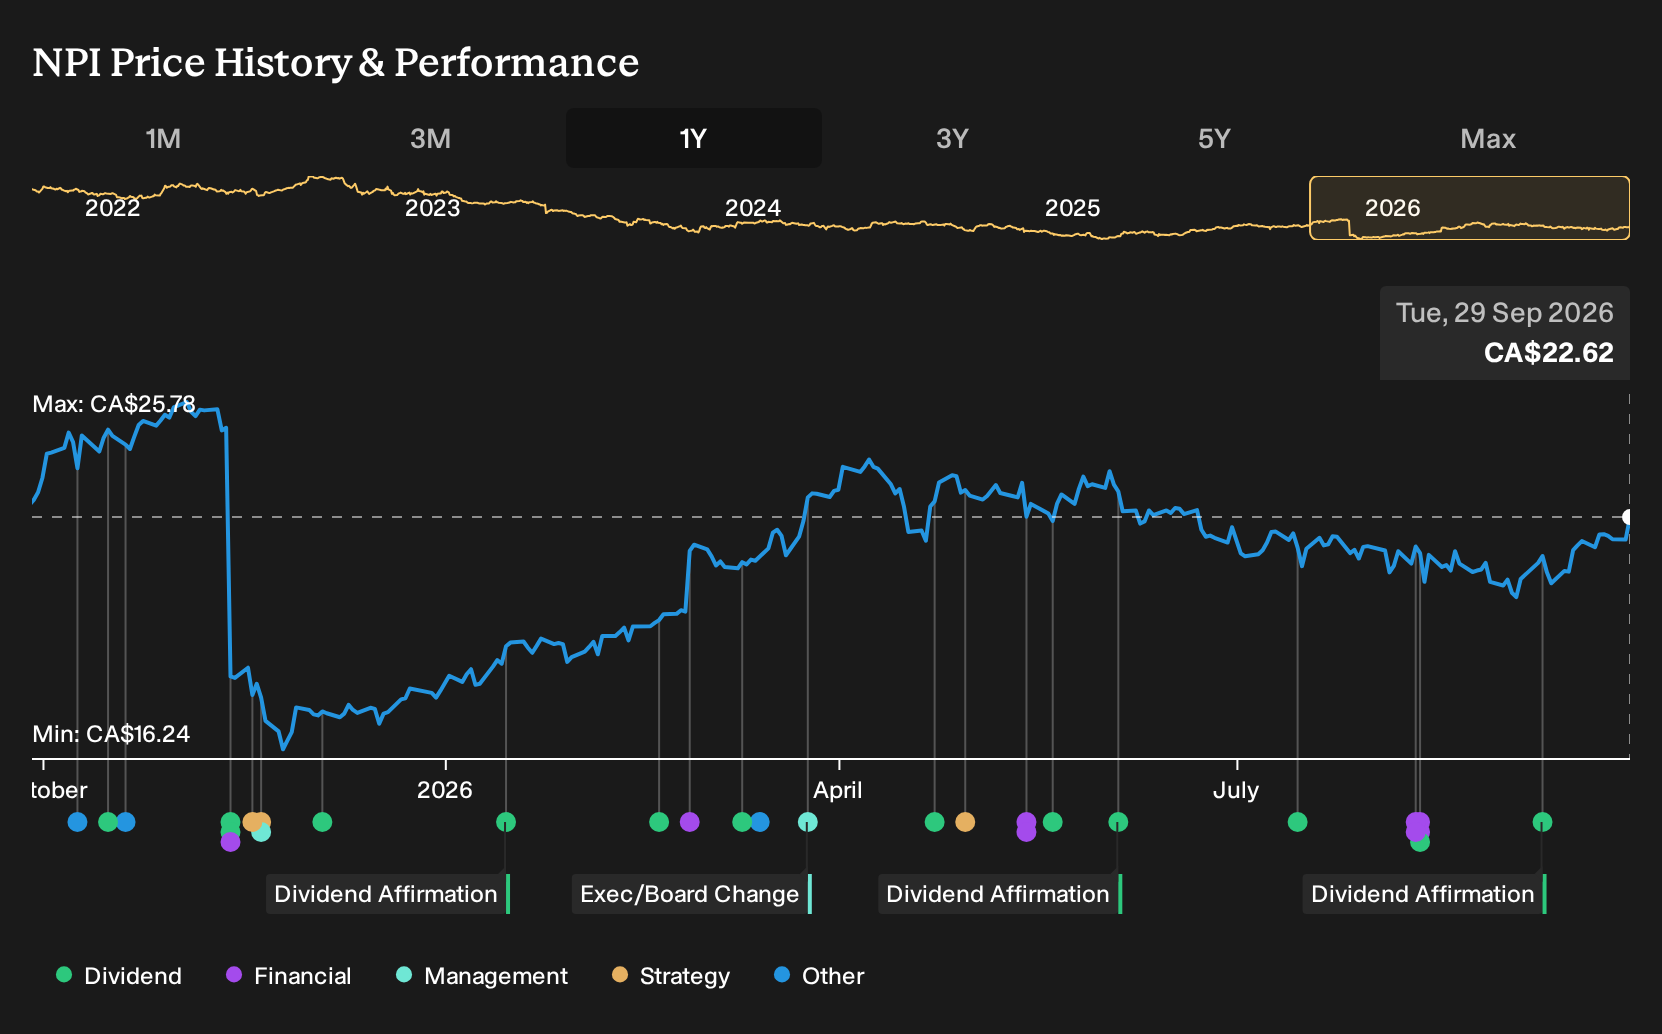
Exploring Other Perspectives
One alternate view on Northland Power puts far more weight on offshore wind execution risk. The most cautious analysts were only pencilling in flat revenue at about CA$2.5b and earnings of roughly CA$346.4m by 2029. That is a much cooler story than consensus. Use this Jurassic BESS update to test which narrative you find more convincing.
Explore 2 other Northland Power fair value estimates, including one that suggests it could be worth just CA$26.62.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Northland Power research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Northland Power. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northland Power's overall financial health at a glance.
Looking For More Investment Ideas Beyond Northland Power?
If the Jurassic BESS story has you rethinking how Northland Power fits into your watchlist, it can help to widen the lens and compare it with other companies that match your risk tolerance and income goals using the Simply Wall St Screener.
- For investors hunting for resilient balance sheets and solid fundamentals, start with a curated list of solid balance sheet and fundamentals (7 results) to help you focus on financially robust businesses.
- If your priority is finding lower risk profiles, scan through a tailored 7 resilient stocks with low risk scores to see which stocks better align with your comfort level.
- For those looking to uncover fresh opportunities before they are widely followed, work through a focused 9 high quality undiscovered gems that highlights under-the-radar companies with strong foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com