
Madison Square Garden Entertainment (MSGE) Following Leadership Shake Up Looks Undervalued
Madison Square Garden Entertainment (MSGE) just reshaped its leadership, promoting Josephine Vaccarello to President with control over entertainment and sports bookings, productions, and special events across its well known venue portfolio.
Recent trading has been upbeat for Madison Square Garden Entertainment, with a 30-day share price return of 4.28% and a year to date share price gain of 50.26%. The 1-year total shareholder return of 80.48% points to strong longer term momentum building behind the stock.
Scan other live entertainment and media stocks showing strong business momentum with our hand picked 17 high quality undiscovered gems for a broader view beyond Madison Square Garden Entertainment.
Madison Square Garden Entertainment now has leadership aligned with its headline venues and a share price that has already moved hard. The next question is whether that mix of performance and promise is already fully reflected in today’s valuation.
Most Popular Narrative: 11% Undervalued
On the most followed view, Madison Square Garden Entertainment carries a fair value of $91.63 against a last close of $81.65, which frames the current price as a discount that leans heavily on the strength and monetization of its event calendar.
• Sustained strong demand for live events and premium in-person experiences is translating into record ticket sales and advance bookings for fiscal '26, with concerts and special events at both the Garden and theaters pacing ahead of prior years. This growth in volume and pricing is likely to drive meaningful increases in revenue and operating income.
• Continued consumer enthusiasm for experiential entertainment is evident in robust sales and expanded show counts for marquee productions like the Christmas Spectacular, along with higher per-capita spend on food, beverage, and merchandise, supporting both top-line growth and net margin expansion.
See why 1 investors see Madison Square Garden Entertainment as 11% undervalued.
Result: Fair Value of $91.63 (UNDERVALUED)
Still, the Madison Square Garden Entertainment story can break if concert volumes soften after key residencies or if premium in venue spending weakens with tighter consumer budgets.
Find out about the key risks to this Madison Square Garden Entertainment narrative.
Another View on Madison Square Garden Entertainment’s Valuation
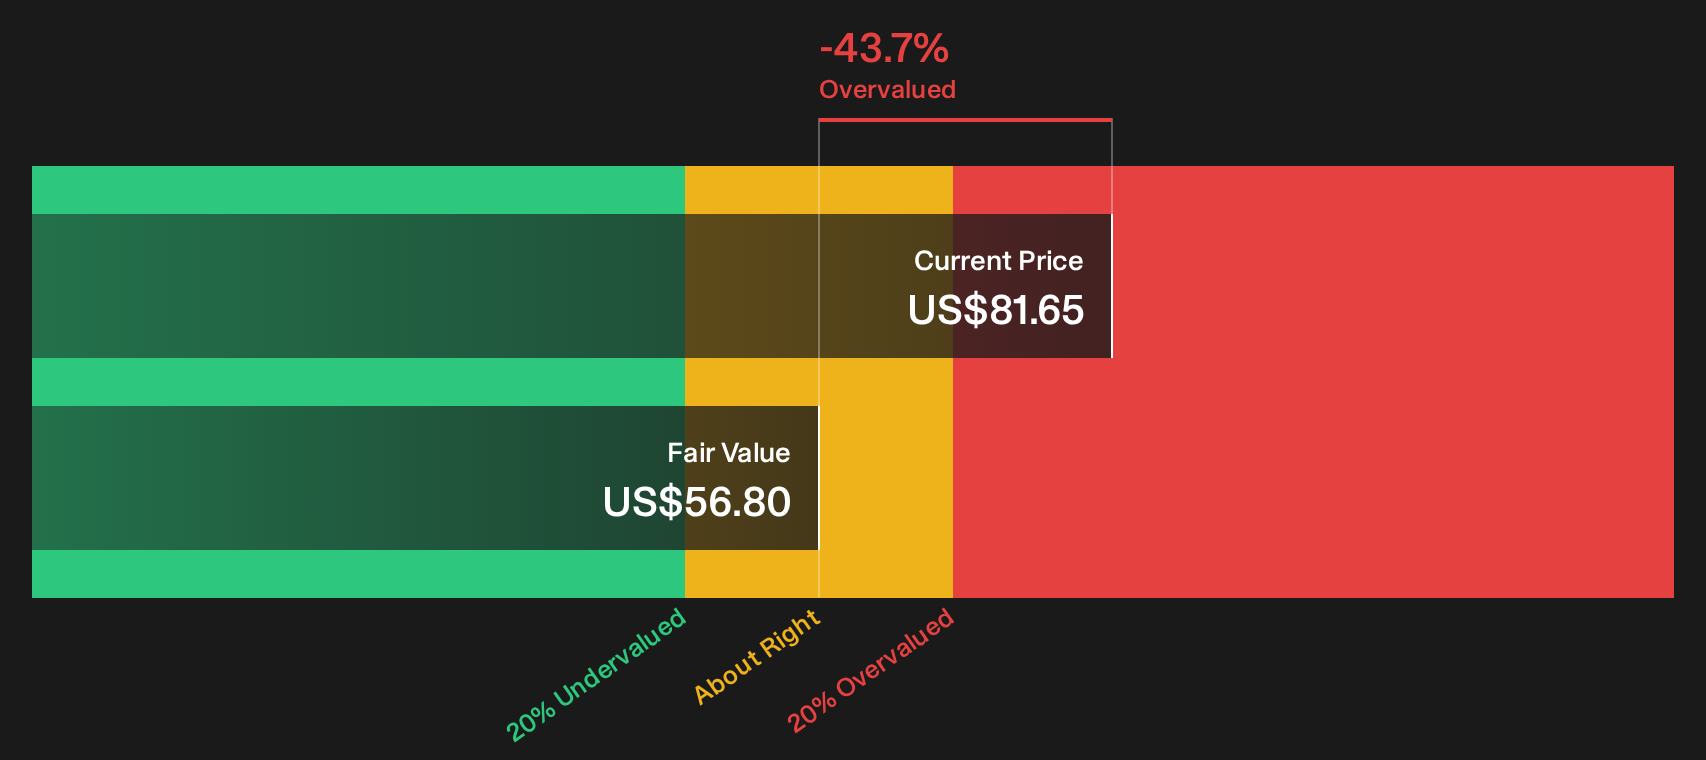
The SWS DCF model paints a very different picture for Madison Square Garden Entertainment. On this framework, MSGE shares at $81.65 sit well above an estimated future cash flow value of $56.80, which screens as overvalued rather than cheap. That split between narrative fair value and cash flow math is where investors need to decide which story they trust more.
For a clearer look at how this cash flow approach is built, and where the key assumptions sit, Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the mix of optimism and caution around Madison Square Garden Entertainment feels finely balanced, treat that as your prompt to check the data yourself and move quickly to your own judgment. To see both sides laid out clearly, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Madison Square Garden Entertainment?
Do not stop your research at Madison Square Garden Entertainment. Use curated stock lists to pressure test your thinking, compare opportunities, and spot potential ideas you might otherwise miss.
- Target stronger value candidates by checking companies on our 32 high quality undervalued stocks that combine quality fundamentals with discounted valuations.
- Prioritize resilience by reviewing the 32 resilient stocks with low risk scores and focus on businesses screened for lower risk profiles.
- Hunt for underfollowed opportunities with the 17 high quality undiscovered gems and see which quieter tickers share appealing fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com