
3 U.S. Small Cap Stocks Tied To Domestic Infrastructure Spending
Today’s mix of firmer U.S. equity futures, closely watched inflation and jobs data, and steady but elevated oil prices is putting a fresh spotlight on small-cap growth stocks that earn most of their money at home. When bigger headlines pull attention to the mega caps, chances in U.S. focused growth stories can slip by. This article unpacks how that backdrop connects to three specific small caps from the U.S. Small-Cap Growth Stocks With Domestic Revenue Focus screener that appear particularly exposed to the current news flow, and it explains why their reaction to these catalysts may matter for your portfolio decisions.
The stocks covered below are only a small sample of what fits this U.S. focused small-cap growth theme. The full screen surfaced 22 more domestically oriented companies with equally compelling narratives that are not broken out in the list that follows. To see the complete set and start identifying which stories best fit your own risk and return preferences, head straight into the U.S. Small-Cap Growth Stocks With Domestic Revenue Focus screener.
Centuri Holdings (CTRI)
Overview: Centuri Holdings provides gas and electric utility infrastructure services across North America, with a heavy emphasis on U.S. modernization and expansion work.
Operations: Centuri generates about US$1.6b from U.S. Gas, US$879 million from Union Electric, US$654 million from Non Union Electric and US$293 million from Canadian Operations, with roughly US$3.1b of revenue in the United States and US$294 million in Canada.
Market Cap: US$2.0b
Centuri Holdings plugs directly into the screener’s U.S. focused growth angle because its contractors are tied to domestic grid upgrades, gas line replacement and onshoring related power projects that move largely with American capital spending cycles rather than global trade swings.
"Heavy exposure to large data center and industrial power projects, including over $1.3 billion of identified data center opportunities, may face delays or cancellations if hyperscale and AI buildouts moderate."
How that single pressure interacts with already tight construction margins and leverage will go a long way to shaping future earnings power.
That tension between future projects and current balance sheet pressure is exactly what the full narrative for Centuri Holdings unpacks, including how Centuri Holdings could respond if data center demand stalls or accelerates.

Orion Group Holdings (ORN)
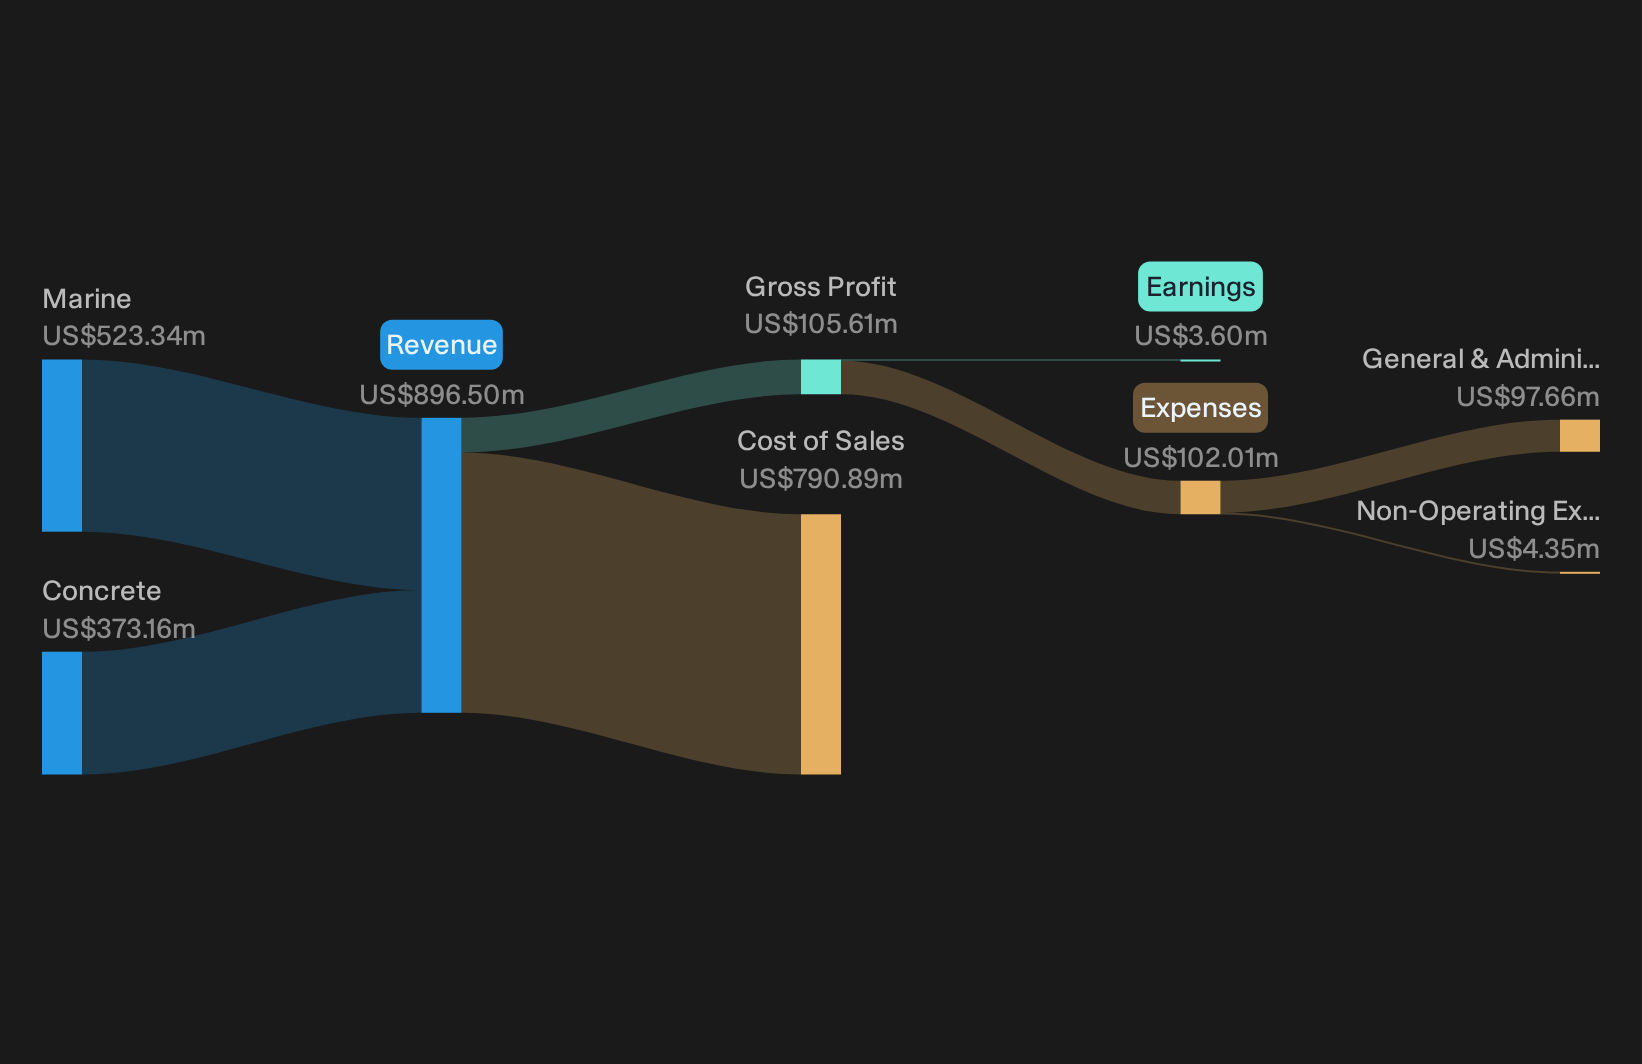
Overview: Orion Group Holdings is a Houston based specialty constructor of marine and concrete infrastructure across North America, closely tied to U.S. construction and port modernization cycles.
Operations: Orion Group Holdings generates about US$523 million from Marine and US$373 million from Concrete, with roughly US$870 million of revenue from the United States and US$27 million from the Caribbean Basin.
Market Cap: US$338 million
Orion Group Holdings fits the U.S. Small-Cap Growth Stocks With Domestic Revenue Focus theme almost perfectly, since its work on ports, bridges, and concrete projects is heavily tied to U.S. public spending and private building plans rather than far flung international demand.
"Orion's strong backlog growth and $18 billion project pipeline, supported by expanded federal and state investment in infrastructure modernization (particularly marine and port projects), are expected by some observers to support sustained revenue growth and increased visibility over multiple years."
The real swing factor is how one unresolved cost and execution pressure shapes future margins just as that project pipeline moves into full build mode.
With that cost overhang in mind, read the full narrative for Orion Group Holdings to see how Orion Group Holdings could turn backlog momentum into accelerating earnings power or stalled profit potential.
Concrete Pumping Holdings (BBCP)
Overview: Concrete Pumping Holdings provides concrete pumping and construction waste management services across U.S. infrastructure, commercial and residential projects, with a smaller U.K. arm.
Operations: Concrete Pumping Holdings generates about US$280 million from U.S. Concrete Pumping, US$82 million from U.S. Concrete Waste Management Services and US$61 million from U.K. Operations.
Market Cap: US$499 million
Concrete Pumping Holdings fits neatly into this U.S. focused growth screen because its concrete pumping fleet and Eco Pan waste business are closely linked to domestic building cycles and infrastructure work rather than global trade swings.
"The company anticipates a robust pipeline of infrastructure projects as previously allocated government funding in both the U.S. and U.K. is converted into project starts, particularly within the Infrastructure Investment and Jobs Act and ongoing U.K. efforts such as HS2."
What happens to Concrete Pumping Holdings' earnings power hinges on whether one underappreciated pressure eases or intensifies as that project wave arrives.
If that pressure point matters to you, the full narrative for Concrete Pumping Holdings shows how Concrete Pumping Holdings could turn project momentum into accelerating cash generation and rerating potential.

Seeking Fresh Alternatives Before Momentum Flies
Fresh breakouts can move fast, and early momentum often fades once the crowd catches on. Scan these under-the-radar ideas while it matters and consider your options before they become widely followed.
- Look for resilient cash generators before the next risk-off wobble and run a quick filter through the list of solid balance sheet and fundamentals (25 results) to see which businesses still look financially robust.
- Explore the potential AI infrastructure buildout while others may be reacting later by scanning the 88 AI infrastructure stocks for construction, power and hardware players tied to that spending wave.
- Consider long-term wealth compounding with a curated roster of 6 dividend fortresses that aim to combine high yields with balance sheets structured to handle rougher markets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com