
How Ananta Launch Hopes At NetEase (SEHK:9999) Has Changed Its Investment Story
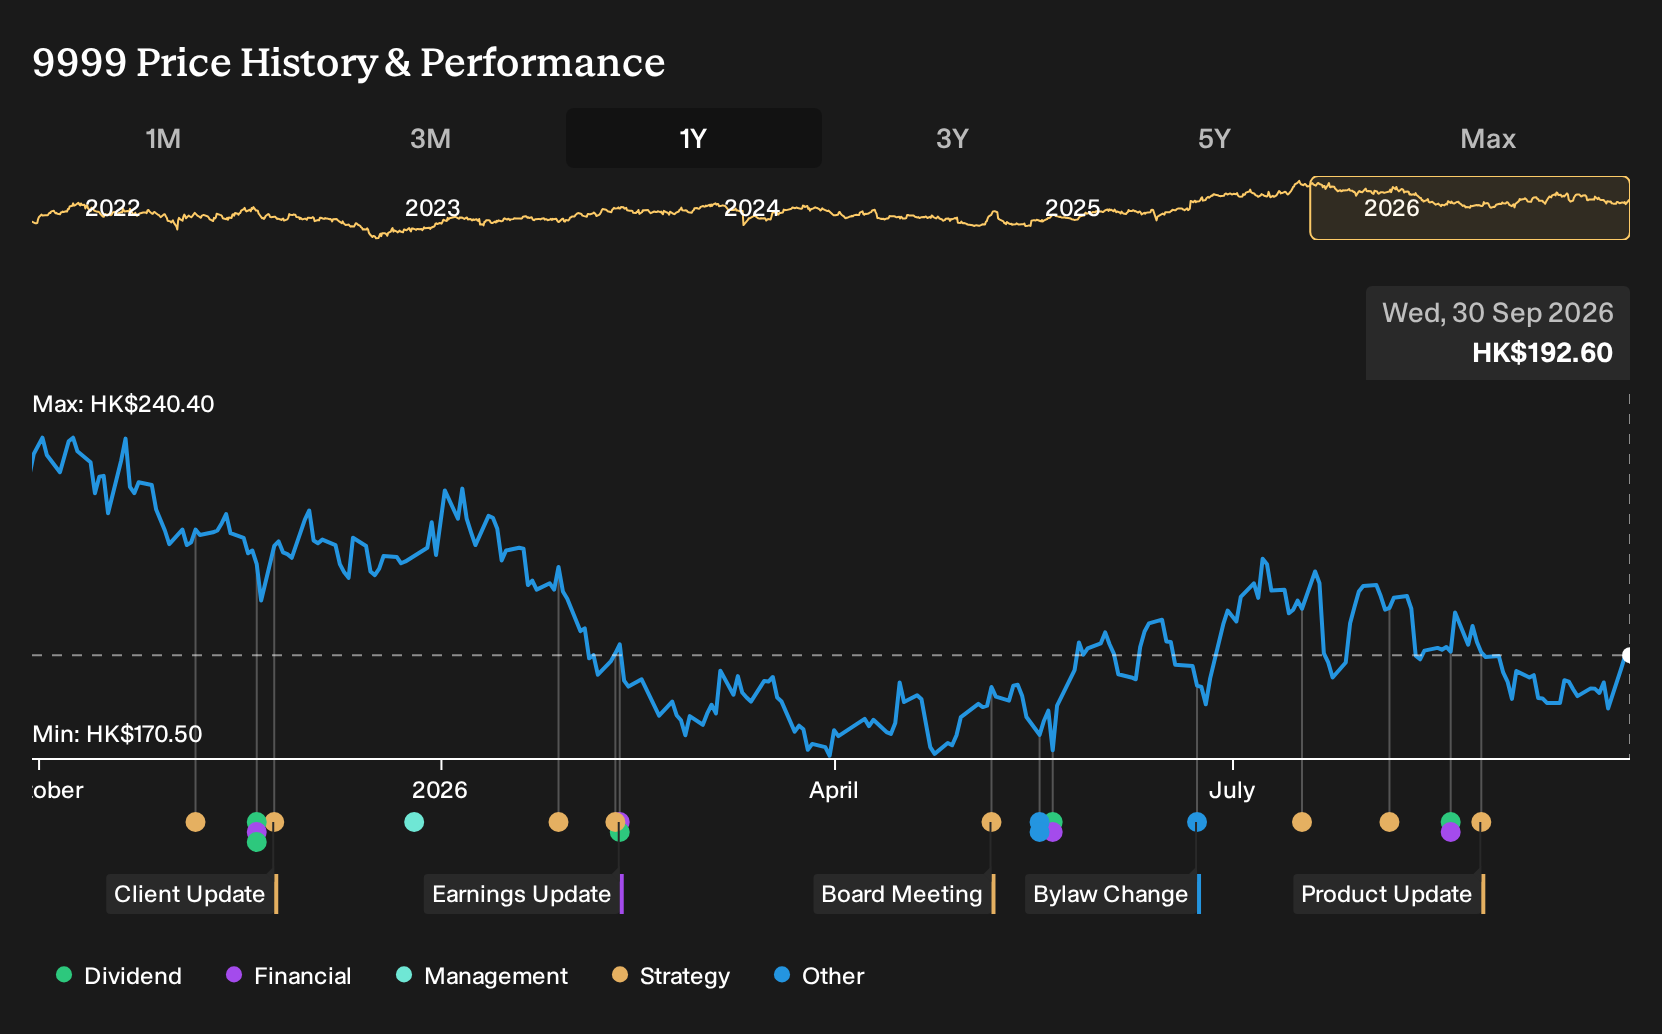
- NetEase recently led Hong Kong blue chip gains after a 1.71% rise on a day when broader tech strength lifted the Hang Seng Index.
- Investor focus is centering on the upcoming global launch of the game Ananta, with options pricing reflecting expectations of a large share move.
- We now assess how NetEase's broader investment narrative could be influenced by expectations around the global rollout of Ananta.
Compare NetEase's momentum with other potential tech movers by scanning our hand picked 621 high quality undiscovered gems that could be preparing for their own catalyst driven breakouts.
NetEase Investment Narrative Recap
To own NetEase, you need to be comfortable with a games led engine that is still heavily tied to China while trying to build a real global footprint. The big near term swing factor is execution on its international pipeline, including Ananta, and whether new titles deepen engagement enough to support earnings that analysts expect to grow about 12.3% a year.
The key risk remains concentration. Almost all revenue is still generated in China, even when user bases look balanced across regions, so any regulatory shock or weaker player spending at home can bite. Higher R&D and content spend add another layer of pressure if new franchises do not scale fast enough.
The most relevant piece of fresh information for this story is the focus on Ananta as a potential 2027 growth driver. Management is already leaning on self developed games, which tend to carry higher gross margins. A successful global rollout would reinforce that shift and support the existing games and related value added services segment, which produced about CN¥96.0b of revenue.
Options activity around the Dec 18, 2026 $70 call signals that traders expect a large move in NetEase shares into the Ananta window, even if direction is unclear. For you, the operational question is simple: does this title meaningfully lift overseas revenue from today’s very low base and offset risks from rising competition, tighter rules, and softer net profit margins compared with last year?
What The NetEase Ananta Story Implies For The Numbers
NetEase's narrative projects CN¥144.4b revenue and CN¥47.4b earnings by 2029. This assumes 8.1% yearly revenue growth and an earnings increase of about CN¥13.3b from CN¥34.1b today.
Uncover how NetEase's fair value indicates a 30% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One optimistic twist on NetEase comes from bullish analysts who see Ananta as a springboard for much faster overseas traction than the market assumes. Before this latest rally, that group was already modeling revenue of about CN¥151.7b and earnings near CN¥56.1b by 2029. You can treat today’s move as a prompt to revisit those more aggressive views and compare them with your own expectations.
Explore another NetEase fair value estimate, including one that suggests potential upside of up to 74% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NetEase research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for NetEase. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NetEase's overall financial health at a glance.
Looking For More Investment Ideas Beyond NetEase?
Once you have a view on NetEase, it can help to cross check that thesis against a wider watchlist so you are not relying on a single story for future returns.
- If you want potential mispricing with quality in focus, scan our 195 high quality undervalued stocks that match strong fundamentals with a discounted market tag.
- For investors who care most about resilience, filter for stability first with a 226 resilient stocks with low risk scores that aims to keep downside front of mind.
- Income focused readers can concentrate on durable payouts by reviewing a carefully curated 160 dividend fortresses that prioritises higher yields with a focus on consistency.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com