
BlackBerry (TSX:BB) Stock Looks Close To Fair Value Today
BlackBerry has delivered a sharp share price run over the past year, so the obvious question for you now is whether that move is matched by the cash flows the business can reasonably produce. After a long period where the story was mostly about transition, the spotlight has shifted onto what its current and future cash generation might really be worth.
- The stock is up 136.4% year to date, which puts much more weight on whether today’s valuation can be explained by the cash the company is expected to earn over time.
- Recent QNX software momentum, including the Alloy Kore partnership for commercial vehicles, may support expectations for stronger and more durable cash flows tied to automotive and embedded software royalties.
- Prefer to judge BlackBerry on earnings? See why BlackBerry's 63.5x P/E tells a different valuation story.
The issue now is whether the current BlackBerry share price around $12.34 is adequately backed by the intrinsic value implied by its cash flows.
If you want to test the same cash flow question that BlackBerry now faces across a wider set of companies, start with 6 high quality undervalued stocks.
Is BlackBerry Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here takes BlackBerry’s future free cash flows and discounts them back to today. On this view, the story is about whether the recent shift in the business can support the current CA$12.34 share price. Latest twelve month free cash flow is about $85.8 million, and the projections assume it grows over time rather than shrinking, with analyst and modelled figures stepping up into the next decade.
That path is not explosive in the model, but it does lean on healthier and more sustained cash generation from software, especially QNX royalties. The recent Alloy Kore win, with more than $100 million of expected future royalties and a QNX backlog near $1b, helps explain why the DCF outcome sits broadly in line with where the stock trades today. The discounting work suggests the current CA$12.34 price is roughly in step with what these projected cash flows could justify over the long run. Find out what BlackBerry could be worth using our Discounted Cash Flow (DCF) estimate.
The BlackBerry Narrative: What Would Justify Today's Price?
BlackBerry Narratives on Simply Wall St pick up where the cash flow puzzle leaves off. They explain which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than it is today. These narratives sit on the Community page so you can track how those storylines evolve as new information on BlackBerry’s growth, profitability and risks comes through.
Community views on BlackBerry now split between one group that sees much more upside in the story and another that thinks recent gains already reflect the key drivers.
Bull case: 24% undervalued
"QNX charges automakers a royalty every time a car rolls off a production line. Once a design win is secured, that royalty flows for the entire model lifecycle…"
Discover why this Narrative puts BlackBerry at 24% undervalued.
Bear case: roughly fairly valued
"The analysts have a consensus price target of CA$11.96 for BlackBerry based on their expectations of its future earnings growth, profit margins and other risk factors…"
Explore why this Narrative puts BlackBerry at roughly fairly valued.
One more BlackBerry check that sits beyond the valuation math
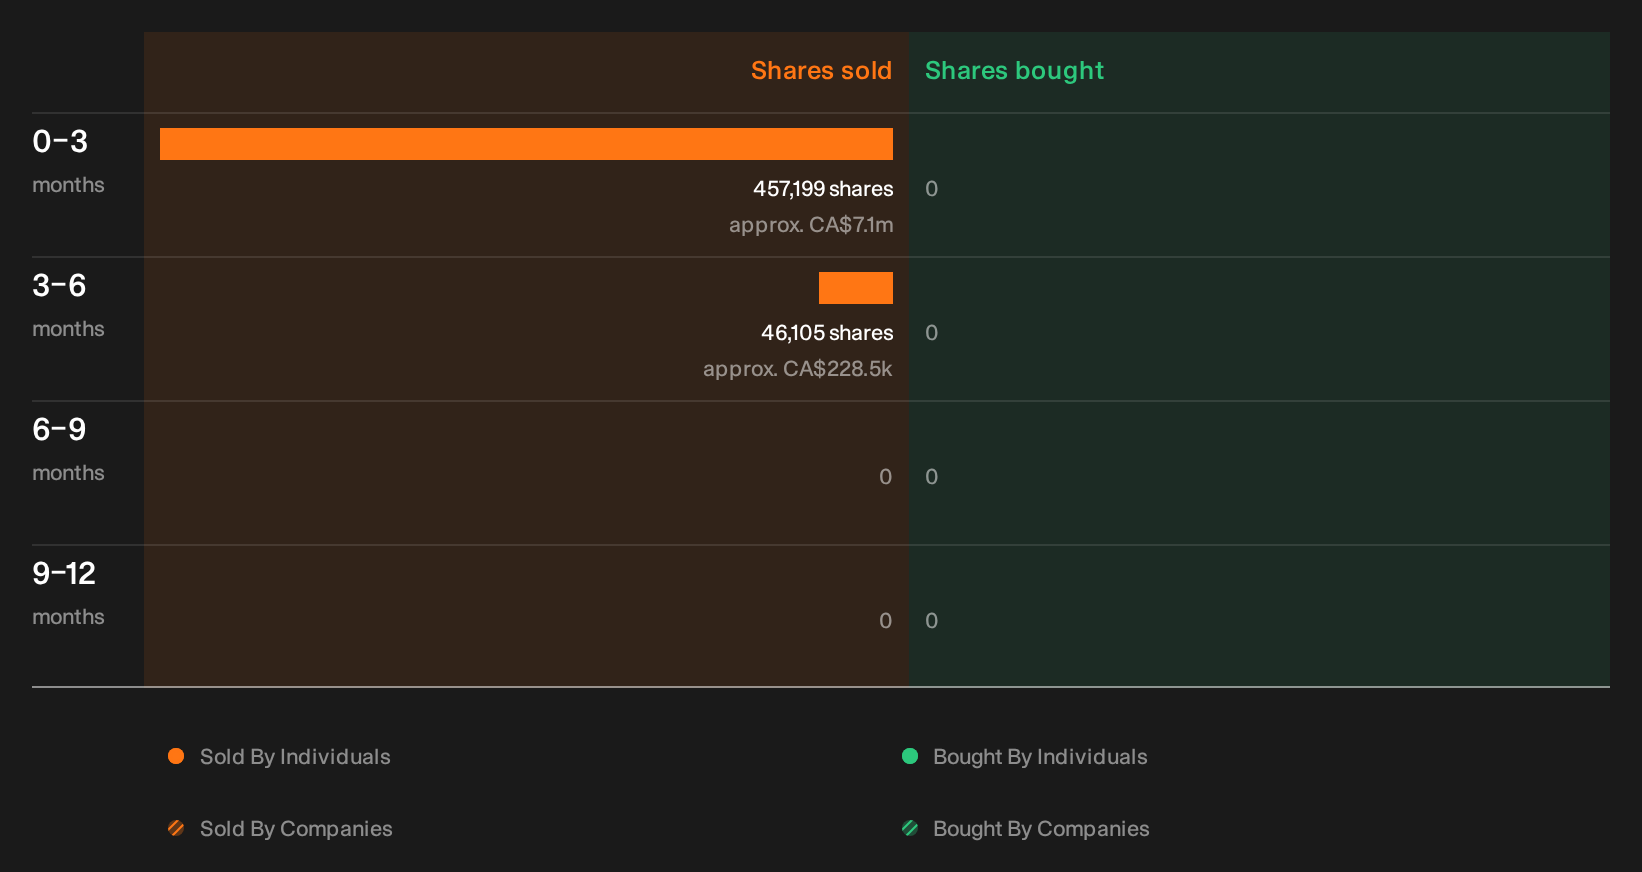
Price, cash flows and community views tell only part of the story. Our checks have also picked up recent insider share activity, and the identities, sizes and possible read-throughs are still for you to unpack. See the recent insider selling flagged for BlackBerry.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com