
11% Undervalued? Old Second Bancorp (OSBC) As Integration Progress Shapes Its Valuation
Old Second Bancorp (OSBC) has been drawing fresh attention after recent trading left the shares near US$24.65. Investors are weighing this regional bank’s valuation against its earnings profile and multi year total return record.
Recent trading has been choppy around that US$24.65 share price, with a small one day pullback offset by a positive 7 day move and a 90 day share price return of 6.11%. The year to date share price gain of 26.54% sits alongside a 1 year total shareholder return of 43.93% and a 5 year total shareholder return of 99.41%, which hints that investors have been steadily reassessing Old Second Bancorp’s prospects and risk profile over time.
Spot opportunities with a similar risk and return profile to Old Second Bancorp by scanning our curated list of 32 resilient stocks with low risk scores.Old Second Bancorp now trades at US$24.65 while analyst targets and intrinsic estimates sit higher, leaving a wide gap. Does that discount reflect real risk or a mispriced regional bank story?
Most Popular Narrative: 10% Undervalued
Old Second Bancorp’s most followed valuation narrative pegs fair value at $27.50, which sits above the recent $24.65 close and frames the current price as a discount that hinges on credit stability and integration progress.
The successful integration of acquisitions and technology upgrades is driving revenue growth, operating efficiency, and higher margins across core banking services. Expanding wealth management and potential further acquisitions diversify income, increase scale, and support long-term stable earnings growth.
See why 1 investors see Old Second Bancorp as 10% undervalued.
Result: Fair Value of $27.50 (UNDERVALUED)
Still, Old Second Bancorp’s heavy focus on Illinois and exposure to commercial real estate mean that a regional downturn or credit slip could quickly challenge that undervalued story.
Find out about the key risks to this Old Second Bancorp narrative.
Another View: Old Second Bancorp On Earnings Multiples
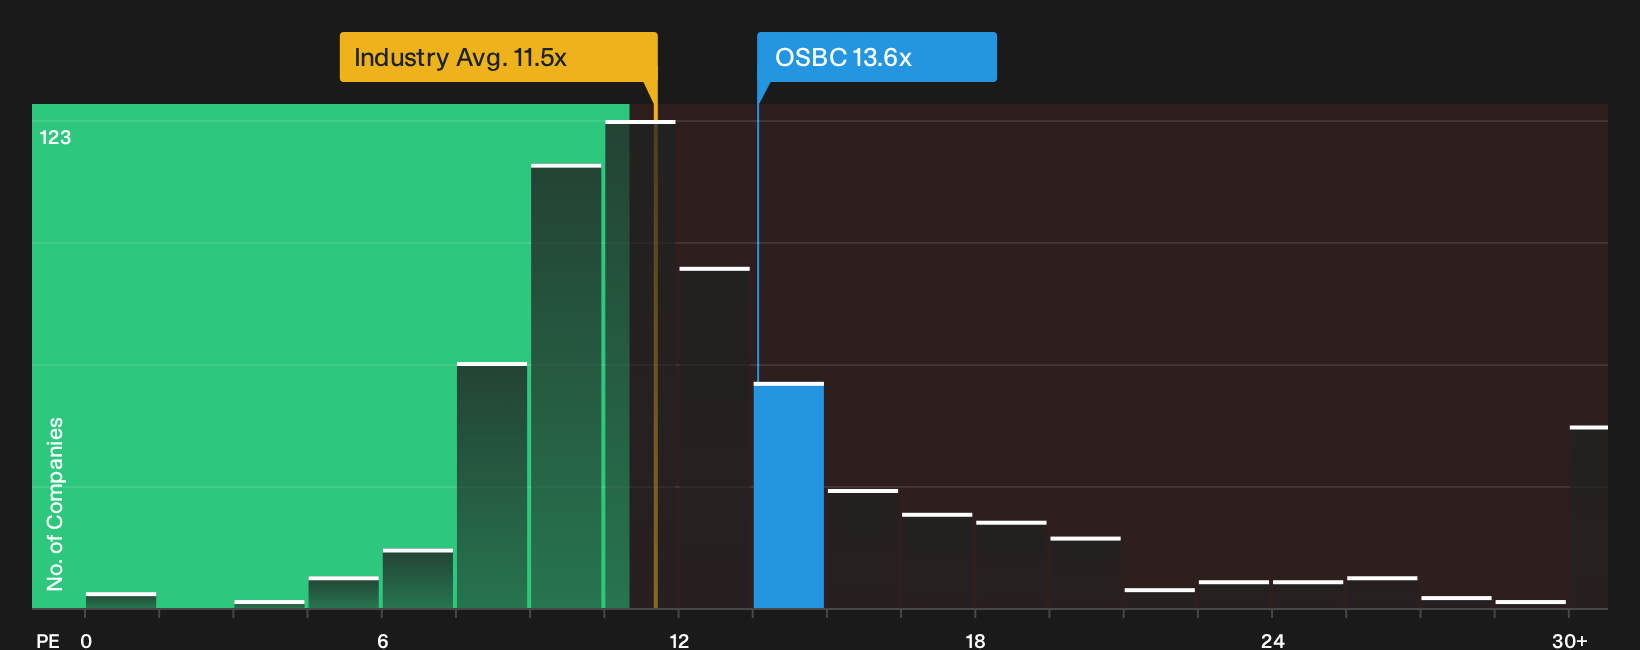
The SWS DCF model points to Old Second Bancorp trading at a sharp discount to an estimated future cash flow value of $49.85. At the same time, the market is pricing the stock at a P/E of 13.6x, compared with a US Banks average of 11.6x and a fair ratio of 12.7x. Does that mix of discounted cash flows and a richer earnings multiple signal opportunity or just more risk being priced in?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Old Second Bancorp so far, or a clear opportunity hiding in plain sight. Act now by weighing both sides of the story through 3 key rewards and 1 important warning sign
Looking for more ideas beyond Old Second Bancorp?
If Old Second Bancorp has caught your attention, do not stop there. Use the Simply Wall Street Screener to quickly spot fresh, high conviction opportunities across the market.
- Target quality at a discount by scanning a curated mix of resilient companies through the 32 high quality undervalued stocks.
- Lock in income potential by reviewing a focused pool of payout heavy candidates via the 6 dividend fortresses.
- Prioritise resilience by filtering for companies with robust finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com