
How Investors May Respond To Aya Gold & Silver Stock High Grade Drill Results
- Aya Gold & Silver reported high-grade drill results at the Boumadine Project and Zgounder Silver Mine in Morocco, covering hundreds of holes across multiple zones and confirming continuous mineralized trends.
- What stands out is the scale of the drill commitment, with a planned 360,000 m infill program at Boumadine and rigorous assay and quality control protocols at Zgounder that indicate how seriously management is treating resource definition and project de-risking.
- We will now look at how Aya Gold & Silver's investment narrative could shift given the extensive high-grade drilling success at Boumadine.
Scan beyond Aya Gold & Silver and line up other high-commitment drill stories by reviewing our curated list of 36 elite gold producer stocks that are now moving on aggressive exploration programs.
Aya Gold & Silver Investment Narrative Recap
To own Aya Gold & Silver, you need to be comfortable with a Morocco focused precious metals producer that is leaning hard into drilling to firm up mine plans and mine life. The big near term swing factor is Boumadine moving efficiently from PEA to Feasibility Study, with sufficient infill data to underpin a robust mine design.
The biggest risk stays the same. Aya is spending heavily on drilling and project work in a single jurisdiction, and still needs to convert high grade hits into mineable, economically tested ounces. The latest Boumadine and Zgounder results improve geological confidence but do not remove execution, permitting and cost inflation risks.
The Boumadine infill program is the clearest link between this news and Aya Gold & Silver's next catalyst. Management plans roughly 360,000 m of drilling over about 15 months, aiming to extend the Main Trend, Tizi and Imariren while tightening spacing ahead of Feasibility work. That represents a serious operational commitment.
For investors, the practical question is whether Aya can turn this dense grid of high grade intercepts into a mine plan that supports stable production and manageable capital needs. Progress on Asirem and greenfield targets adds optionality, although it also layers on more spend and execution complexity at a time when analysts already expect earnings to decline.
Aya Gold & Silver's current earnings of $112.7 million are forecast by analysts to shift to $81.5 million by 2029, which implies a decline of $31.2 million in profit, even though revenues are projected to sit at $346.6 million in that same year and are expected to remain fairly flat over the next 3 years.
Uncover why Aya Gold & Silver's fair value indicates a 7% potential upside to its current price, which could close faster than many investors expect.
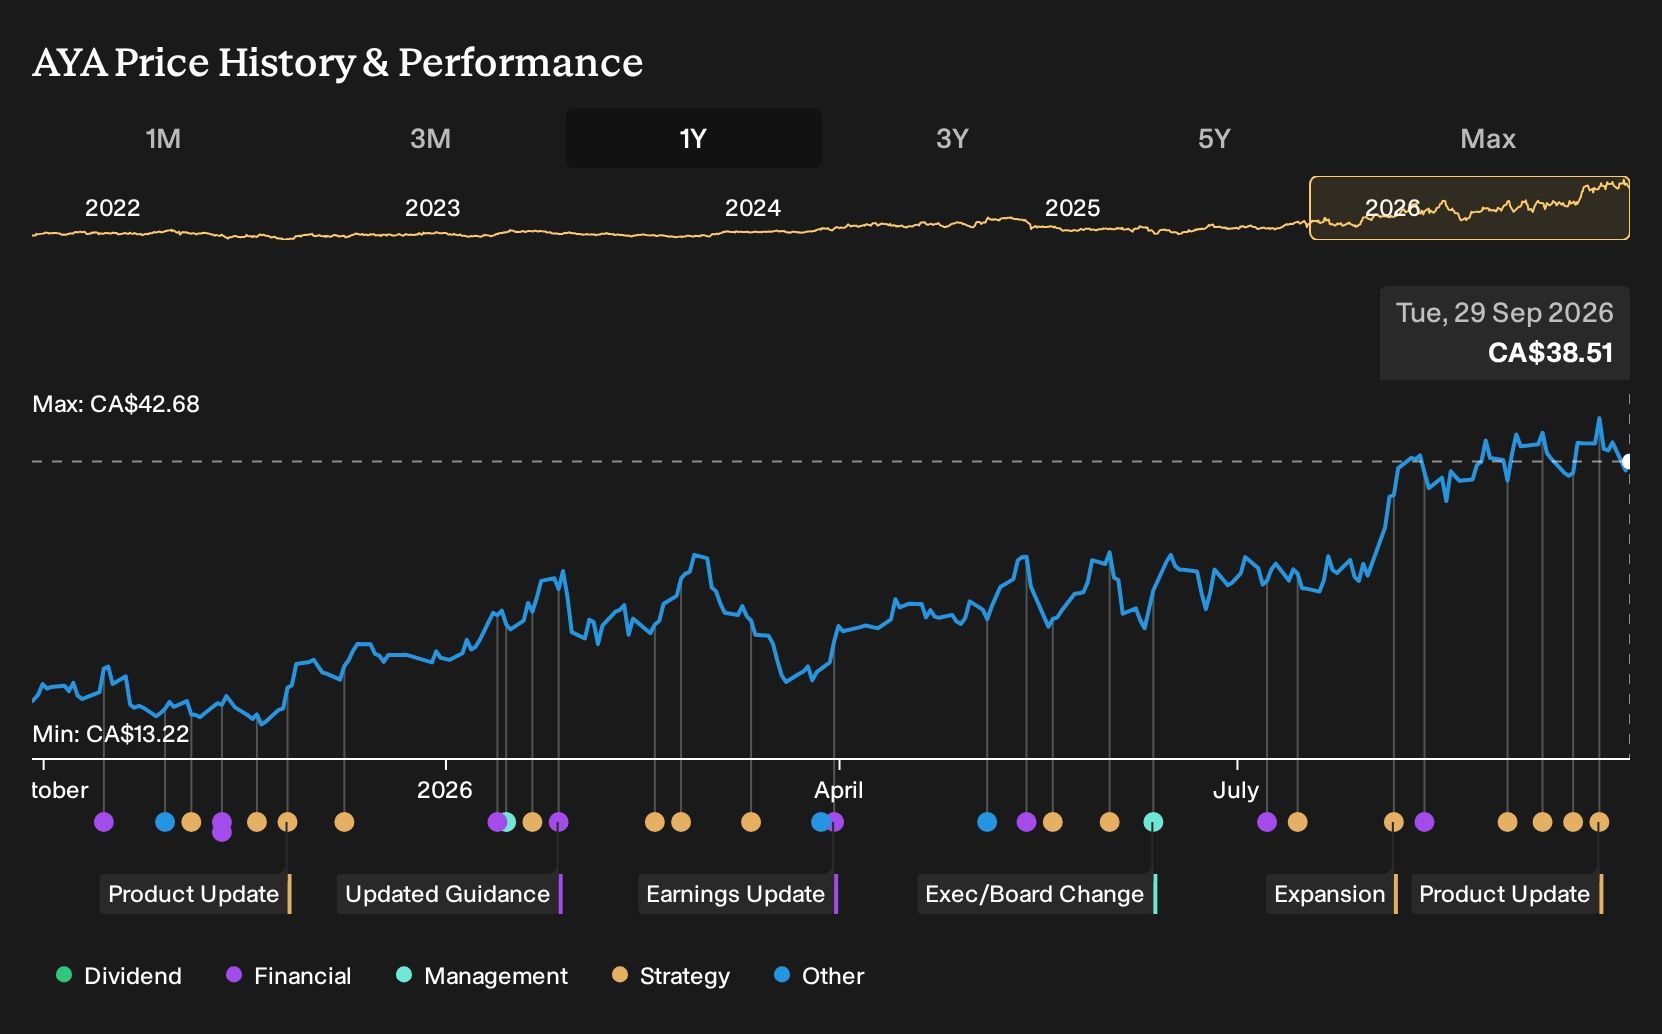
Exploring Other Perspectives
One alternate angle to watch is dilution risk. The most pessimistic analysts were already modeling earnings of about $57.5 million on $191.4 million of revenue by 2028, while assuming shares outstanding climb roughly 7% per year. That paints a much harsher Aya Gold & Silver story, and these pre news views may shift as new drilling data lands.
Explore 5 other Aya Gold & Silver fair value estimates, including one that suggests as much as 89% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis and judgment.
- A great starting point for your Aya Gold & Silver research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Aya Gold & Silver. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aya Gold & Silver's overall financial health at a glance.
Looking For More Investment Ideas Beyond Aya Gold & Silver?
If Aya Gold & Silver has sharpened your focus on where drilling dollars and project work can create value, it can be useful to line it up against other opportunities on different parts of the risk and quality spectrum using the Simply Wall St Screener.
- For investors who want potential mispricings with quality fundamentals, scan a curated 6 high quality undervalued stocks that may offer a more attractive balance between business strength and current share price.
- If capital preservation sits high on your list, narrow the field to companies in our 7 resilient stocks with low risk scores that combine more resilient profiles with measured risk scores.
- When you want sturdier fundamentals and less fragile balance sheets, start with a list of solid balance sheet and fundamentals (7 results) and compare how those businesses stack up against Aya Gold & Silver on leverage and financial flexibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com