
A $60 Billion Amazon Opportunity Is Changing Qualcomm's Chip Story
Qualcomm’s (QCOM) story has been under pressure. Smartphones still drive a large part of its business. However, handset revenue has weakened recently, with Apple reducing its reliance on Qualcomm for modem chips.
Now Amazon (AMZN) is giving Qualcomm something it has been chasing for years—a foothold in the AI data center market. Will this potential $60 billion deal turn Qualcomm from a smartphone chip heavyweight into a serious AI infrastructure player?
Let’s find out.
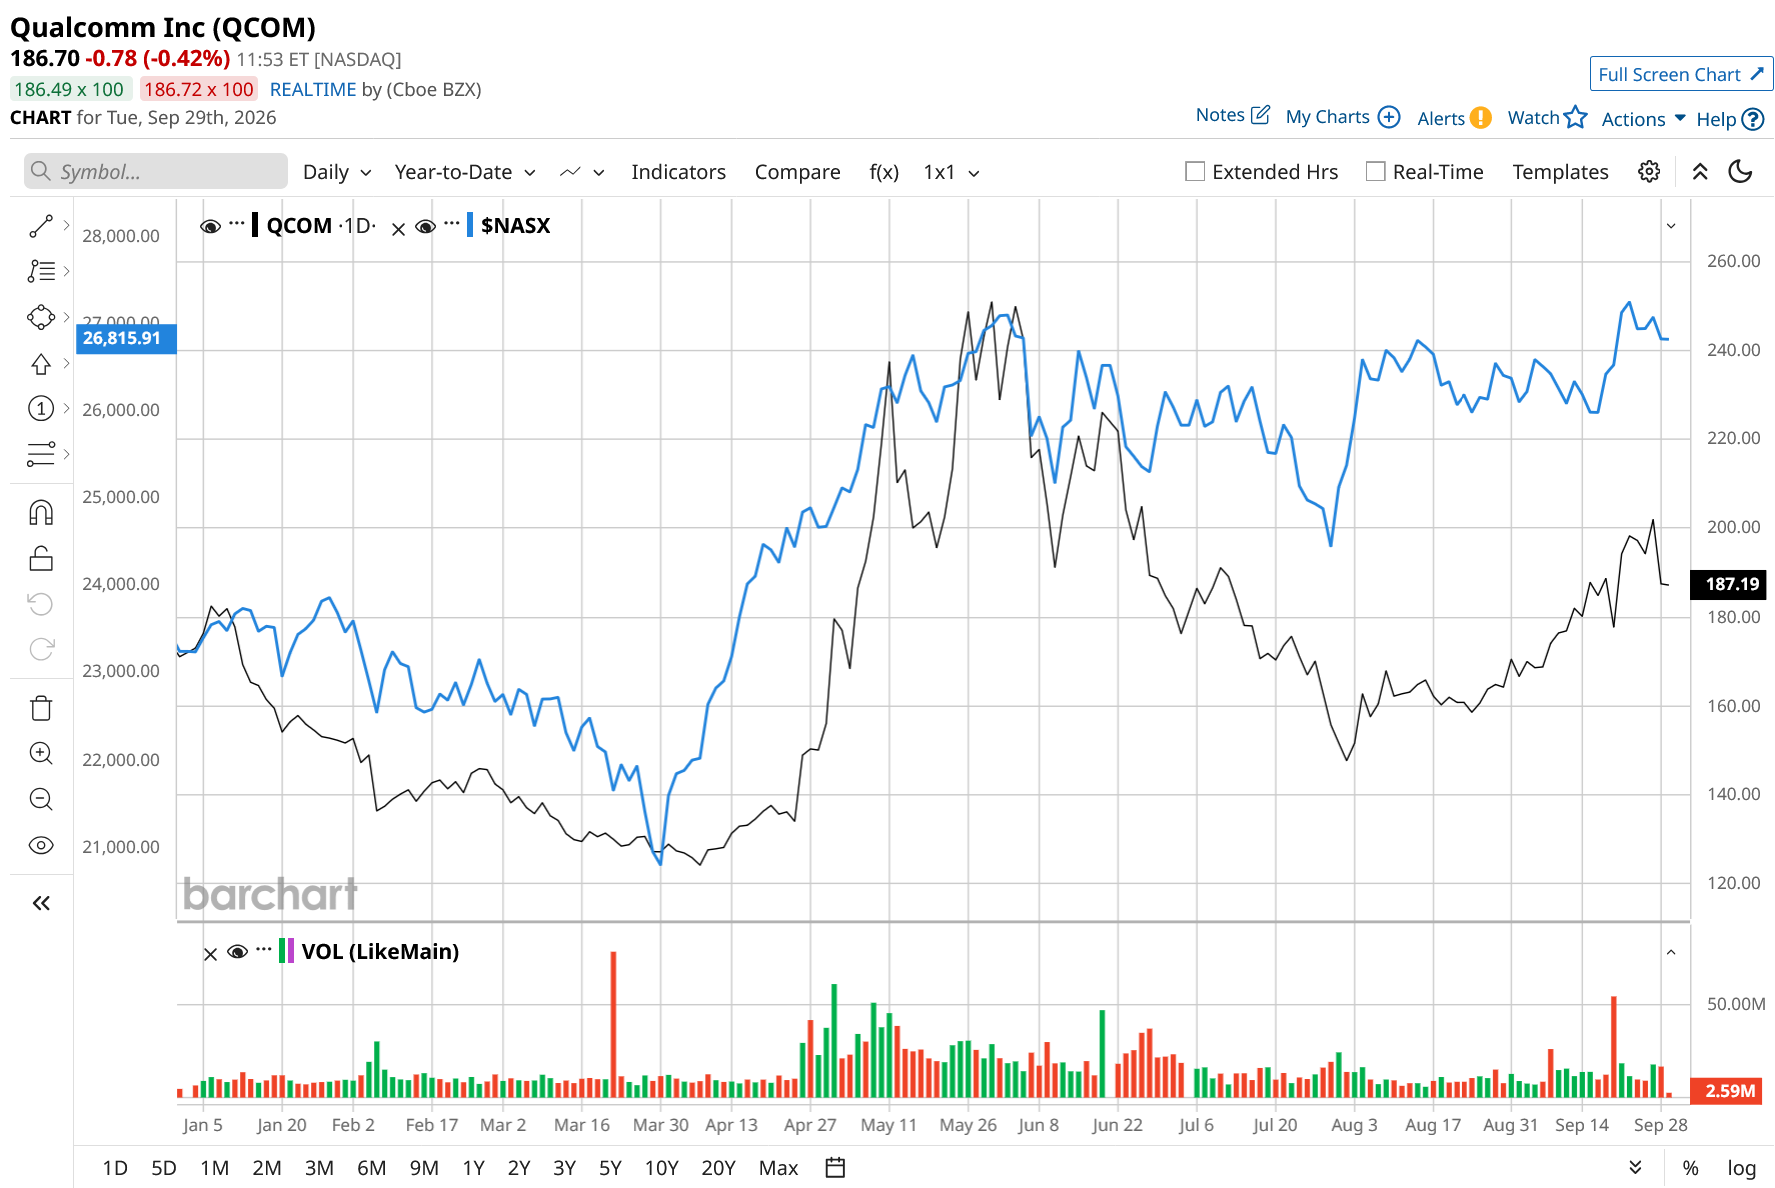
Qualcomm Needed a New Growth Story
Sitting with a market cap of $212 billion, Qualcomm is a semiconductor and technology company best known for designing chips and licensing wireless technology. Its QCT (Qualcomm CDMA Technologies) segment is its chip business for handsets, automotive, IoT, and data centers. Meanwhile, its QTL (Qualcomm Technology Licensing) licenses its extensive portfolio of wireless technology patents to generate royalty revenue.
For years, Qualcomm's story has largely revolved around smartphones. While the smartphone business remains enormous, it has been a drag on its financials. In the fiscal third quarter, handset revenue fell 20% year-over-year (YoY) to $5.09 billion. Although automotive revenue jumped 61% and IoT revenue increased 9%, overall QCT segment revenue dipped 5% to $8.5 billion. At its June 2026 Investor Day, Qualcomm said it expects non-handset revenue to reach $40 billion by fiscal 2029, roughly twice the target it had previously established. Data centers are supposed to become a major part of that expansion, with Qualcomm targeting more than $15 billion in data center revenue by fiscal 2029.
Amazon is Opening New Doors of Opportunity
The Amazon deal opened new doors for its data center ambition. Recently, Qualcomm and Amazon announced working together on chips and other technology for Amazon’s AI data centers. The partnership will initially focus on AI inference, which is the computing needed to run AI models and generate responses. Furthermore, Qualcomm will also provide the technology for moving data around these data centers at very high speeds. The agreement includes optical connectivity products based on its SerDes and optical DSP technologies, with the initial generation reaching 1.6T and later generations planned.
This is where Qualcomm’s $2.4 billion acquisition of Alphawave will be beneficial. It allows Qualcomm to use a broader portfolio in an actual hyperscale deployment. In other words, this partnership is expected to cover several generations of products, so this is bigger than a one-time chip order.
As part of the agreement, Amazon received the right to buy up to 25 million Qualcomm shares at $161.26 per share. Some of those rights become available as Amazon meets certain commitments to buy Qualcomm's data center products and services. Those purchases can eventually reach as much as $60 billion under the agreement. However, this doesn’t mean that Amazon has agreed to outright pay Qualcomm $60 billion. It represents the maximum level of purchases tied to the agreement's warrant structure.
The timing of this deal is just perfect for Qualcomm’s data center buildout. After the Amazon agreement, CFO Palkhiwala is now highly confident of achieving the data center target, as Qualcomm already has purchase orders and is producing chips for Amazon. The company expects revenue from Amazon to begin in the December quarter. Palkhiwala also specifically said that while Amazon is one of the core components supporting the company’s fiscal 2029 goal, the company is also working with another undisclosed hyperscaler.
Amazon Could Be the Proof Qualcomm Needed
Qualcomm has spent years trying to prove that its expertise in low-power computing, connectivity, and chip design can take the company beyond smartphones. While Automotive and IoT have already proved that, Amazon now gives Qualcomm a hyperscale customer and a real opportunity to establish itself in AI infrastructure. For Qualcomm, the Amazon deal may just be the validation it needed. It gives the company a foothold in a market where spending is surging and where Qualcomm has been trying to build a business.
That said, Qualcomm still has to turn Amazon’s commitment into large-scale deployments and prove that its chips can deliver the performance, power efficiency, and reliability that hyperscalers demand.
On Wall Street, QCOM stock holds a consensus “Hold” rating. Of the 33 analysts covering the stock, nine rate it a “Strong Buy,” two say it is a “Moderate Buy,” 18 recommend holding it, while one says it is a “Moderate Sell,” and three rate it a “Strong Sell.” QCOM has climbed 9% year-to-date (YTD) and currently trades just below its mean target price of $198.31. However, its high target price of $400 implies an upside potential of 114% over the next year.
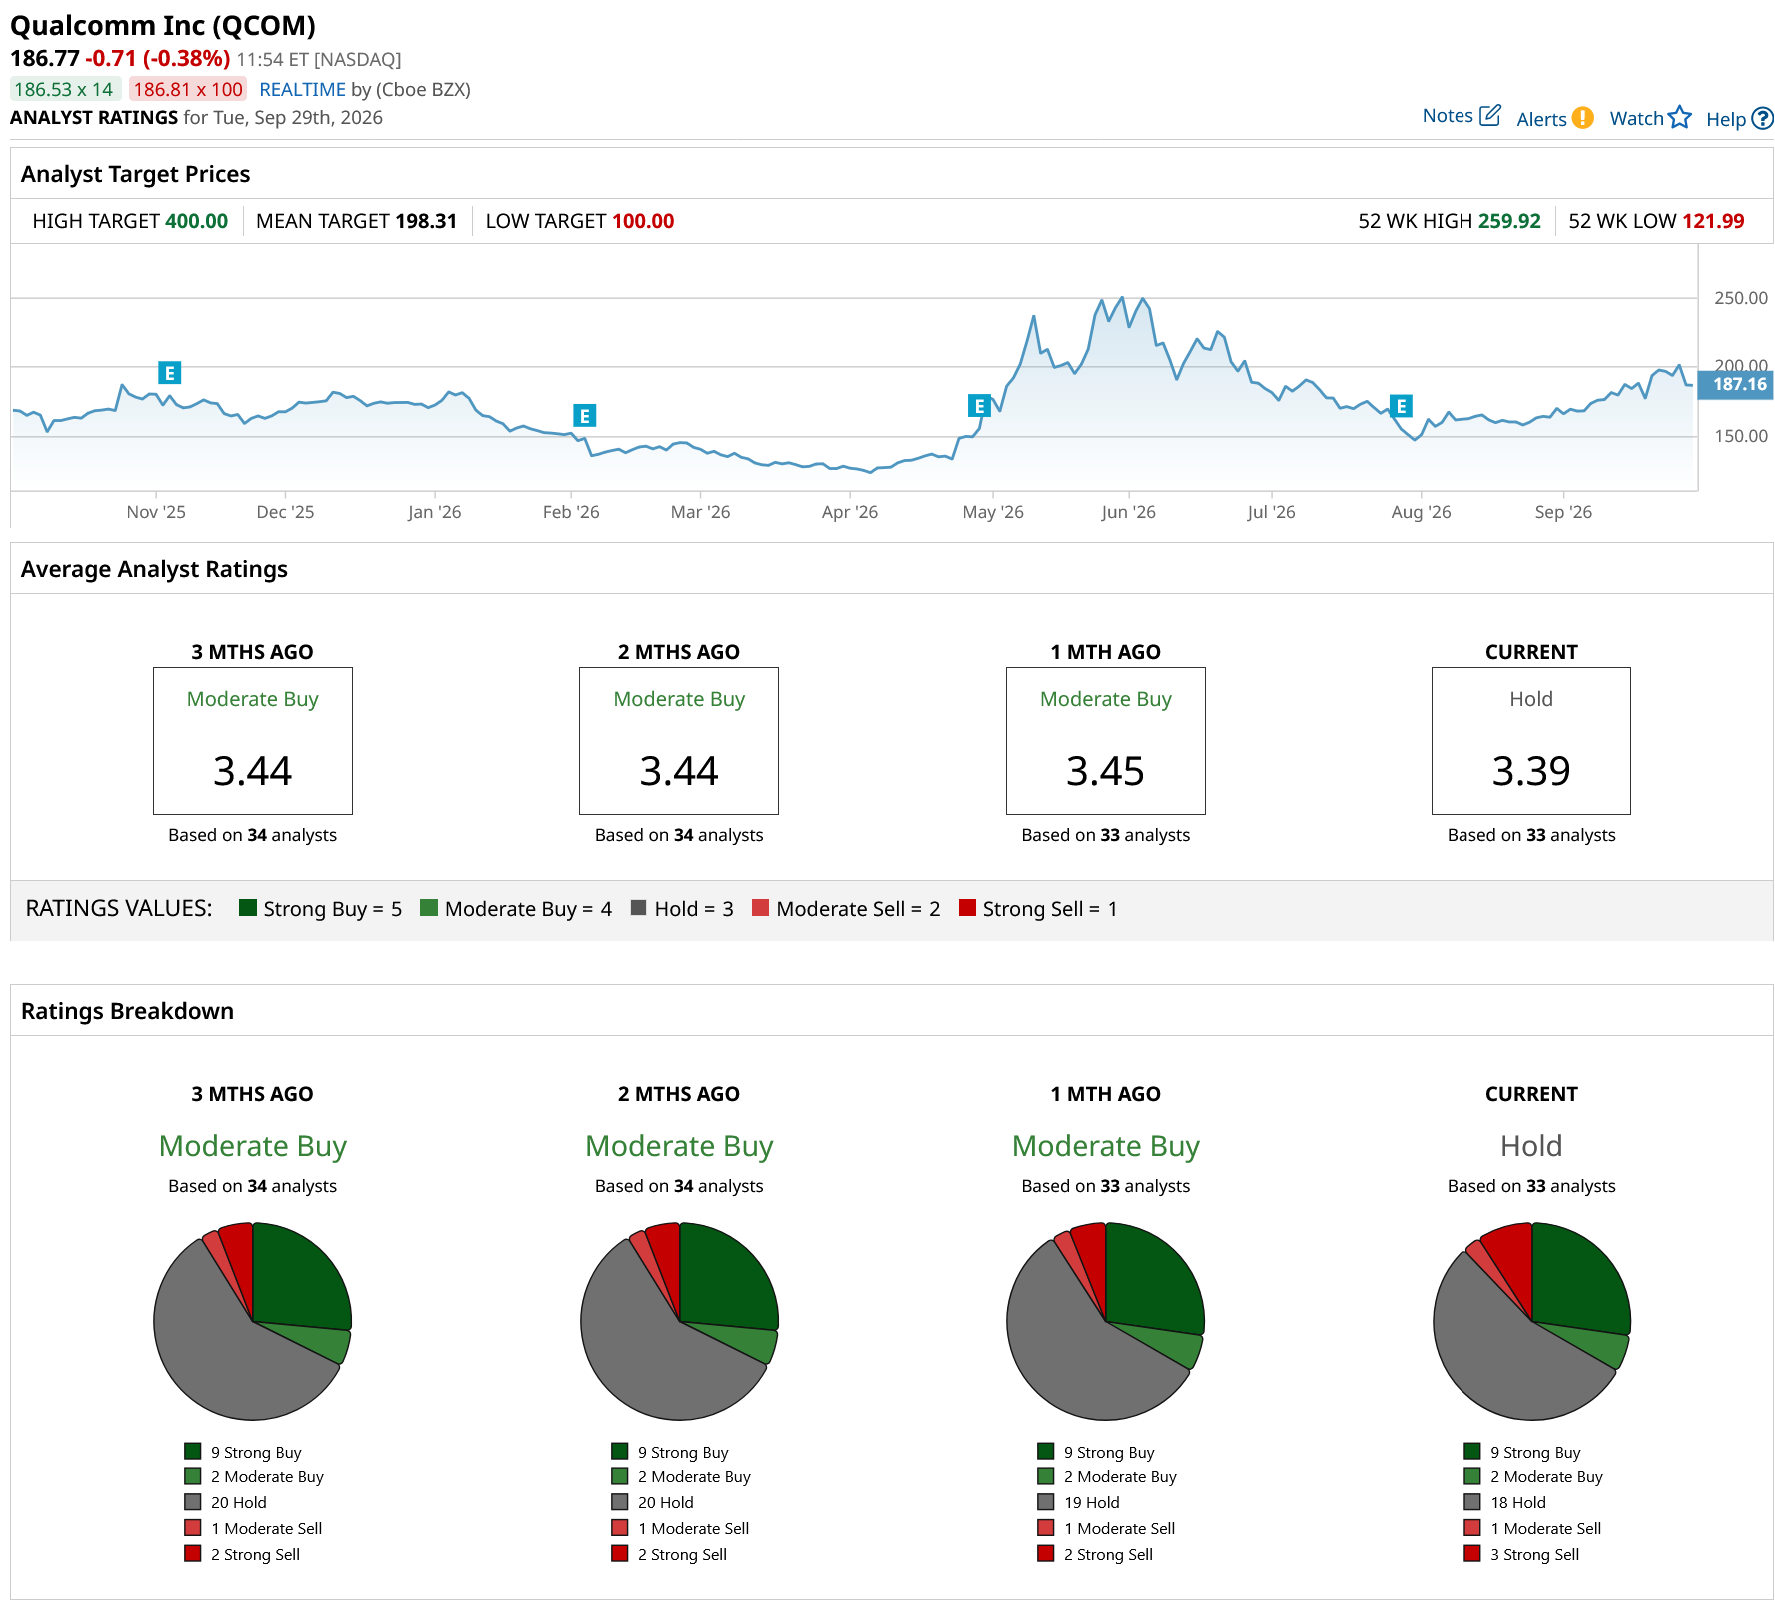
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.