
Canada's Undiscovered Gems Including 3 Promising Small Caps
In recent months, the Canadian market has shown impressive resilience despite global economic uncertainties, with large-cap stocks often overshadowing their smaller counterparts. As inflation concerns and geopolitical tensions continue to impact market dynamics, uncovering promising small-cap stocks requires a keen understanding of macroeconomic forces and an eye for potential growth opportunities that align with current conditions.
Top 10 Undiscovered Gems With Strong Fundamentals In Canada
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
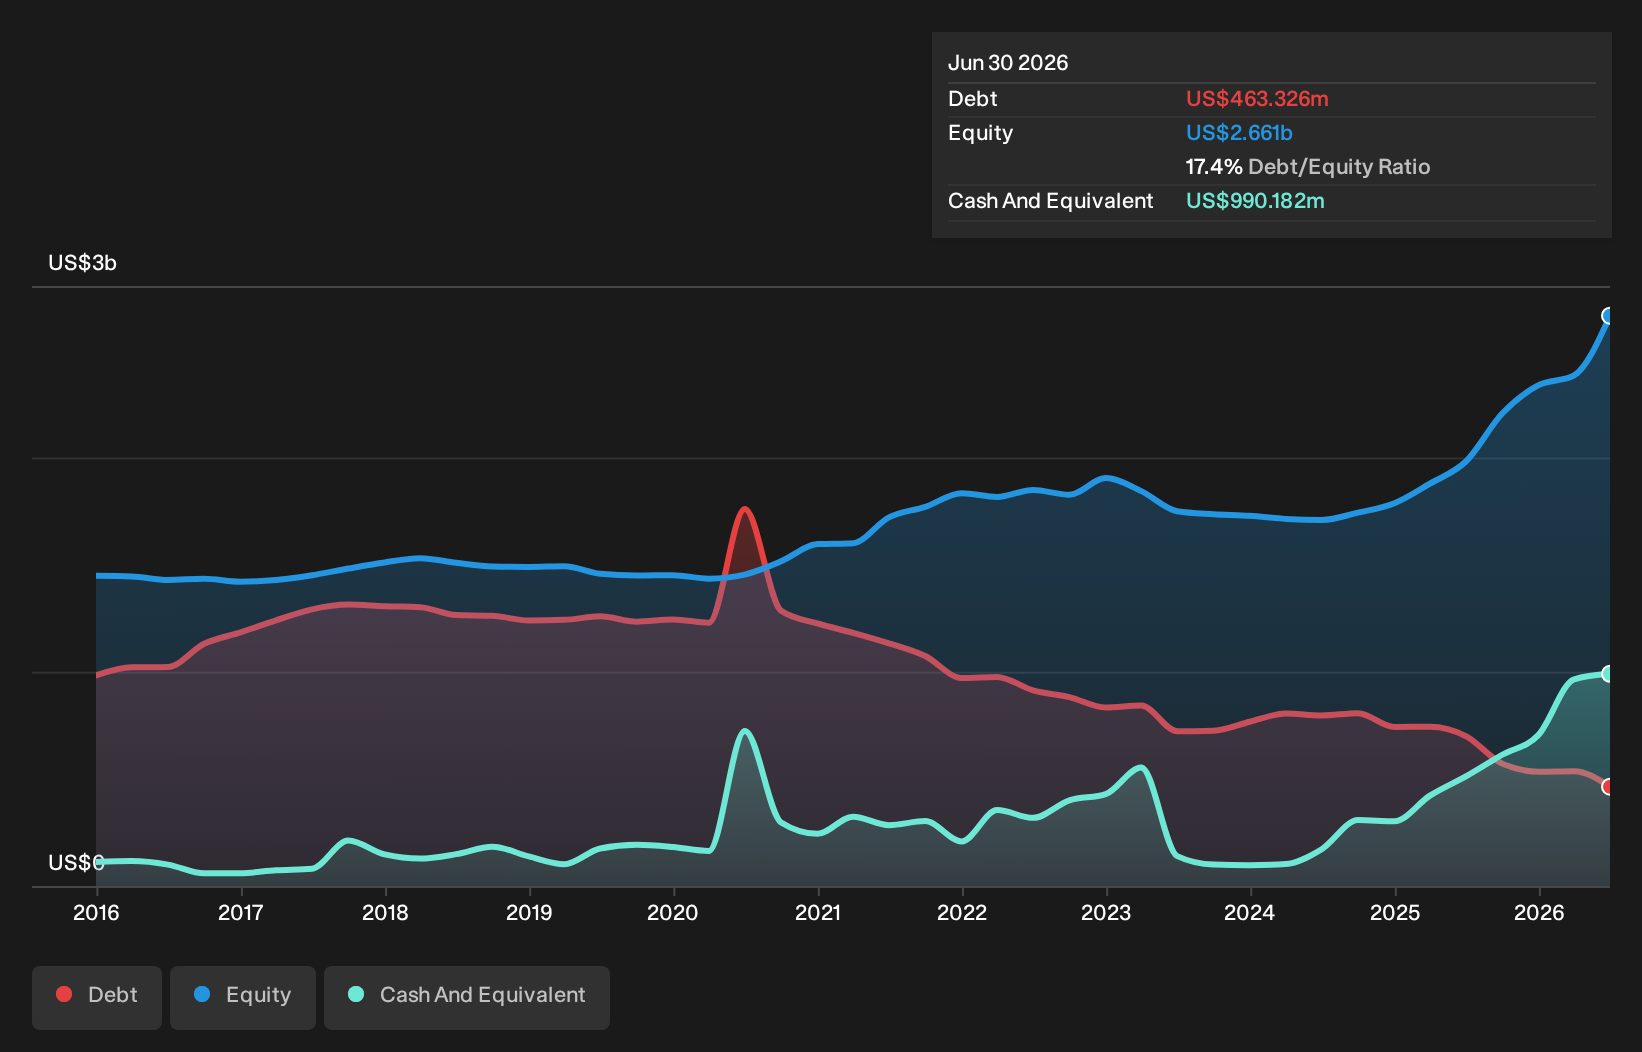
| China Gold International Resources | 17.41% | 2.90% | 18.32% | ★★★★★★ |
| Total Energy Services | 3.93% | 18.21% | 37.46% | ★★★★★★ |
| Thor Explorations | NA | 38.45% | 61.95% | ★★★★★★ |
| Alvopetro Energy | 18.59% | 7.72% | 6.43% | ★★★★★☆ |
| K92 Mining | 4.04% | 35.93% | 58.04% | ★★★★★☆ |
| Luca Mining | 47.11% | 35.45% | -50.81% | ★★★★★☆ |
| Hydreight Technologies | 22.28% | 71.66% | 59.41% | ★★★★☆☆ |
| Richards Group | 44.27% | -2.06% | -0.80% | ★★★★☆☆ |
| Kolibri Global Energy | 20.09% | 25.10% | -21.44% | ★★★★☆☆ |
| Rio2 | 22.38% | 105.97% | 53.08% | ★★★☆☆☆ |
We're going to check out a few of the best picks from our screener tool.
China Gold International Resources (TSX:CGG)
Simply Wall St Value Rating: ★★★★★★
Overview: China Gold International Resources Corp. Ltd. is a mining company focused on acquiring, exploring, developing, and mining gold and base metal resources in China and Canada, with a market capitalization of CA$15.61 billion.
Operations: The company's revenue primarily comes from mine-produced copper concentrate, generating $1.24 billion, and mine-produced gold, contributing $399.26 million.
China Gold International Resources, a smaller player in the mining sector, has shown impressive earnings growth of 162.6% over the past year, outpacing its industry peers' 130.3%. The company trades at a substantial discount, about 68.1% below its estimated fair value, suggesting potential for value investors. Despite challenges like a temporary suspension at the CSH Mine due to slope instability, which required RMB 98 million in remediation costs, CGG remains financially robust with more cash than total debt and free cash flow positivity. The recent mineral resource update for Jiama Project further strengthens its long-term prospects.
K92 Mining (TSX:KNT)
Simply Wall St Value Rating: ★★★★★☆
Overview: K92 Mining Inc. focuses on the exploration and development of mineral deposits in Papua New Guinea, with a market cap of CA$6.82 billion.
Operations: K92 Mining generates revenue primarily from its Kainantu Project, which contributed $795.83 million. The company has a market cap of CA$6.82 billion.
K92 Mining, a promising player in the mining sector, has demonstrated impressive financial growth with earnings increasing by 58% annually over the past five years. The company is trading at a significant discount, about 83.7% below its estimated fair value, suggesting potential for value appreciation. Despite having more cash than total debt and maintaining positive free cash flow, K92 faces challenges such as jurisdictional risks in Papua New Guinea and fluctuations in gold prices that could impact production stability. Recent leadership changes aim to bolster strategic direction as David Medilek steps up as CEO effective October 1, 2026.

Rio2 (TSX:RIO)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Rio2 Limited focuses on the exploration, development, and mining of mineral properties across Canada, Peru, Bahamas, and Chile with a market capitalization of CA$1.83 billion.
Operations: The company does not report any revenue segments, indicating a focus on early-stage exploration and development activities rather than current production. With a market capitalization of CA$1.83 billion, it appears to be in the investment phase, potentially incurring costs related to exploration and project development without generating revenue from mineral sales.
Rio2 is carving out a niche in the mining sector with impressive financial strides and strategic projects. Over the past year, earnings surged by 4776.5%, significantly outpacing the industry average of 130.3%. The company trades at 85% below its estimated fair value, presenting potential for investors seeking undervalued opportunities. Rio2's net debt to equity ratio stands at a satisfactory 9.5%, indicating prudent financial management despite an increase in total debt over five years from zero to 22.4%. Recent regulatory approval for expanding its Condestable mine enhances operational capacity and extends its environmentally approved lifespan by a decade, underscoring robust future prospects.
- Take a closer look at Rio2's potential here in our health report.
Gain insights into Rio2's past trends and performance with our Past report.

Make It Happen
- Access the full spectrum of 11 TSX Undiscovered Gems With Strong Fundamentals by clicking on this link.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com