
Learn Why The Bull Case For Ondas (ONDS) Could Change Following SSE Drone Deal
- Cyberhawk, a subsidiary of Ondas, recently secured a three year agreement with SSE for drone inspection and surveying across UK electricity networks, with an option to extend. The scope now includes offshore wind turbine inspection plus renewed digital asset intelligence services.
- This combination of recurring inspection work and extended use of Cyberhawk’s iHawk as a Service platform points to deeper integration into SSE’s critical infrastructure workflows. This matters for Ondas because it can influence contract visibility, utilization of drone fleets, and software driven revenue mix.
- We will look at how Ondas' investment narrative is shaped by this expanded SSE drone and offshore wind inspection agreement.
Scan other infrastructure focused drone and grid technology plays that are moving on similar contract momentum with utilities and renewables using the curated list of 39 power grid technology and infrastructure stocks
Ondas Investment Narrative Recap
To own Ondas, you need to believe the shift toward autonomous defense systems, drones, and private networks can translate into sustained contract flow across defense and infrastructure customers. The new SSE deal helps that story a little. It reinforces the drone and software side but does not change the fact that Ondas is still early in scaling its platforms.
The key near term catalyst remains execution at Ondas Autonomous Systems and converting its backlog into cash flow while managing volatile margins. The biggest risk is that high operating costs and debt, alongside past disruptions and timeline slippage, limit flexibility if expected revenue growth or defense orders do not arrive as planned.
The SSE agreement lines up most cleanly with the Ondas narrative that recurring autonomous systems deployments can support revenue growth, which is currently forecast at 36.5% per year. It gives Cyberhawk more contracted visibility in utilities and renewables, while tying customers more tightly to iHawk as a Service and drone inspection workflows.
For catalysts, this matters because investors are already weighing a very large three year share price move against premium P/E multiples and earnings that are forecast to decline on average. Progress on long term, operations heavy contracts like SSE can help test whether Ondas’ mix of drones, software, and private wireless can scale fast enough to offset margin volatility and funding risk.
Ondas' narrative projects US$1.0b revenue and US$114.4 million earnings by 2029. This assumes revenue growth of 119.3% per year and an earnings decline of US$19.8 million from US$134.2 million today.
Uncover why Ondas' fair value indicates a 169% potential upside to its current price that could narrow quickly.
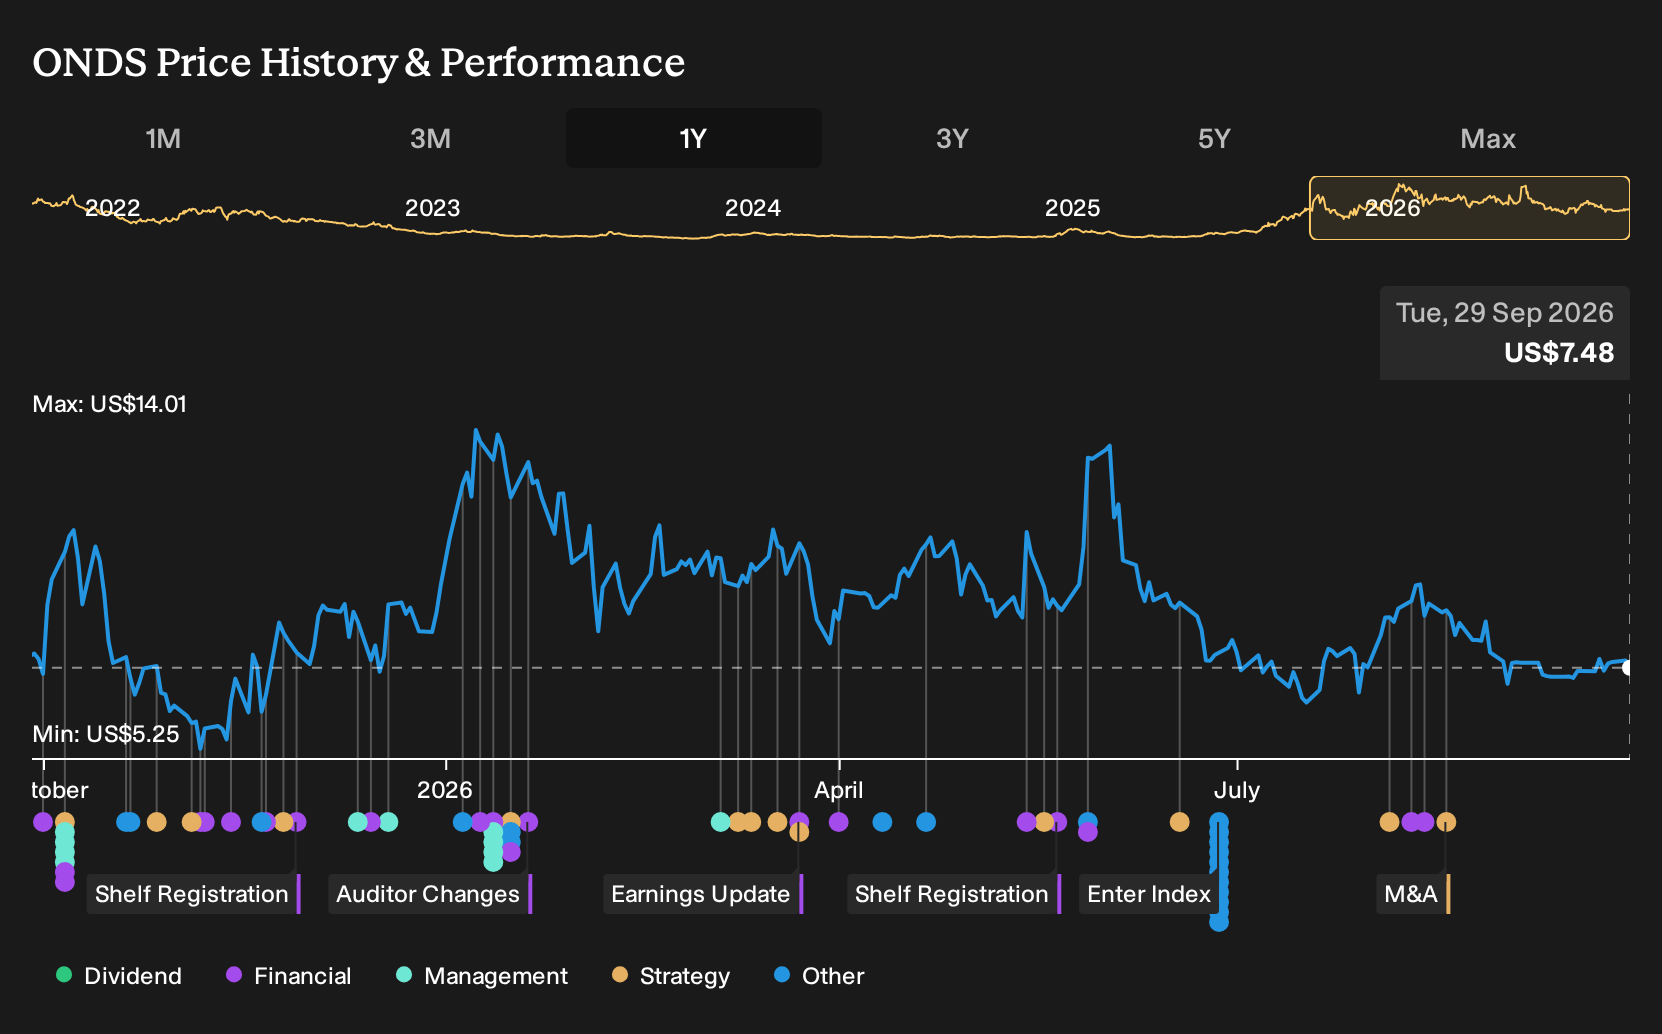
Exploring Other Perspectives
The most optimistic analysts focus on Ondas turning defense and counter drone demand into very rapid growth, with revenue forecasts near 170% a year and possible earnings of US$213.4 million by 2029. That is a far more upbeat story than the consensus US$1.0b revenue view. The new SSE contract sits outside those older projections, so you should expect opinions to shift as you compare these different sets of assumptions.
Explore 8 other Ondas fair value estimates, including one that suggests potential upside of as much as 245% from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Ondas research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Ondas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ondas' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ondas?
If the Ondas story has you thinking about where else contract driven growth or balance sheet strength might be hiding, the Simply Wall St screener can help you widen the field without losing focus on quality.
- For investors willing to tolerate volatility in pursuit of higher potential, consider scanning a curated set of smaller, higher risk opportunities via 9 elite penny stocks with strong financials.
- If capital preservation and stability are higher on your list, focus on businesses with sturdier finances by reviewing the 32 resilient stocks with low risk scores.
- When you want quality, financial resilience, and room for upside in one place, start with the 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com