
3 Canadian Pipeline Stocks To Watch In September 2026
US Federal Reserve officials now signal that tighter policy may extend into 2026, which keeps pressure on borrowers and rewards businesses with steady, fee based cash flows. That puts American midstream oil and gas pipeline operators in focus, since they are paid to move molecules, not bet on commodity prices. This article walks through three stocks from this group that many investors are still overlooking.
The three midstream operators covered below are just a starting sample, and the full screen surfaced 6 more US pipeline and storage businesses with equally compelling narratives that are not unpacked in this article. If you want to identify and analyze the highest conviction midstream plays tied to Trump’s early 2025 fossil fuel orders, head straight into the US Midstream Oil and Gas Pipeline Operators screener.
Enbridge (TSX:ENB)
Overview: Enbridge is a large North American energy infrastructure company that primarily moves crude oil and natural gas through long haul pipelines, storage, and export facilities.
Operations: Enbridge generates most of its revenue from its Liquids Pipelines business at about CA$63.6b, with Gas Distribution and Storage at roughly CA$11.2b, Gas Transmission around CA$6.8b, and Renewable Power Generation contributing about CA$0.6b.
Market Cap: CA$148.4b
Enbridge matters for this midstream screen because its liquids pipelines and export terminals sit directly in the path of any push to move higher North American production to end markets under faster permitting timelines.
"The Sunrise Expansion Program is expected to create more than 2,500 jobs and contribute to both the provincial and national economies through project spending and related activity."
What investors really need to watch is how one unresolved pressure on Enbridge’s balance sheet ultimately shapes future cash flow flexibility.
That balance sheet tension is exactly what the full narrative for Enbridge unpacks, showing how Enbridge’s capital choices could be masking a stronger and longer runway for its pipeline cash flows.
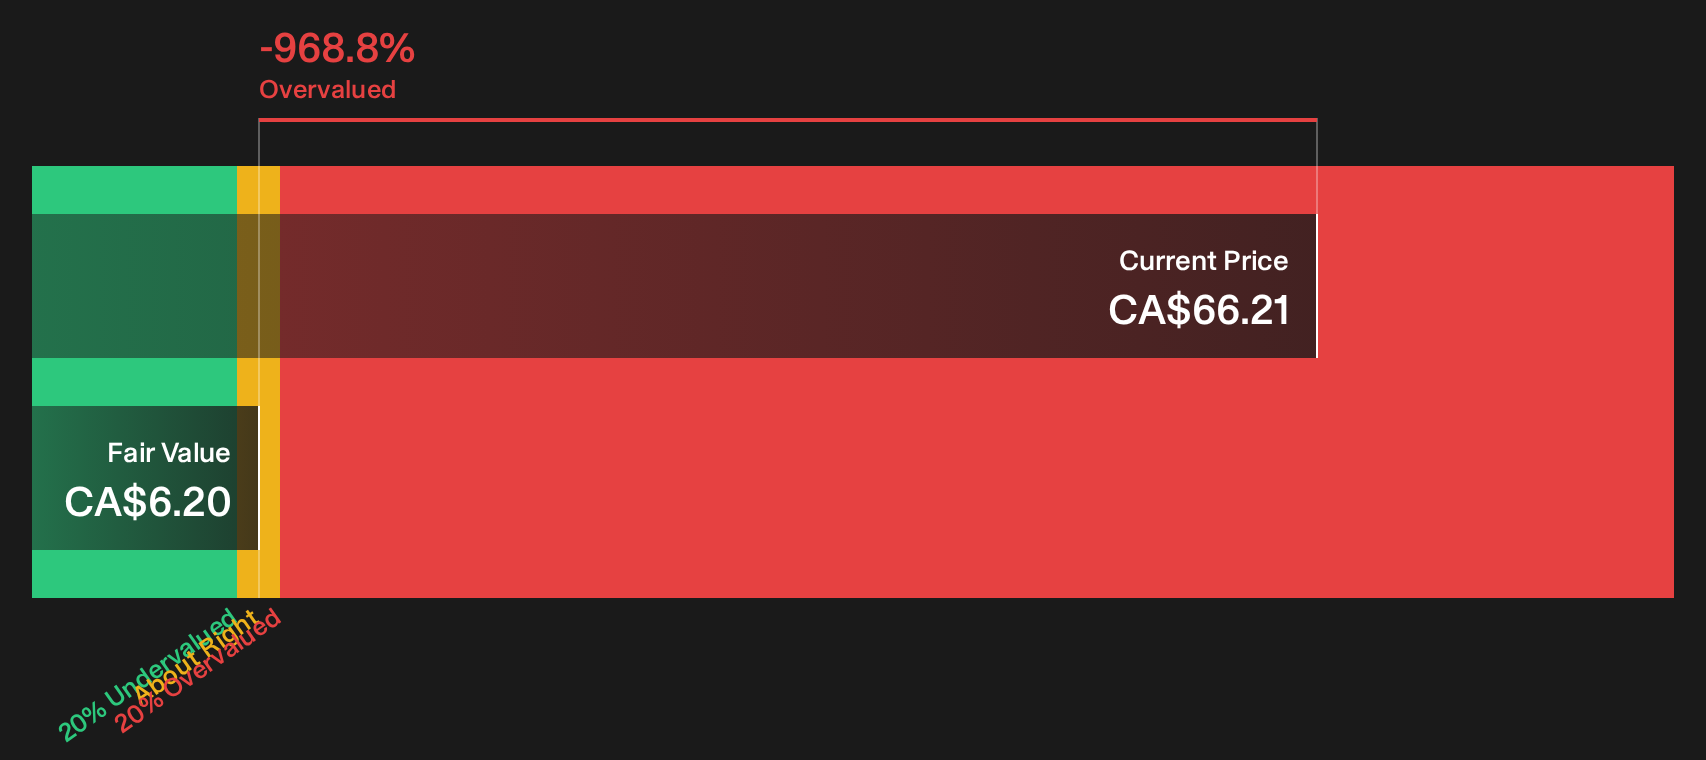
Cenovus Energy (TSX:CVE)
Overview: Cenovus Energy is an integrated Canadian oil and gas producer that develops, transports, stores, and refines hydrocarbons across North America and Asia.
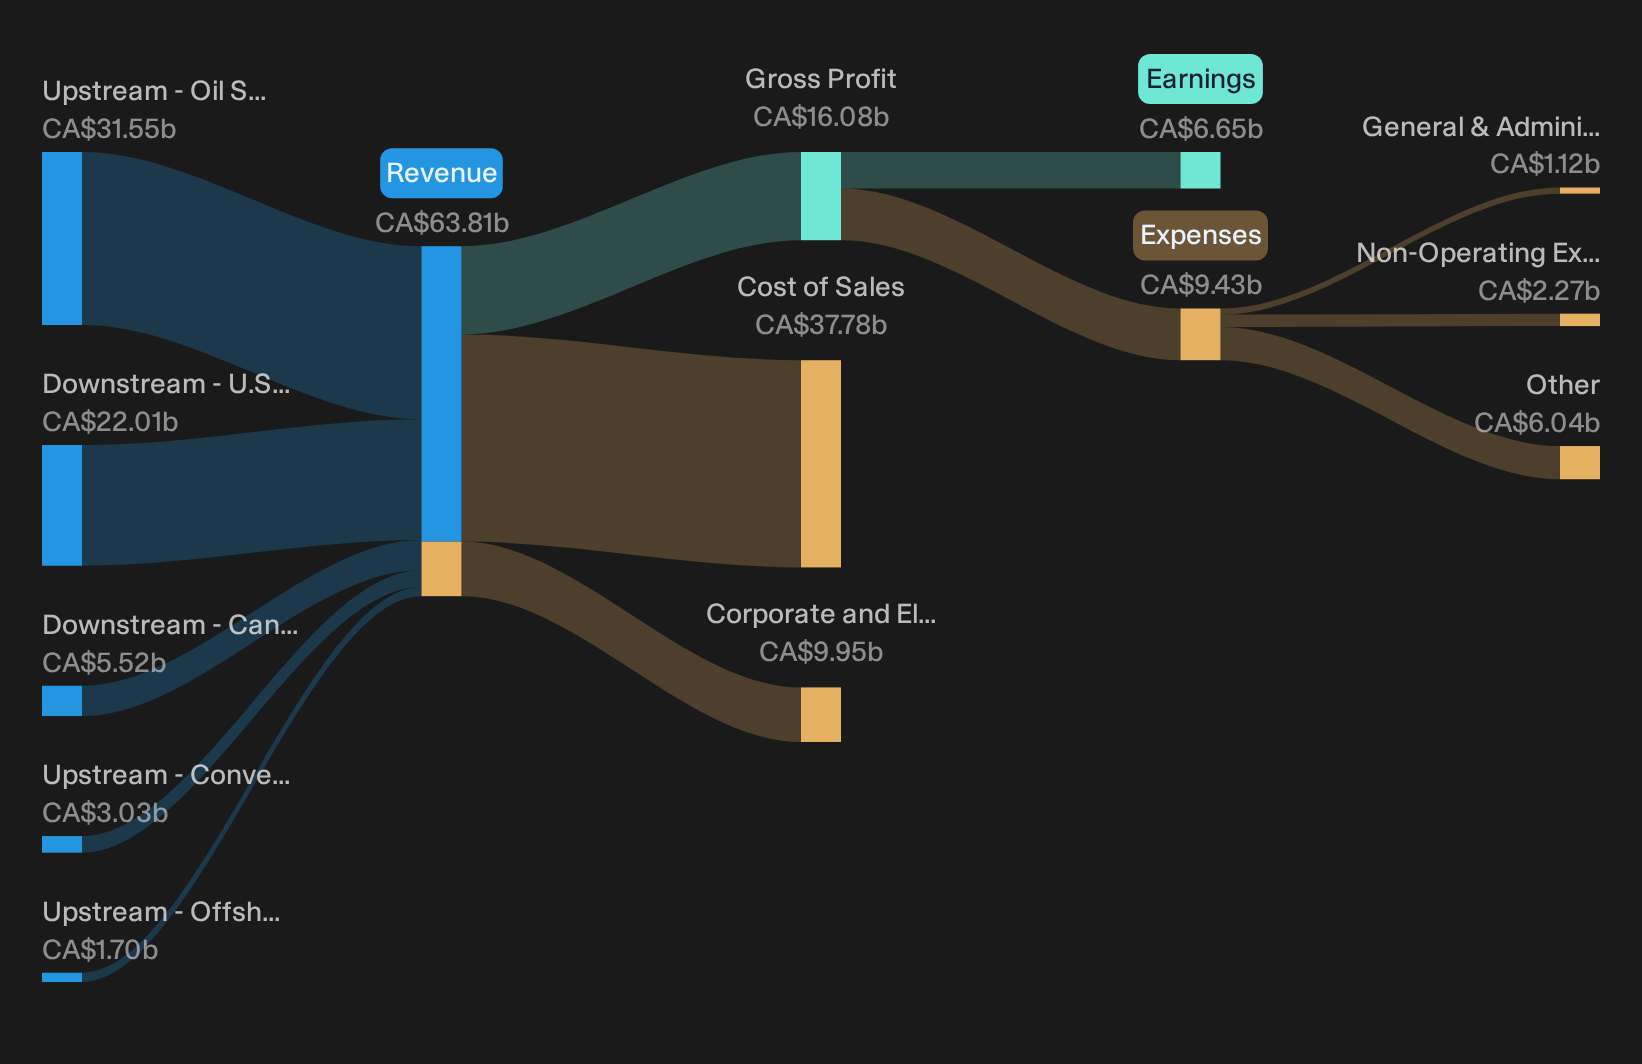
Operations: Cenovus generates most revenue from Oil Sands at CA$31.5b and U.S. refining at CA$22.0b, primarily serving Canada and the United States.
Market Cap: CA$81.4b
Cenovus Energy matters for this midstream focused screen because its gathering pipelines, terminals, and Bruderheim crude by rail hub directly connect higher output to refineries and export routes when policy tailwinds favor more infrastructure.
"Pipelines and storage facilities will be critical to moving larger volumes of oil and gas efficiently, especially with the renewed emphasis on LNG exports to meet global demand."
What ultimately happens to Cenovus’s margins comes down to how one key midstream bottleneck shapes pricing and export access.
That bottleneck is the real hinge for Cenovus Energy, and the full narrative for Cenovus Energy shows how pricing power, export access, and risk could be quietly decoupling.
Imperial Oil (TSX:IMO)
Overview: Imperial Oil is an integrated Canadian energy business that produces, refines, and transports hydrocarbons, with downstream pipelines and terminals closely linked to midstream demand.
Operations: Imperial Oil generates about CA$57.3b from Downstream, CA$17.2b from Upstream, and CA$1.4b from Chemical activities, with roughly CA$41.5b from Canada.
Market Cap: CA$83.9b
Imperial Oil matters in this pipeline focused screen because its downstream pipeline network and fuel terminals directly tie refining activity to midstream transportation and storage demand as policy support leans toward faster fossil fuel infrastructure build out.
"Pipelines and storage facilities will be critical to moving larger volumes of oil and gas efficiently, especially with the renewed emphasis on LNG exports to meet global demand."
What really determines how much investors benefit is how one underappreciated shift in throughput and margins interacts with that growing infrastructure push.
That hinge is exactly where the full narrative for Imperial Oil shows how Imperial Oil’s throughput, margins, and midstream leverage could be quietly accelerating beyond the headline pipeline story.

Seeking Fresh Alternatives With Real Potential
New themes gain momentum fast while older ideas get caught dropping out of focus. Scan curated stock sets under the radar for now and get in early.
- Spot income workhorses built on resilient cash flows before everyone else starts chasing yield with the 1 dividend fortresses.
- Target stronger balance sheets and healthier fundamentals while they are still flying under most investors’ screens through the list of solid balance sheet and fundamentals (7 results).
- Ride early momentum in power grid upgrades and supporting suppliers before that story becomes crowded by using the 39 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com