
Something Changed At Banco De Sabadell This Year
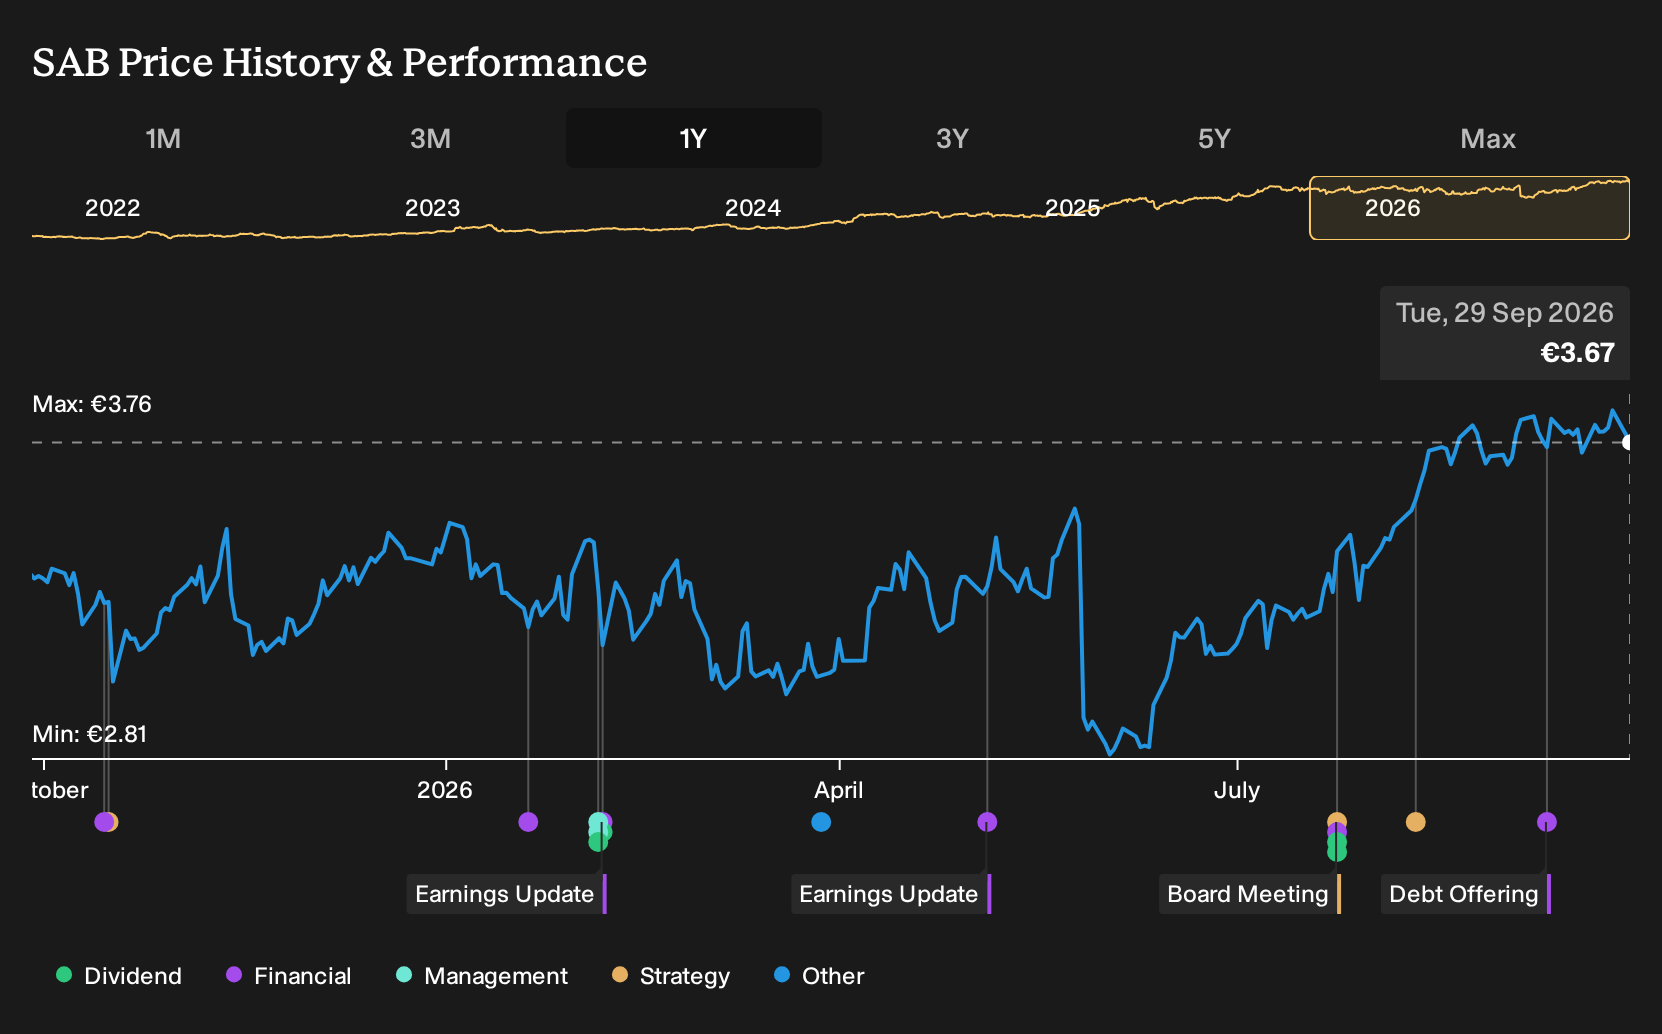
If you only glanced at Banco de Sabadell headlines this year, the eye catcher was not a new app or branch refresh but a hard Euro figure: the €331 million share buyback announced alongside strong Q2 2026 results and an extraordinary dividend funded by the TSB sale. Investors who held Banco de Sabadell over the past year are up 28.1%, including dividends. If you were deciding back on 29 September 2025, what had to be true about digital execution, capital returns, and Spain focused lending for that outcome to look reasonable?
Banco de Sabadell has already moved. See which of 196 high quality undervalued stocks still trade below our estimates.
The Two Banco de Sabadell Stories Investors Were Weighing
The shares cost €3.29 at the start of the period, and anyone looking at Banco de Sabadell then had to choose between two very different stories.
The bullish view saw a Fair Value of €4, a rough guide to what the stock might be worth if that script played out, built on expectations of rapid digital progress, shrinking non performing assets and extraordinary capital returns from the TSB sale.
The bearish narrative pointed to a Fair Value of €2.3, anchored in worries about legacy IT systems, an aging customer base in Spain and Europe, and higher regulatory costs squeezing long term profitability.
What The Results Changed For Banco de Sabadell
The Q2 2026 report for Banco de Sabadell backed parts of the optimistic script. Recurrent net profit was higher quarter on quarter, net interest income and customer funds were reported as stronger, and a €331 million buyback plus an extraordinary dividend pointed toward the capital return side of the thesis. The cautious case stayed alive because guidance still relied on future profitability targets rather than fresh, long run data. Overall, the evidence cut both ways.
The key assumption that really mattered here was execution on digital and capital heavy plans. When you look at another bank, check whether management promises show up in concrete actions such as new tech units, such as Sabadell’s AI focused restructure, and in actual cash distributions rather than only in forward looking guidance.
What Banco de Sabadell’s Price Now Asks You To Believe
Today Banco de Sabadell trades at €3.67, and this Narrative’s Fair Value sits below that level according to its own modelling. The view leans on the idea that richer pricing leaves less room for error as digital rivals and regulation pressure the traditional banking model.
As a buyer at today’s price, you would effectively be assuming Sabadell can keep loan growth and efficiency on track. The key question is how the Narrative’s concerns about digital disruption and legacy systems might affect that path.
"Despite the current acceleration in loan volumes and strong asset quality metrics, Banco de Sabadell faces a growing threat from accelerated digital disruption by fintech startups and global tech companies, which is likely to erode traditional banking market share over the coming years, ultimately placing downward pressure on future revenues and compressing fee income as more customers migrate to agile, technology-led competitors."
One Narrative disagrees with today's price. → See where this Narrative says Banco de Sabadell should trade
Where Banco de Sabadell’s Lesson Points
Watching Banco de Sabadell wrestle with digital execution raises a broader question. What if a bank is built mobile first from day one?
Instead of branches and legacy software, this other player runs almost entirely through a phone. Customers open accounts, move money and borrow inside a single app.
That model strips out much of the physical friction Sabadell is working around. It also aims to keep everyday account costs low for users.
Because everything flows through software, the provider leans heavily on automation and data. The open question is how far that kind of pure digital bank can stretch what a mainstream lender looks like.
That argument has a Narrative and a number behind it. → See the company one Narrative values 84% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com