
At Home HPV Partnership Might Change The Case For Investing In Waters (WAT)
- In September 2026, Everlywell announced a partnership with Waters Corporation to support at home use of the FDA cleared Onclarity HPV Self Collection Kit, with samples processed at CLIA certified labs and results delivered digitally with telehealth follow up.
- The collaboration places Waters inside a diagnostic workflow that targets cervical cancer screening gaps, linking at home testing to care pathways that are relevant for health plans responding to NCQA MY2026 updates and upcoming 2027 preventive care guidance.
- We will assess how Waters' investment narrative is influenced by its role in Everlywell's at home HPV screening workflow for health plans.
Scan beyond Waters and this HPV partnership by lining up diagnostics-focused peers, using the curated list of solid balance sheet and fundamentals (25 results) as a starting universe for further research.
Waters Investment Narrative Recap
To own Waters, you need to believe the enterprise can turn its analytical hardware base and service footprint into steadier earnings, even as academic and pharma discovery budgets look soft and profit margins sit at 3.6%, well below last year. The Everlywell relationship fits that thesis only modestly, since it is more about workflow relevance in diagnostics than a clear near term volume or margin event.
The near term swing factor still sits with the planned acquisition and integration of BD's Biosciences and Diagnostic Solutions units, along with realizing the modeled cost and revenue synergies. The biggest risk remains execution. Any delay, overruns, or disruption to legacy LCMS replacement cycles could pressure already thin profitability and keep valuation rich relative to Life Sciences peers.
The Everlywell HPV partnership links Waters into an at home screening workflow that responds directly to NCQA MY2026 and 2027 preventive care rules. That matters because the BD Onclarity HPV Assay sits in the middle of this process, so instrument reliability, uptime, and service quality directly influence how sticky these diagnostic workflows become for health plans and labs.
Viewed alongside the BD Biosciences and Diagnostic Solutions deal, this news offers a small but concrete example of what a broader clinical and diagnostics footprint could look like in practice. It highlights both the potential for more recurring usage around regulated assays and the operational risk if integration, support, or product upgrades fall short while academic and drug discovery demand remains under pressure.
Waters' narrative projects US$7.9b revenue and US$1.4b earnings by 2029. This assumes 19.3% yearly revenue growth and an earnings increase of about US$1.2b from current earnings of US$166.6m.
Uncover why Waters' fair value is broadly in line with its current price.
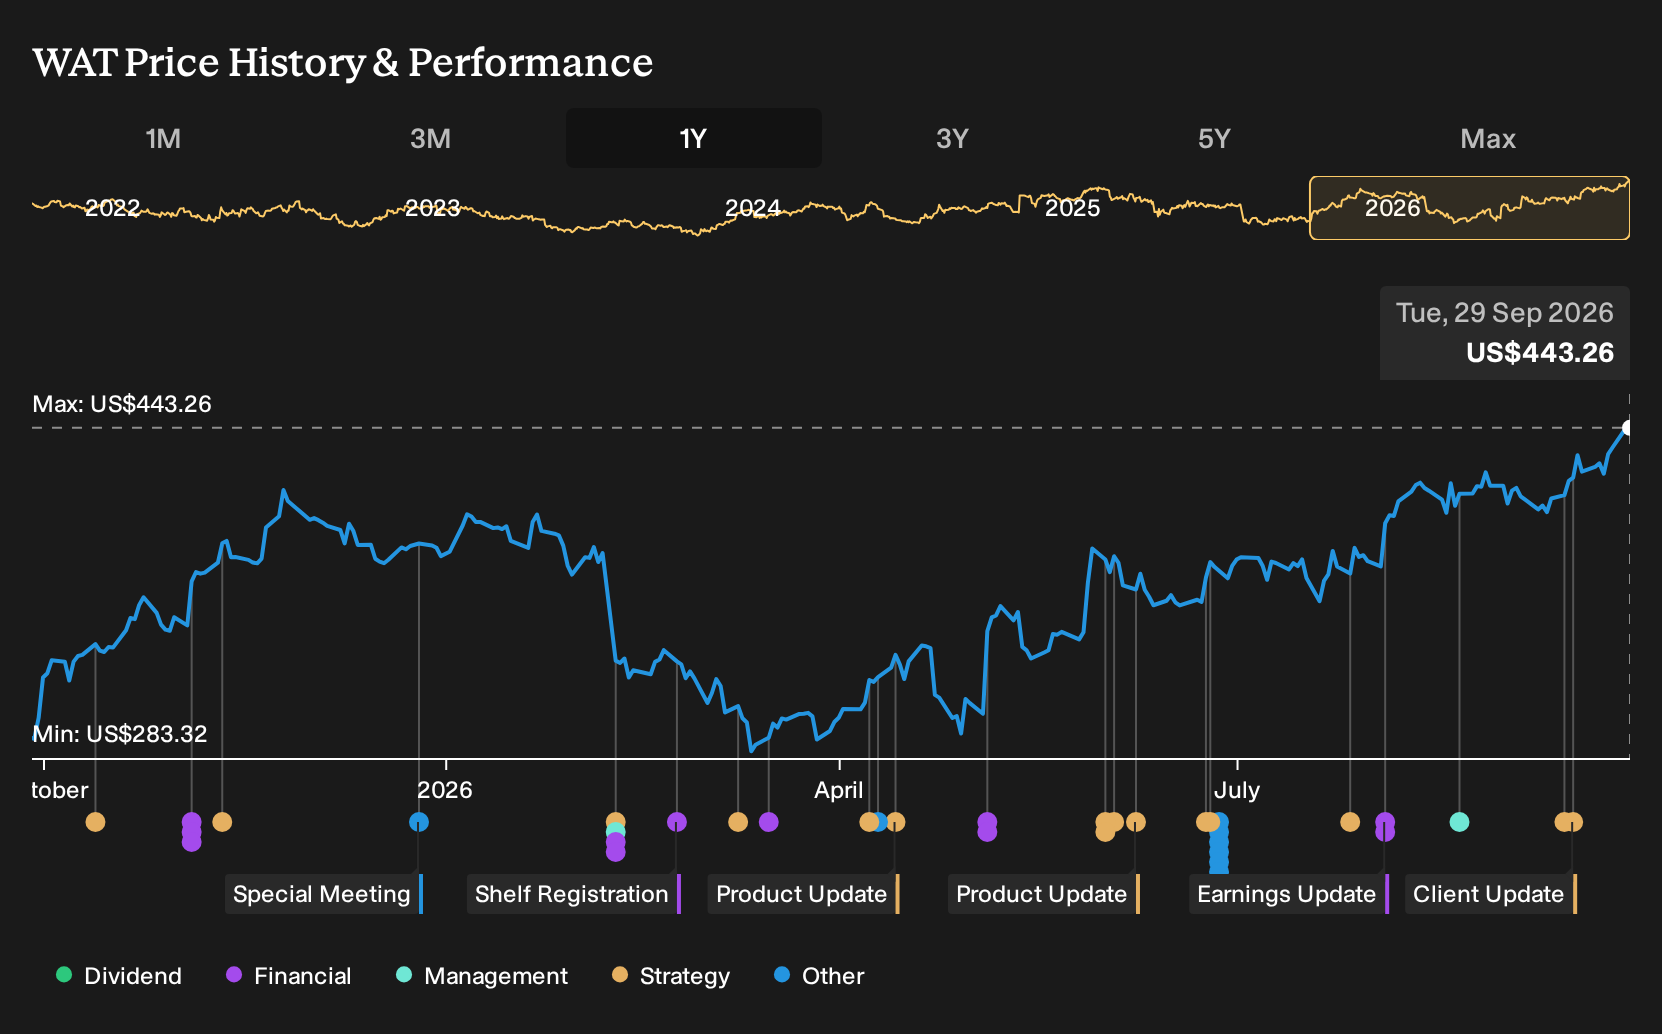
Exploring Other Perspectives
One alternate view on Waters leans hard into acquisition risk. The most cautious analysts worried that integration issues could cap earnings nearer US$1.1b by 2029 on US$7.9b revenue, compared with the consensus US$1.4b path, even before this Everlywell HPV news. Use that gap to test how your own expectations might shift as new data lands.
Explore 3 other Waters fair value estimates, including one that suggests as much as 12% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Waters research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Waters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waters' overall financial health at a glance.
Looking For More Investment Ideas Beyond Waters?
If the Waters story has sharpened your thinking but you want a broader watchlist, use the Simply Wall St Screener to line up other businesses that better match your risk profile and income goals.
- For investors hunting for resilience first, filter for companies that prioritise balance sheet strength with the 32 resilient stocks with low risk scores.
- If income is your main objective, focus on steady cash returns through the 6 dividend fortresses.
- When you want quality that is not already crowded, widen your research set using the 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com