
What to Expect From Philip Morris International’s Next Quarterly Earnings Report
Stamford, Connecticut-based Philip Morris International Inc. (PM), with a market capitalization of approximately $302 billion, is a global consumer goods company that manufactures and sells cigarettes and smoke-free nicotine products. Operating in about 170 markets, the company is transforming its business by developing science-backed smoke-free alternatives while gradually reducing its reliance on traditional cigarettes.
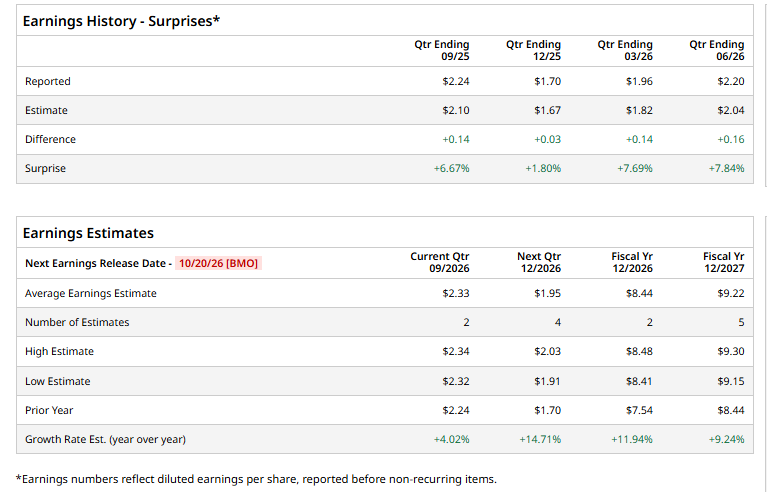
PM is set to report its Q3 earnings on Tuesday, October 20, 2026, before the market opens. Ahead of the release, analysts expect the company to report diluted EPS of $2.33, up 4% from $2.24 in the year-ago quarter. Moreover, PM has exceeded Wall Street’s EPS estimates in each of the past four quarters, which is admirable.
For fiscal 2026, analysts expect the company to report EPS of $8.44, up 11.9% from $7.54 in fiscal 2025. EPS is projected to increase another 9.2% year over year to $9.22 in fiscal 2027.
PM stock has gained 19% over the past 52 weeks, slightly outperforming the S&P 500 Index ($SPX), which advanced 15.2%, and the State Street Consumer Staples Select Sector SPDR ETF (XLP), which gained 4.8% over the same period.
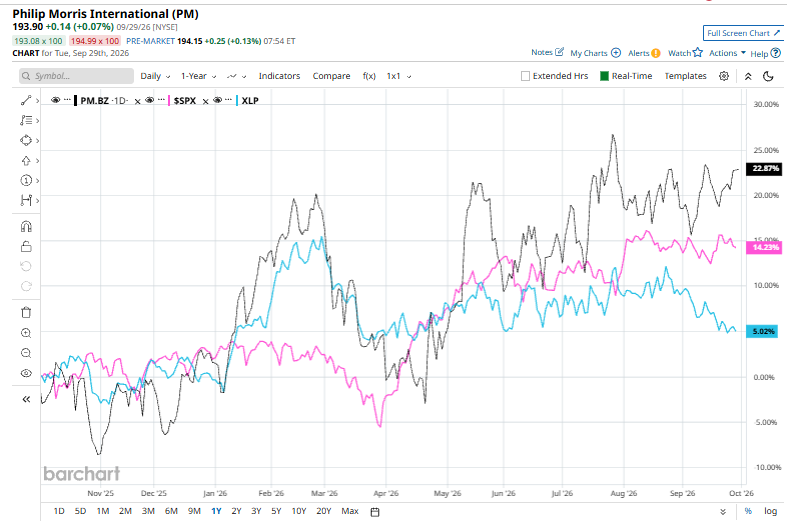
Philip Morris’ strong performance over the past year has been supported by its premium-priced products. The company’s robust financial results and continued growth in its smoke-free business have further boosted its performance. On July 22, Philip Morris reported second-quarter revenue of $11.2 billion, up 10.4% year over year, while smoke-free revenue increased 11.7% and accounted for about 42% of total sales. Adjusted EPS climbed 15.2%. More recently, the company raised its quarterly dividend by 8.8%, while FDA authorizations for additional ZYN products have further strengthened its smoke-free portfolio and have supported investor sentiment.
Analysts remain somewhat bullish on PM, with the stock carrying a consensus “Strong Buy” rating. Among the 14 analysts covering the stock, eight recommend a “Strong Buy,” two rate it a “Moderate Buy,” and four suggest a “Hold.” Meanwhile, the average price target of $207.86 implies potential upside of 7.2% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.