
How Postponed Projects At Trex Company (TREX) Has Changed Its Investment Story
- Trex Company recently reported that customers have been postponing outdoor projects, contributing to a 1.7% revenue decline over the last two years and raising fresh questions about capital efficiency.
- The same update sharpened focus on how Trex must balance higher capital intensity with long-term demand drivers, such as sustainability-focused decking and an aging installed base of decks in North America.
- We will examine how Trex Company's investment narrative holds up as customers defer projects and capital efficiency faces tougher investor scrutiny.
Compare Trex Company's setup with hand-picked peers facing similar demand pauses and capital intensity questions by scanning the 32 high quality undervalued stocks that still combine quality with disciplined reinvestment.
Trex Company Investment Narrative Recap
For Trex Company to be in your portfolio, you need to believe that postponed projects are a timing issue rather than a structural break in demand for composite decking. The key near term swing factor is whether repair and remodel activity stabilises enough for distributors and contractors to start working through delayed deck replacements and upgrades.
The biggest operational risk is that softer demand collides with higher capital intensity and keeps net margins under pressure. Customers deferring projects, combined with a 1.7% revenue decline over two years and an 11.19% 90 day share price pullback, keeps scrutiny squarely on how efficiently new capacity is used.
The most relevant recent update is management’s flag that customers are postponing outdoor projects and that revenue has declined 1.7% annually over the last two years. That comment goes straight to the health of Trex Company’s core repair and remodel channel and the timing of replacement demand from aging decks.
This same disclosure reframes catalysts and risks around execution. Higher capital expenditures for the Arkansas facility and other projects now have to earn their keep in a slower demand patch. An investor is essentially judging whether sustainable materials adoption and the long replacement cycle can offset weaker near term returns on capital.
Trex Company's narrative projects US$1.5b revenue and US$234.1m earnings by 2029. This implies 6.6% yearly revenue growth and an earnings increase of about US$56.7m from current earnings of US$177.4m.
Uncover why Trex Company's fair value indicates a 24% potential upside to its current price before other investors fully account for that difference.
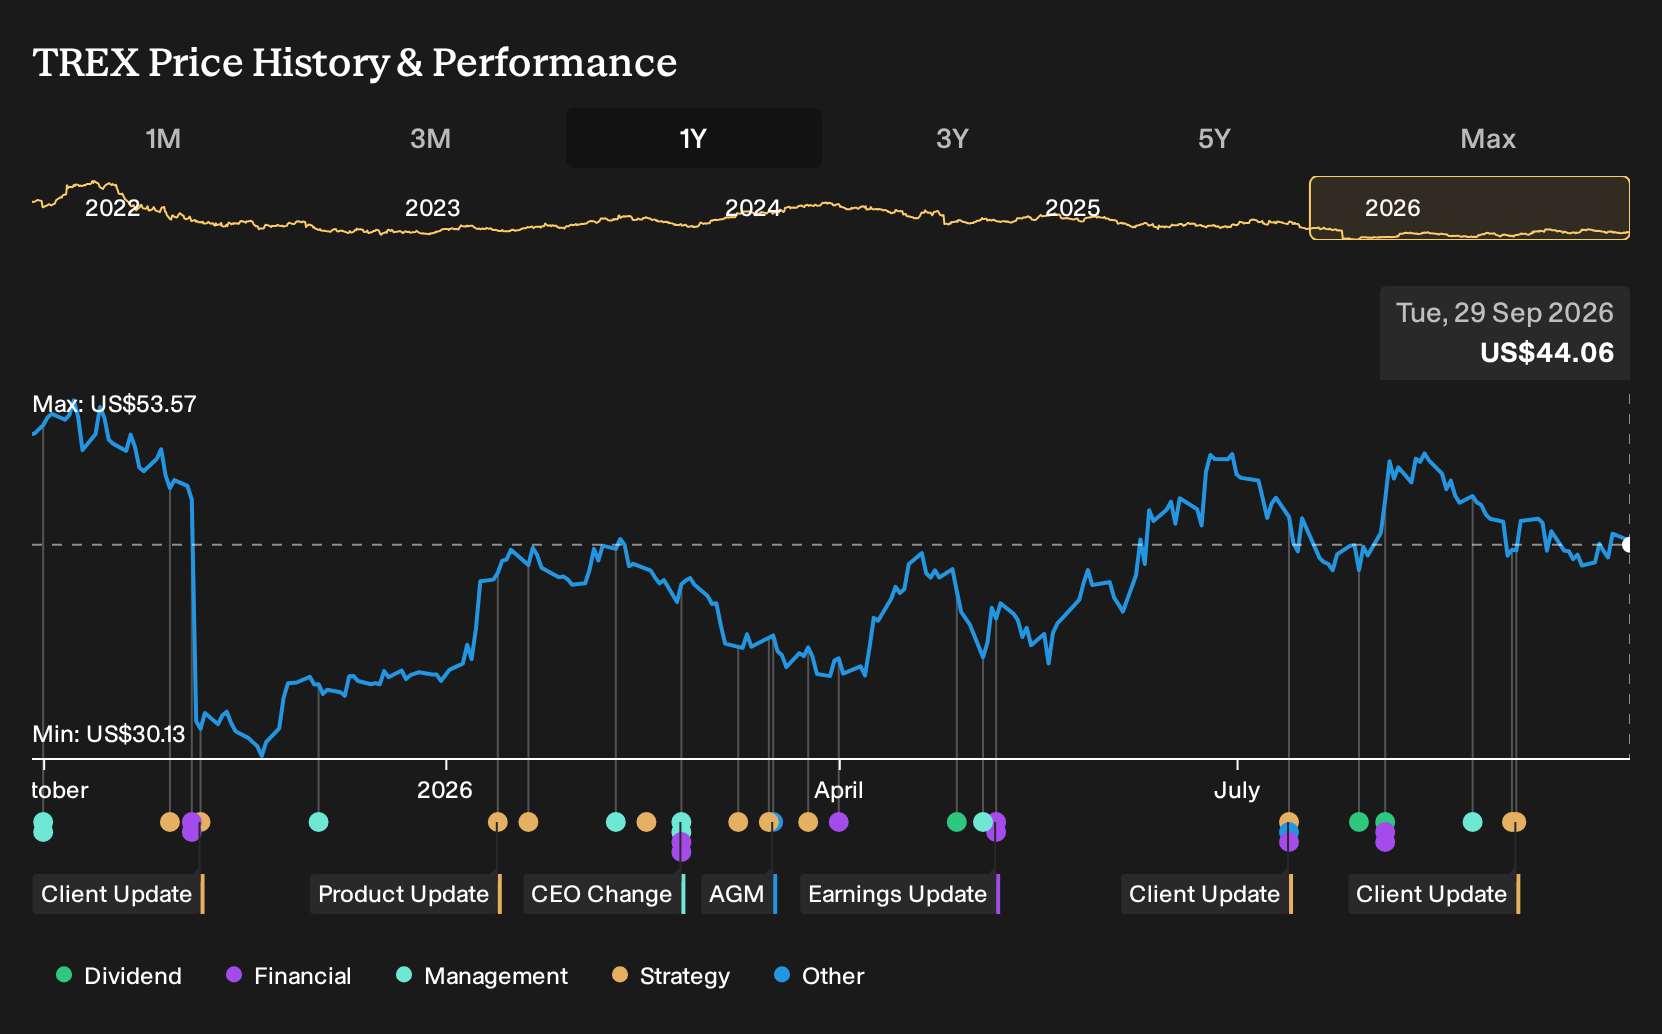
Exploring Other Perspectives
For Trex Company, the most bearish analysts fixate on overcapacity risk. They worry that weaker housing and renovation cycles could leave the new Arkansas facility underused. Those estimates still pencilled in about US$1.4b revenue and US$238.0m earnings by 2029. Your view might differ, and this fresh postponement news could shift those narratives again.
Explore 2 other Trex Company fair value estimates, including one that suggests it could be worth just $54.67!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research and going with your instincts.
- A great starting point for your Trex Company research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Trex Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trex Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Trex Company?
Once you have a view on Trex Company, it helps to benchmark that thesis against other opportunities that fit different risk, income, and balance sheet profiles. The Simply Wall St Screener lets you move from one stock story to a curated set of ideas that match what you care about most, whether that is stability, income, or finding businesses that the market may be underpricing.
- If capital preservation and smoother ride potential sit high on your list, start with a group of 32 resilient stocks with low risk scores that score well on risk metrics and financial resilience.
- If your priority is a stronger balance sheet profile, filter for companies in the list of solid balance sheet and fundamentals (25 results) to compare leverage, liquidity, and asset backing side by side.
- If you are hunting for under-the-radar opportunities, cast a wider net across 17 high quality undiscovered gems that pair solid fundamentals with lighter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com