
Southwest Gas Holdings (SWX) Looks Oversold After Mixed Results And Rate Case Progress
Southwest Gas Holdings (SWX) is back in focus after mixed quarterly results, fresh progress on rate cases in Arizona, Nevada, and California, and new commitments tied to its Great Basin 2028 expansion project.
The share price, near US$82.24, has drifted lower in recent weeks. The 30 day share price return is down 7.7% and the 90 day move is down 7.1%. However, the 1 year total shareholder return sits at 8.1% and the 3 year total shareholder return is 53.2%. This suggests that long term holders in Southwest Gas Holdings have still seen solid gains, while near term momentum has faded.
Spot potential rebounds across the utilities space by lining up Southwest Gas Holdings against our hand picked 32 high quality undervalued stocks.Southwest Gas Holdings now trades well below the average analyst target, even though its own fair value estimate suggests far less of a bargain. Is the recent pullback simple mispricing, or is it a clear warning sign about valuation risk?
Most Popular Narrative: 19.7% Undervalued
Analysts put Southwest Gas Holdings' fair value near $102.43 a share, which sits well above the latest close around $82.24. That gap rests on a set of growth, margin, and regulatory assumptions that investors need to understand before treating the recent pullback as a discount.
Robust customer growth facilitated by ongoing population and economic expansion in the Southwest, with 40,000 new meter connections in the last 12 months, suggests extended demand for natural gas in core service territories, directly underpinning long-term revenue and earnings growth.
Accelerated infrastructure investment opportunities, exemplified by the Great Basin pipeline expansion project with potential $1.2 to $1.6 billion in new capital expenditures, are expected to drive significant rate base growth, supporting higher future regulated revenue and earnings.
See why 4 investors see Southwest Gas Holdings as 20% undervalued.
Result: Fair Value of $102.43 (UNDERVALUED)
Still, the bullish story around Southwest Gas Holdings can be knocked off course if decarbonization policies curb long term gas demand or if major projects suffer delays and cost overruns.
Find out about the key risks to this Southwest Gas Holdings narrative.
Another Take On Southwest Gas Holdings' Valuation
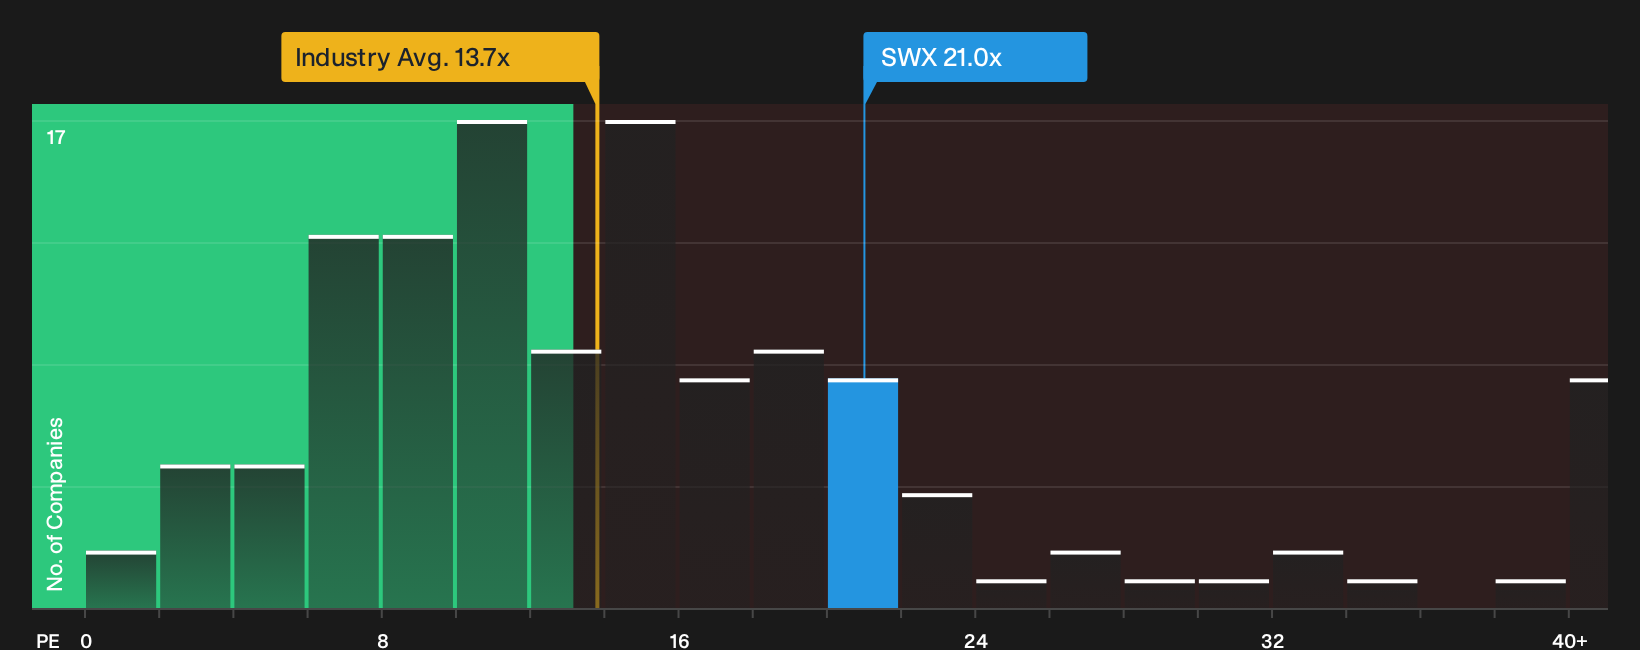
The analyst narrative paints Southwest Gas Holdings as about 20% undervalued, yet the market is already paying a rich P/E of roughly 21x. That is higher than both the global gas utilities average of 13.8x and peer levels around 16.1x, even though the fair ratio sits closer to 21.3x. This raises the question of whether investors have a cushion or a thin margin for error if growth or regulation disappoints.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Southwest Gas Holdings can feel uncomfortable, so use that urgency to your advantage and pressure test the story for yourself by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Southwest Gas Holdings?
If Southwest Gas Holdings has sharpened your focus on valuation and risk, do not stop there. Use screener driven shortlists to quickly surface fresh, high conviction ideas that might otherwise never hit your radar.
- Target potential value candidates that pair quality fundamentals with attractive pricing by reviewing our hand picked 32 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by scanning a list of solid balance sheet and fundamentals (25 results) before the next bout of volatility surprises you.
- Get ahead of the crowd by filtering for 17 high quality undiscovered gems that combine resilient financials with under the radar profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com