
Will Community Microgrids Change PG&E (PCG) Stock Narrative
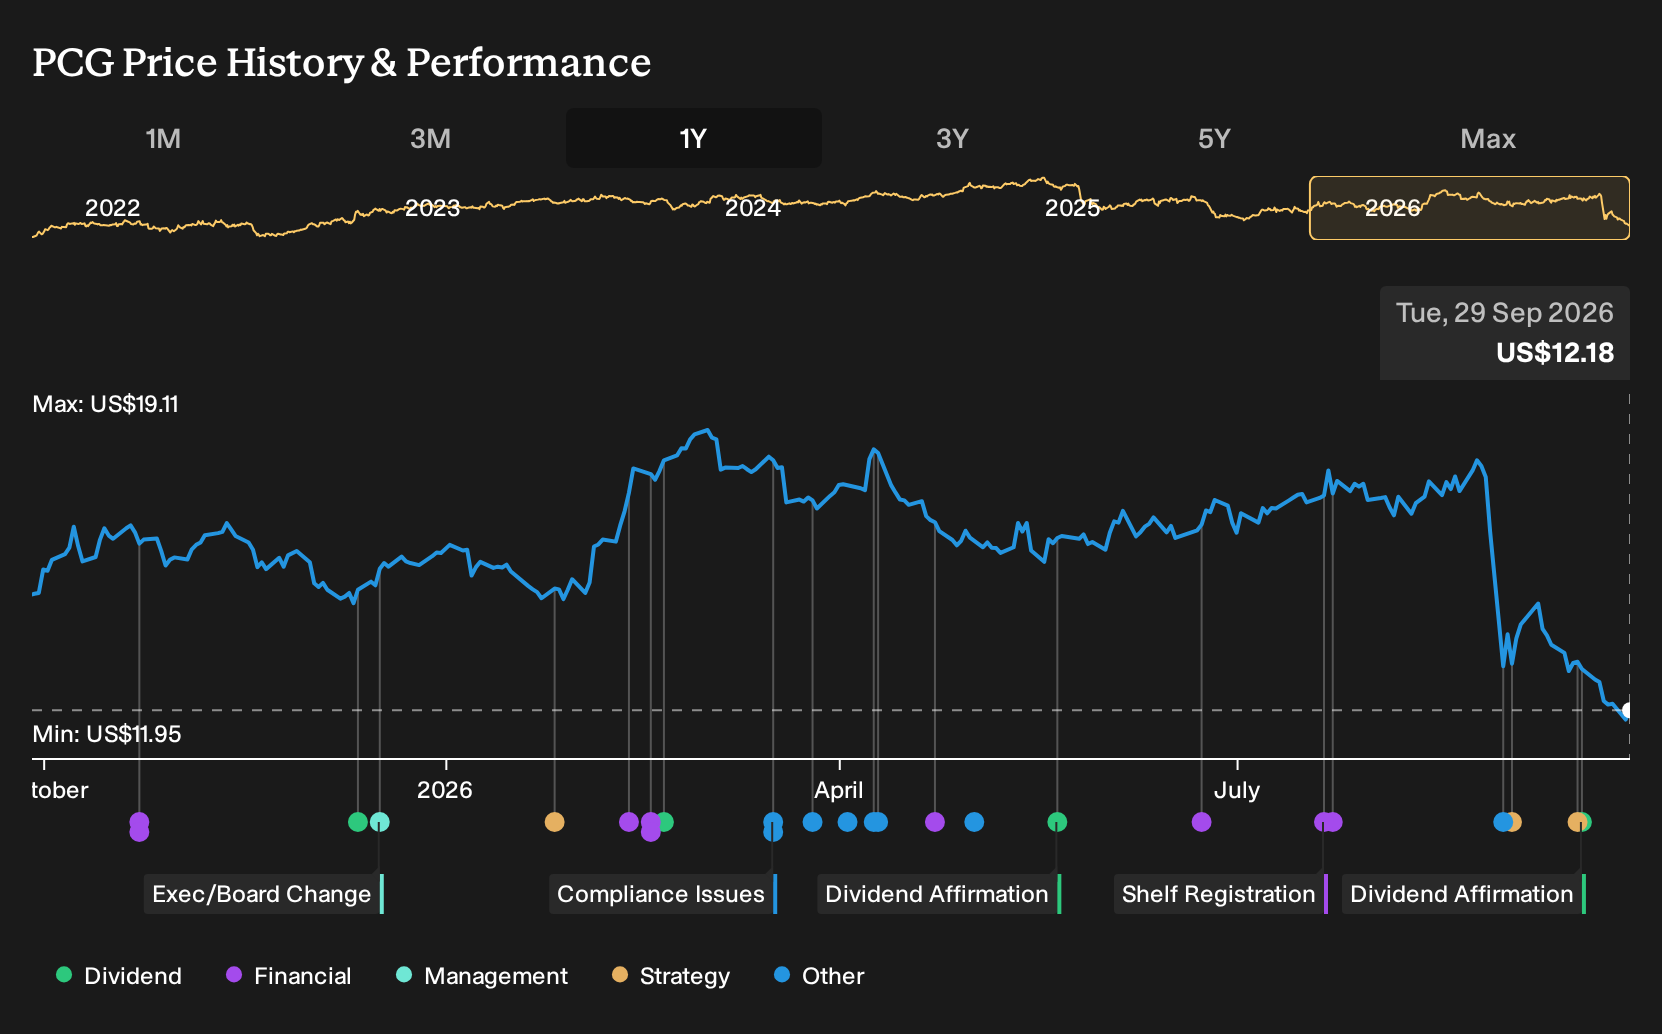
- PG&E declared a regular third quarter 2026 cash dividend of $0.05 per share and reported over $73 million in authorized community microgrid investments across Northern and Central California, including six new projects and progress on earlier awards.
- The expansion of PG&E funded community microgrids, with projects like the Pescadero solar and battery system, points to rising capital commitments toward local resilience infrastructure that can influence long term cost structure and service reliability.
- We will now look at how PG&E's expanded community microgrid investments could reshape the investment narrative around grid resilience and capital deployment.
PG&E Investment Narrative Recap
To own PG&E, you need to believe the utility can turn heavy grid and wildfire spending into a predictable, regulated earnings stream while keeping political and legal risk in check. The latest dividend affirmation at $0.05 per share signals that management is keeping a measured capital return profile as it funds large projects.
In the short term, the key swing factor is still how regulators treat cost recovery for resilience and wildfire work. The new microgrid commitments support PG&E's operational story but do not fundamentally change that near-term catalyst. Wildfire liability, affordability pressure, and interest coverage remain the biggest watchpoints.
The community microgrid expansion is the headline operational move. More than $73 million in authorized projects and a Pescadero system sized for roughly 1.5 megawatts of solar and 2 megawatts of storage give PG&E concrete assets tied to resilience and reliability goals that regulators and communities are focused on.
Those investments sit right next to the main catalysts that analysts have been watching. Grid modernization and resilience spending, if judged prudent, can support rate base growth, while community-level microgrids may help manage outage risk that feeds wildfire concerns. The regular dividend decision then becomes one more data point in how PG&E balances funding these projects with shareholder payouts.
PG&E's analyst narrative points to revenue of $28.6b and earnings of $4.5b by 2029, which implies 3.4% yearly revenue growth and an earnings increase of about $1.4b from current earnings of $3.1b.
Uncover why PG&E's fair value indicates a 61% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For PG&E, the biggest swing factor in the more optimistic narrative is the US$73b capital plan. The most bullish analysts were modeling revenue of US$30.3b and earnings of US$4.9b by 2029 before this dividend and microgrid news. You can read those forecasts as a high bar that might shift as resilience projects scale.
Explore 2 other PG&E fair value estimates, including one that suggests the potential for as much as 61% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your PG&E research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for PG&E. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PG&E's overall financial health at a glance.
Looking For More Investment Ideas Beyond PG&E?
If you want to put PG&E in context and widen your opportunity set, the Simply Wall St Screener can help you quickly surface other stocks that fit specific return and risk profiles.
- If income matters most to you, consider companies in our list of dependable payers by starting with 6 dividend fortresses.
- If you care more about durable balance sheets and resilience through different cycles, start with the list of solid balance sheet and fundamentals (25 results).
- If you are hunting for lesser known opportunities with strong fundamentals, take a look at the 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com