
What MPLX (MPLX)’s Higher Payout Plan Means For Shareholders
- MPLX has laid out plans for heavier capital spending alongside a target of 12.5% annual distribution growth through 2027. This increases the earnings burden needed to support both richer payouts and an expanding project slate.
- This combination of higher distributions and larger project budgets puts MPLX’s cash generation, funding mix, and execution discipline into sharper focus for anyone assessing the durability of its current payout profile.
- We will now assess how MPLX’s push for 12.5% annual distribution growth could reshape the investment narrative investors have been using so far.
Compare MPLX’s richer payout plans with peers that are pursuing similar income strategies by scanning our hand picked group of 6 dividend fortresses for context on yield and balance sheet strength.
MPLX Investment Narrative Recap
To own MPLX, you need to be comfortable with a midstream partnership whose fortunes are tied to U.S. oil and gas activity, especially in the Permian and Delaware. The core belief is that gathering, processing, and pipeline volumes can remain strong enough for the current asset base and recent acquisitions to support earnings and cash generation.
The near term swing factor is execution on the large slate of gas and NGL projects entering service through 2026, and how quickly those assets fill. The biggest risk is that higher capital spending and any weaker basin activity leave utilization and returns below expectations, which would strain coverage of MPLX’s distribution plans.
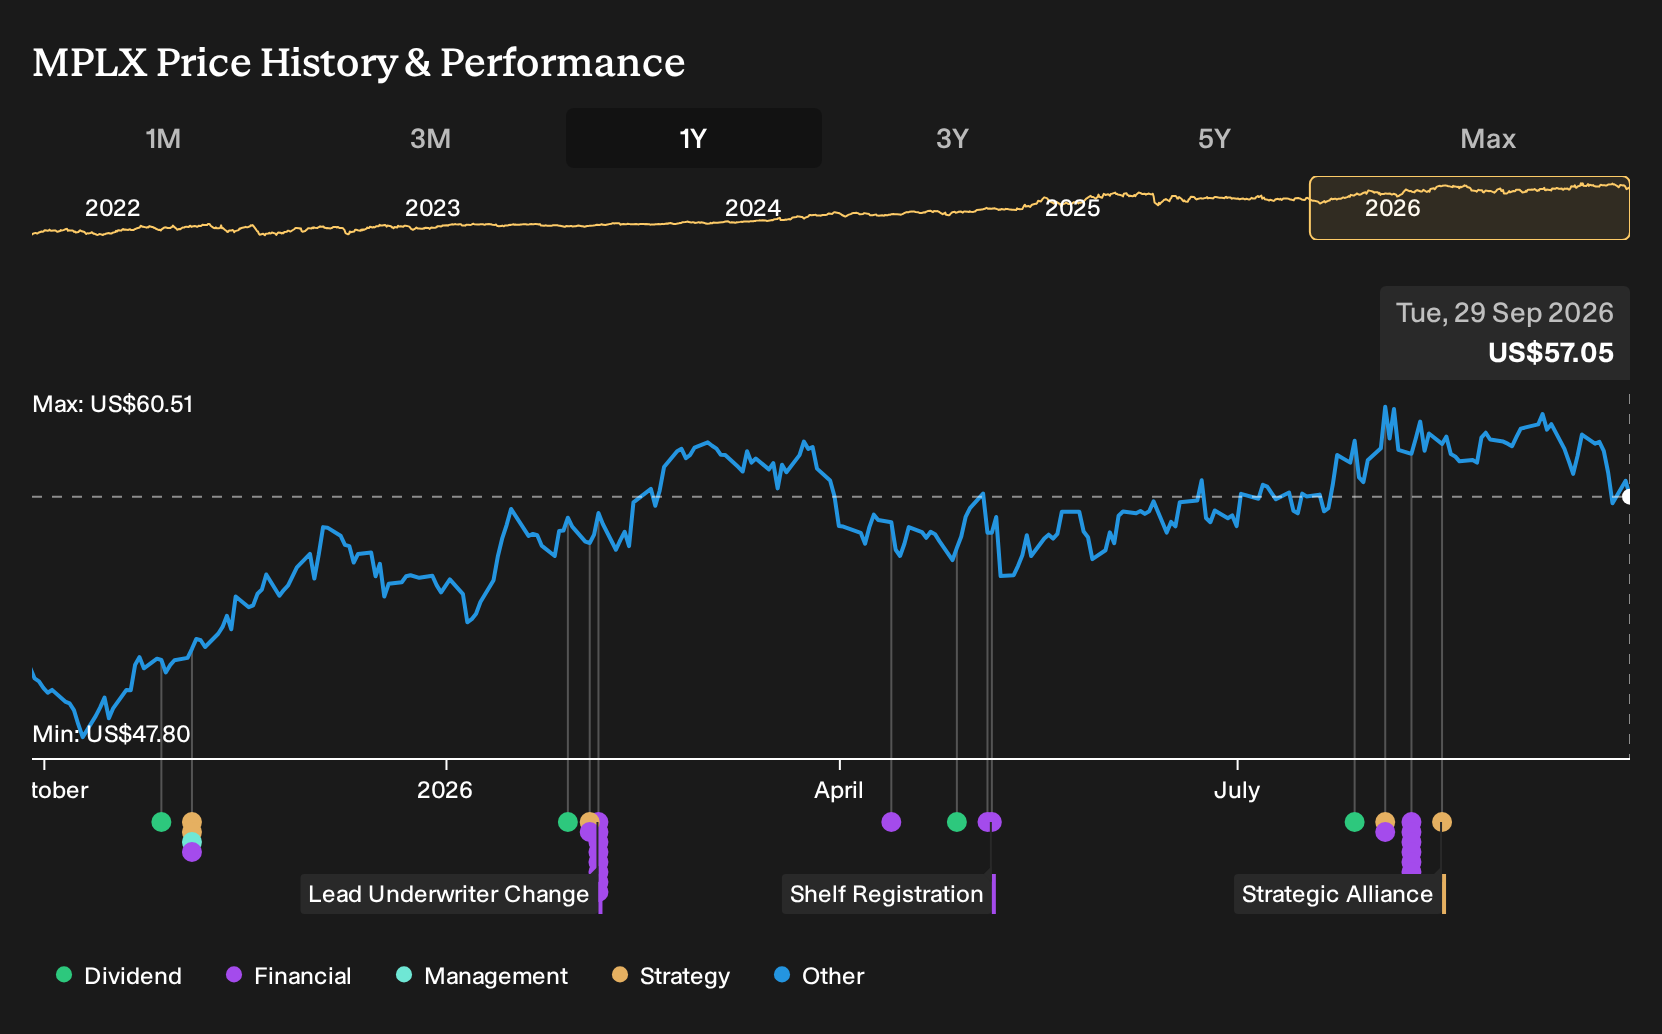
The clearest announcement tied to the current debate is management’s target of 12.5% annual distribution growth through 2027 alongside heavier capital spending, including about US$2.9b planned for 2026. That combination means MPLX would rely more heavily on consistent project performance and stable financing conditions to fund both payouts and new infrastructure.
For you, the key question is whether throughput growth from assets like Northwind Midstream, BANGL, and new processing plants can keep cash flows ahead of higher distributions and debt costs. If large projects underperform or hedging results remain weak, the current payout profile and expansion tempo could feel tight against the balance sheet.
MPLX's current analyst narrative points to about US$15.8b in revenue and US$5.6b in earnings by 2029. That path assumes revenue expanding at roughly 9.5% per year and earnings rising by about US$0.9b from US$4.7b today to reach those 2029 consensus estimates.
Uncover why MPLX's fair value indicates a 10% potential upside to its current price that could close faster than many income investors expect.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$62.85 and US$130.34, which places MPLX above some views and well below others. That kind of spread often reflects different opinions on Permian and Delaware volume resilience, so treat it as a cue to explore several contrasting viewpoints before relying on any single narrative.
Explore 2 other MPLX fair value estimates, including one that suggests as much as 128% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your MPLX research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MPLX. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MPLX's overall financial health at a glance.
Looking for more investment ideas beyond MPLX?
If the MPLX story has sharpened your thinking on income, risk, and balance sheet strength, it can help to stress test that framework against a wider opportunity set using the Simply Wall St Screener.
- If capital preservation matters most to you, start with 32 resilient stocks with low risk scores that aim to pair steadier fundamentals with lower risk profiles.
- For investors hunting for potential mispricing, scan 32 high quality undervalued stocks that combine solid cash generation with supportive balance sheets.
- If you want to uncover ideas that are not widely followed, review 17 high quality undiscovered gems that still show strong underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com