
3 Rate Sensitive US Growth Stocks to Watch as Inflation Cools
Inflation just surprised on the softer side, PCE came in below forecasts, Treasury yields eased and suddenly rate-sensitive growth stocks are back in focus. When borrowing costs stop climbing so quickly, investors often reprice anything tied to future cash flows, and the moves can be sharp. This article walks through three U.S. large-cap growth stocks exposed to the latest inflation and Fed expectations shift, and explains why their reaction could matter for your portfolio.
The three stocks covered below are just a first cut, and the full screen surfaced 35 more U.S. large-cap growth companies across tech, internet, software and semiconductors with equally compelling rate-sensitive narratives that are not unpacked here. To go straight to the full list and analyze which ideas best fit your own view on inflation and yields, head into the U.S. Large-Cap Rate-Sensitive Growth Stocks screener.
Semtech (SMTC)
Semtech fits the screener brief almost perfectly, sitting at the intersection of high beta semiconductors and IoT connectivity, where lower yields often give long-term projects more breathing room and where small shifts in funding costs can quickly alter how investors price its future cash flows.
Semtech is a fabless chip and IoT connectivity supplier with three roughly similar sized engines: Signal Integrity at about US$401 million, Analog Mixed Signal and Wireless at around US$409 million, and IoT Systems and Connectivity close to US$365 million. The stock sits near US$16.8b in market value.
"Heavy dependence on hyperscaler AI data center spending leaves Semtech exposed if large customers slow network upgrades."
What happens to Semtech’s earnings power if a single assumption about how quickly high speed connectivity projects ramp actually shifts just a little?
That makes the next step clear: read the full narrative for Semtech to see how Semtech’s AI data center exposure could evolve if connectivity demand accelerates again.

Ciena (CIEN)
Ciena gives you exposure to rate sensitive, large cap communications technology, where long lived network projects and AI heavy data traffic can make changes in borrowing costs and discount rates matter a lot for how future earnings get priced today.
Ciena provides networking platforms, software and services for global carriers and cloud providers. Most revenue comes from Networking Platforms at about US$4.8b, followed by Global Services near US$714 million, Platform Software and Services around US$379 million, and Blue Planet at roughly US$101 million. The stock is valued around US$48.8b.
"Major cloud providers and a new wave of neo-scalers are aggressively investing in high-capacity, low-latency optical networking infrastructure to support AI workloads, driving multiyear, global network buildouts that should significantly expand Ciena's addressable market and underpin sustained, above-trend revenue growth."
What happens to that growth path if a single assumption about how quickly those AI heavy networks turn into higher margin contracts proves too optimistic?
That hinge point is exactly where the full narrative for Ciena shows how Ciena could still convert accelerating AI traffic into pricing power, mix shift, and more resilient cash generation.

Jabil (JBL)
Jabil plugs into this rate-sensitive growth theme as a large-cap manufacturing partner to many of the same hardware and electronics projects that benefit when borrowing costs ease and customer capex plans look more attractive.
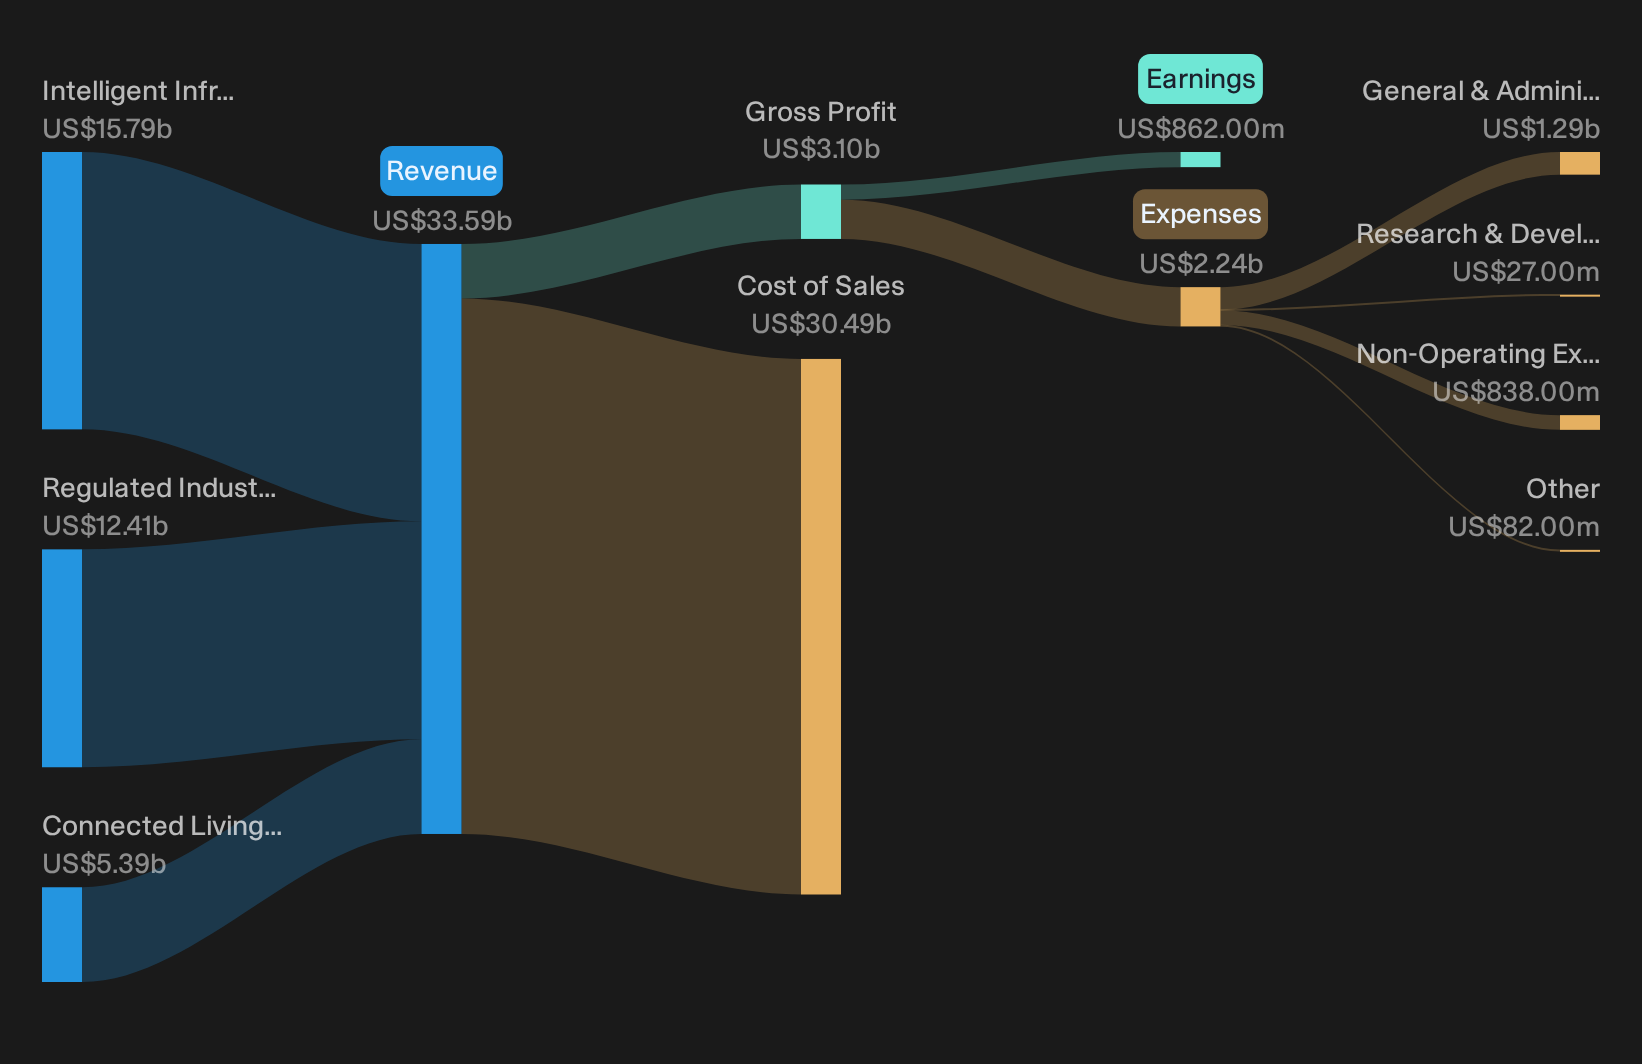
Jabil is an engineering and manufacturing specialist for complex electronics and hardware across 5G, cloud, healthcare, automotive and connected devices, with around US$12.4b from Regulated Industries, US$15.8b from Intelligent Infrastructure, and US$5.4b from Connected Living and Digital Commerce, and a market value near US$33.4b.
"Jabil's acquisition of Pharmaceutics International, Inc. opens access to a $20 billion market, suggesting potential revenue growth and improved margins by expanding its pharmaceutical solutions offering."
What happens to Jabil’s margin story if a single assumption about how quickly customers shift complex manufacturing programs to its platform proves too cautious?
If that shift happens faster than expected, read the full narrative for Jabil to see how Jabil’s margins, cash generation and valuation story could accelerate further.
Seeking Alternatives Before Momentum Runs
Fresh opportunities do not stay quiet for long. Breakout stories get spotted, momentum builds, and prices start flying. Screen under the radar for now, then act early to establish a position.
- Track cash rich compounding stories before they get crowded by using the curated 32 high quality undervalued stocks while valuation gaps and quality mismatches still matter.
- Ride the next wave of automation as capital shifts toward precision hardware by scanning the hand picked 93 robotics and automation stocks while prices have not fully caught the trend.
- Position ahead of potential rate or currency shocks by reviewing a filtered 36 elite gold producer stocks while market attention is still focused elsewhere.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com