
3 Energy Stocks Retail Investors May Revisit As UK Gas Prices Threaten A £2,000 Cap
Energy bills in the UK look set to climb again, with a forecast 16% rise in the price cap to around £2,000 from January, linked to Iran war related gas supply disruption. That kind of shock can punish households but reshape the opportunity set for investors. This article walks through 3 UK and European listed natural gas and integrated energy stocks exposed to this news and explains how that could influence their investment appeal.
The stocks covered below are just a sample, and the full screen surfaced 15 more UK and European listed natural gas producers and integrated energy groups with equally compelling narratives that are not included in this article. To identify and analyze the highest conviction opportunities that fit this theme, go straight to the UK and European-listed natural gas producers and integrated energy companies screener.
Yü Group (AIM:YU.)
Yü Group is a pure UK business energy supplier, so any swing in wholesale gas and power pricing ripples straight through its retail economics. That direct link to the screener theme is what makes the growth story worth a closer look.
Yü Group supplies electricity, gas, water and related metering and software services to UK businesses, generating £764.8 million of revenue in the United Kingdom, and the stock currently carries a market value of about £282.4 million.
Management is targeting a significant increase in market share, while expanding cross-selling opportunities across electricity, gas, water and engineering services.
The real swing factor is how one shift in future UK power and gas pricing filters through supply margins and ultimately shapes earnings quality.
That pricing risk is exactly what the full narrative for Yü Group unpacks in detail, including how tariff shifts, hedging choices and contract mix could be accelerating or masking Yü Group’s potential.

Gulf Keystone Petroleum (LSE:GKP)
Gulf Keystone Petroleum is an upstream oil and gas producer in the Kurdistan Region of Iraq, so its fortunes are closely tied to global oil and gas benchmarks that sit behind this screener theme.
Gulf Keystone Petroleum focuses on exploring and producing oil and gas from the Shaikan Field in Kurdistan, earning about US$193 million from exploration and production activities. The company currently has a market value of roughly £439 million.
The appeal for investors is not just that Gulf Keystone Petroleum is linked to higher global energy benchmarks. It is also that its core asset could convert any improvement in market pricing into much stronger earnings power if the operating backdrop cooperates.
Progress toward restarting oil exports through the Iraq-Turkey pipeline presents the potential for access to higher international prices, operational leverage, recovery of outstanding receivables, and greater commercial stability, all of which could meaningfully boost revenue and earnings.
What happens if one constraint on production volumes and sales terms finally eases may matter more for margins here than any short term oil price move.
When that bottleneck finally shifts, the full narrative for Gulf Keystone Petroleum shows how Gulf Keystone Petroleum’s pricing, volumes and political risk could be accelerating or quietly capping the upside.

Jadestone Energy (AIM:JSE)
Jadestone Energy gives you pure upstream exposure to oil and gas pricing, and its Asia-Pacific focus fits cleanly with a screener built around producers that earn their keep directly from tight hydrocarbon markets.
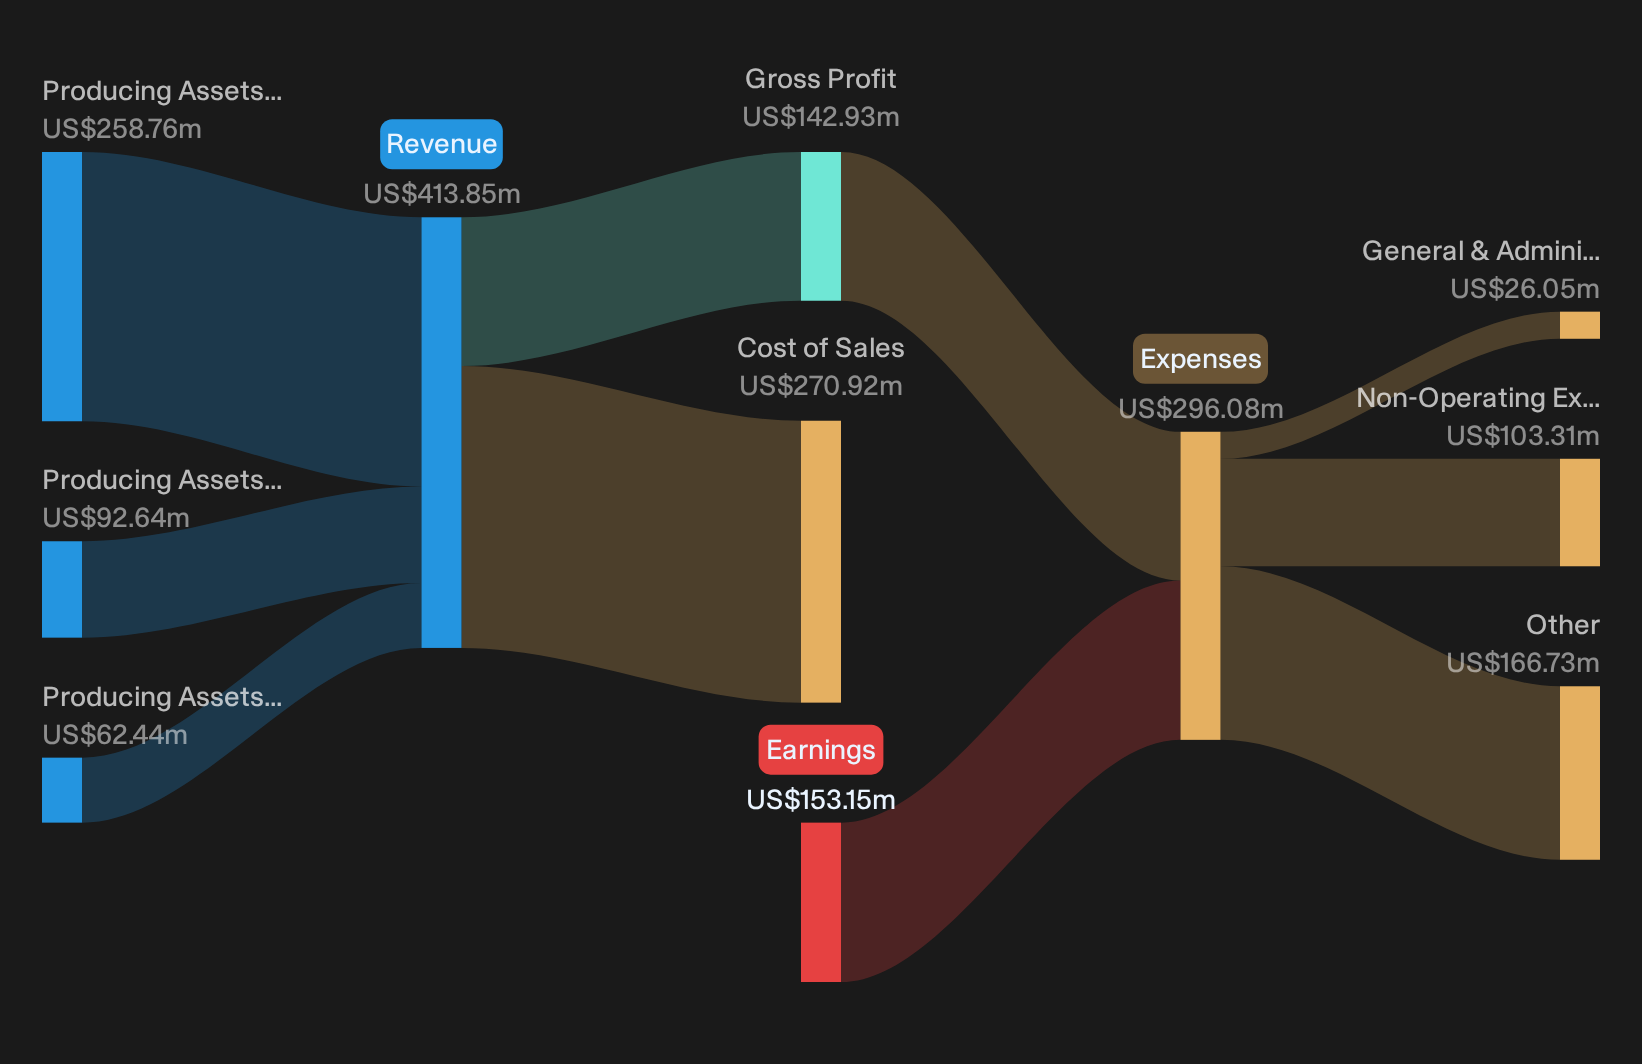
Jadestone Energy develops and produces oil and gas across Australia, Malaysia, Indonesia and Vietnam, anchored by the Akatara gas and liquids field in Indonesia. It generated about US$259 million from Australian assets, US$62 million from Malaysia and US$93 million from Indonesia, and the stock is valued at roughly £210 million.
Jadestone's disciplined focus on acquiring low decline, producing Asia-Pacific assets has been a defining feature of its strategy and reflects management's view of opportunities in upstream oil and gas.
The real swing factor for Jadestone Energy is what happens if one unseen pressure on future cash generation breaks in its favour.
If that pressure eases in Jadestone Energy's favour, the full narrative for Jadestone Energy examines whether cash generation is quietly accelerating or still held back by less obvious risks.
Seeking Alternatives Before The Crowd?
Fresh ideas move fast. By the time most investors spot a breakout, the best entry point can be gone. Use these curated lists while it matters and aim to get in earlier in the cycle.
- Spot resilient cash generators that may hold up when sentiment turns by scanning the list of solid balance sheet and fundamentals (10 results), which is tuned to financial strength and quality fundamentals.
- Follow structural themes in automation and industry 4.0 by tracking companies inside the 93 robotics and automation stocks before institutional money potentially chases momentum.
- Focus on infrastructure linked to long term electrification developments using the 39 power grid technology and infrastructure stocks, curated for businesses involved in grid upgrades, reliability and capacity expansion.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com