
Is Amgen (AMGN) Undervalued Following Its Phase 3 Sjögren's Disease Trial Update?
Amgen (AMGN) is back in focus after reporting positive topline Phase 3 data from its OASIZ 301 trial of dazodalibep in Sjögren's disease, which has sharpened attention on its autoimmune drug pipeline.
Amgen’s recent autoimmune update lands against a backdrop of strong momentum, with the share price up 17.2% over the past 90 days and 29.3% year to date. The 1 year total shareholder return of 54.3% points to gains that extend beyond short term trading reactions.
See how Amgen’s autoimmune progress compares by lining it up against 35 healthcare AI stocks that are shaping the next wave of data driven drug development.
Amgen’s surge now raises a sharper issue for you as an investor. Has the Sjögren’s win simply flipped sentiment, or is the move better grounded in what you are paying for the underlying business?
Most Popular Narrative: 18% Overvalued
Amgen’s last close at $423.64 sits well above the $359.98 fair value in the most followed narrative, which frames the recent autoimmune excitement as only part of a tougher, obesity focused story.
The "Amgen 2027 Bull Case" relies on a classic top-line fallacy: assuming that macro obesity market growth and FDA's CNPV (Commissioner’s National Priority Voucher) tailwinds will automatically trigger a re-rating.
Here is the cold, data-driven reality:
1. CNPV solves regulatory speed, not the manufacturing bottleneck. Amgen lacks the massive, domestic GLP-1 supply chain infrastructure that Lilly and Novo command. Fast-tracked approval without scale-up capacity only accelerates market-share caps.
2. The consensus ignores the regulatory friction. The CNPV pilot program is facing severe legal durability and structural transparency questions in mid-2026. Betting a 2027 thesis on an unstable, non-statutory policy is a high-risk gamble.
3. Competitors are already using the exact same playbook. Novo Nordisk already secured its Wegovy HD approval via CNPV in March 2026. Amgen is a latecomer trying to enter a crowded arena where the incumbents already hold the fast-track tokens.
4. The timeline mismatch is real. MariTide's commercial ramp-up will take years post-launch. Meanwhile, Amgen’s high-margin legacy moats (Prolia and Enbrel) are already eroding at a brutal -30%+ YoY clip right now.
Amgen is priced for flawless execution, leaving zero margin of safety for the structural vacuum underneath its valuation. AMGN is a speculative premium hiding a legacy erosion.
See why 6 investors see Amgen as 18% overvalued.
Result: Fair Value of $359.98 (OVERVALUED)
Still, if Amgen executes on obesity manufacturing capacity or stabilises key franchises faster than expected, this bearish narrative could lose its edge.
Find out about the key risks to this Amgen narrative.
Another View on Amgen’s Valuation
Where the most followed Amgen narrative leans on a $359.98 fair value, the SWS DCF model comes out in a very different place. On that framework, the shares at $423.64 are seen as trading below an estimated future cash flow value of $672.77, which points to an undervalued profile instead.
That kind of gap cuts both ways for you as an investor. It can signal a cushion if Amgen’s cash generation holds up, or it can highlight how sensitive the story is to any reset in assumptions. The real question is which lens you trust more when the next piece of news hits.
Look into how the SWS DCF model arrives at its fair value.
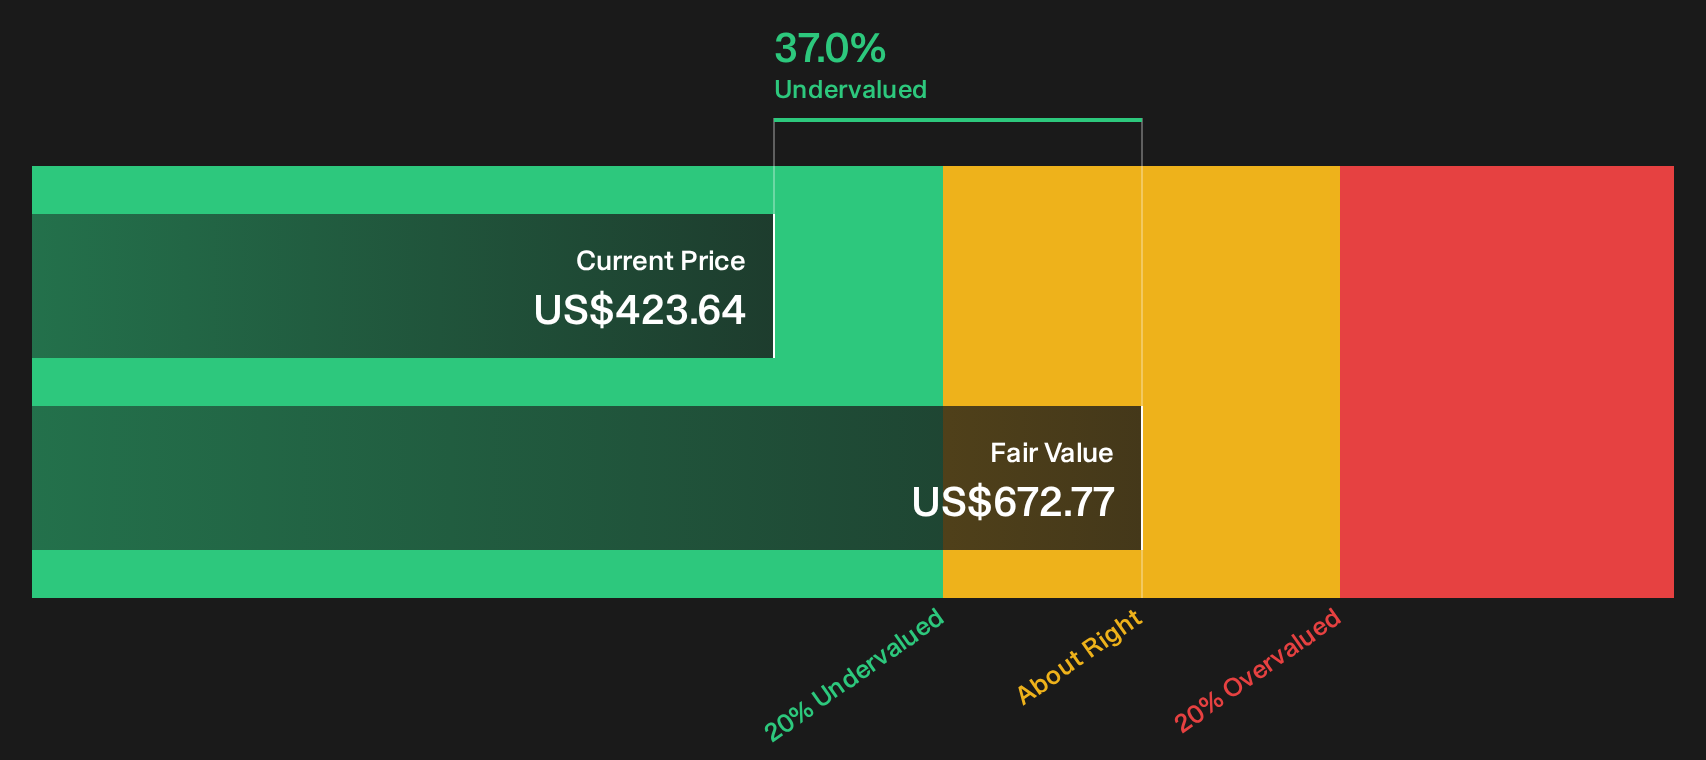
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Amgen for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Amgen is sharply split. Your edge comes from checking the numbers yourself and deciding quickly where you stand on the trade off between upside and downside. To see that balance laid out clearly, review the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Amgen?
If Amgen has your attention, use that momentum. Broaden your watchlist with other opportunities that fit your risk, return, and income goals before they move without you.
- Target stronger upside potential by scanning for quality companies trading below their estimated worth through the 32 high quality undervalued stocks.
- Strengthen your portfolio’s resilience by focusing on companies with robust finances using the list of solid balance sheet and fundamentals (25 results).
- Add income power by hunting for reliable high yield opportunities with the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com