
Genius Sports (GENI) Launches Prediction.com As Reaffirmed Outlook Keeps Fair Value In View
Genius Sports (GENI) moved into focus after confirming its 2026 revenue outlook at US$1.005b to US$1.025b. The reaffirmed guidance followed the recent launch of its Prediction.com consumer platform.
Those launches and reaffirmed targets come against a mixed trading backdrop, with the share price down 23.07% over 30 days and 42.76% year to date, while the 3-year total shareholder return is positive at 25.66%. However, the 1-year total shareholder return is down 50.16%, hinting that confidence around Genius Sports is rebuilding from a weaker recent base rather than surging.
Scan how Genius Sports fits among other sports, betting and media-focused plays by reviewing a curated list of 17 high quality undiscovered gems before these stories become crowded trades.
The recent slide in Genius Sports looks less like a verdict on its data and consumer tools and more like a reset in mood. The valuation work now is figuring out which story the current price reflects.
Most Popular Narrative: 43% Undervalued
Against a last close of $6.17, the most followed narrative points to a fair value for Genius Sports of $10.83. This frames the current share price as deeply discounted and puts the focus on whether the business can deliver on its long-term plan.
Rapid adoption of interactive, real-time sports content and next-gen fan engagement technologies (e.g. BetVision, GeniusIQ, augmented broadcast, AI-driven analytics) is driving deeper integration with leagues and media partners, creating high-margin, recurring revenue streams and supporting long-term net margin expansion through product differentiation.
See why 25 investors see Genius Sports as 43% undervalued.
This narrative uses a 10.19% discount rate and a forward-looking view on Genius Sports. It combines analyst assumptions on revenue growth, margin improvement, and future earnings to reach that $10.83 figure. It rests on forecasts that annual revenue expansion could run in the high 20% range and that the firm could shift from a loss of $181.6 million today toward positive earnings over the coming years, while still carrying the execution and regulatory risks outlined in the same storyline.
For readers comparing this to the current market price, the gap between $6.17 and the narrative fair value highlights how much faith is being placed in Prediction.com, data rights deals, and higher margin media tools developing into durable, cash-generative businesses for Genius Sports.
Result: Fair Value of $10.83 (UNDERVALUED)
Still, the Genius Sports story can break if key data rights are renewed on tougher terms or if rising tech spend fails to translate into sustainable free cash flow.
Find out about the key risks to this Genius Sports narrative.
Another View: What Multiples Say About Genius Sports
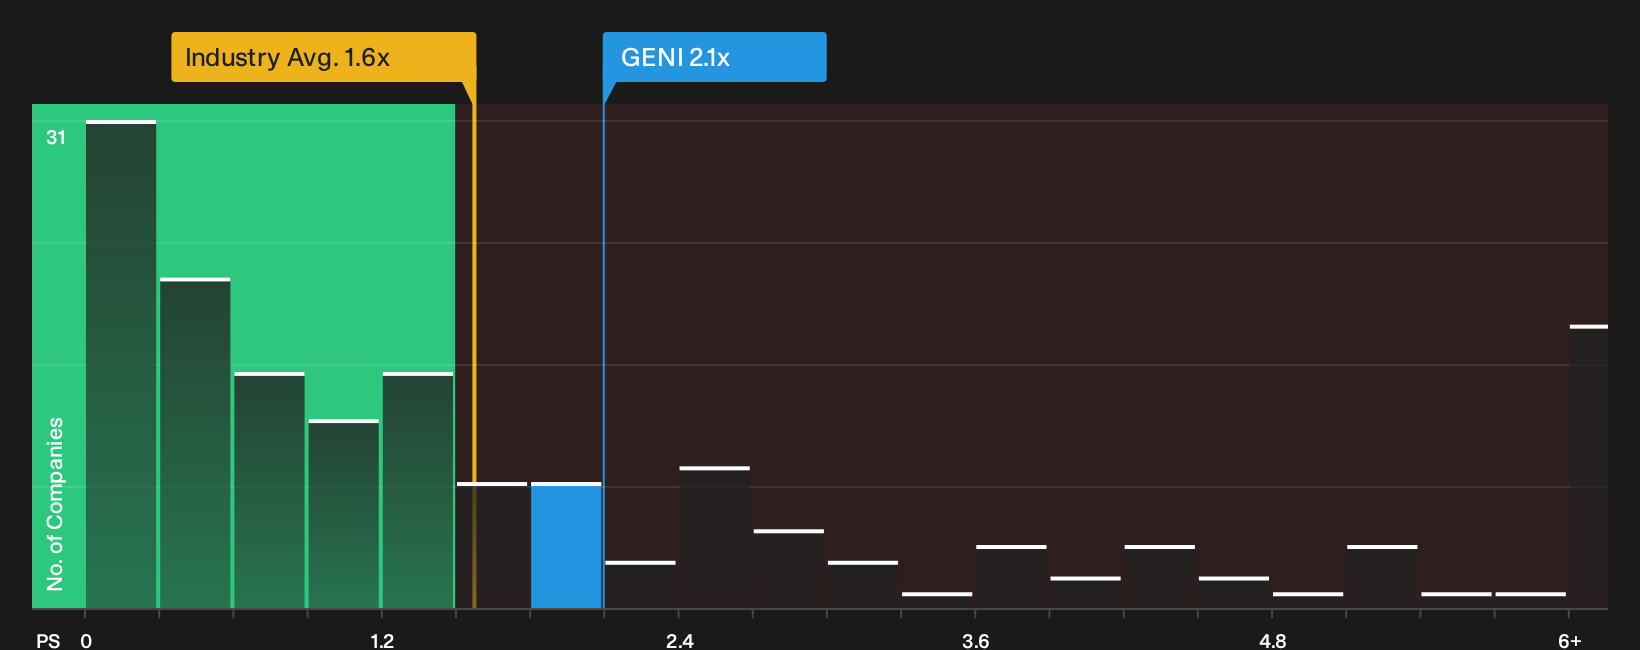
The DCF work presents Genius Sports as heavily undervalued, with the share price at $6.17 compared with an estimated future cash flow value of $30.38. The picture looks less generous when you switch to a simple sales multiple, where GENI trades on a P/S of 2.1x.
That ratio is higher than the US Hospitality sector on 1.6x and above the peer average on 1.3x, and also above the fair ratio estimate of 1.8x. In practice, that means the market is already paying a premium to current fundamentals. The real question is which story you place more weight on: the cash flow model, or the market based multiple view.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Genius Sports so far. If you want to move fast and build your own view using the same inputs, start with the 2 key rewards and 2 important warning signs.
Looking for more Genius Sports style opportunities?
If Genius Sports has your attention, do not stop here. Fresh ideas are often found where fewer investors are currently looking.
- Target potential mispricing by scanning a curated set of 32 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into the price.
- Prioritize resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you focus on companies with steadier financial footing when conditions change.
- Push beyond the usual tickers by hunting through a 32 resilient stocks with low risk scores that filters for calmer price swings without abandoning quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com