
Infineon Technologies (XTRA:IFX) Could Be 18% Overvalued On Its Current Narrative
Infineon Technologies (XTRA:IFX) is back in the spotlight after confirming multiple appearances focused on AI infrastructure, including Data Centre World Asia on September 29 and the AI & Technology Virtual Investor Conference on October 1.
Those AI data centre appearances come after a volatile stretch for Infineon Technologies, with the share price up 4.83% on the day to €59.3 and a 30 day share price return of 3.89%, but a 90 day share price decline of 23.88%. Total shareholder return sits at 79.99% over one year and 95.66% over three years, which points to strong longer term momentum despite recent pressure.
Scan how Infineon Technologies compares with other AI infrastructure plays by reviewing our curated list of 88 AI infrastructure stocks shaping the data centre build out story.
After a sharp pullback followed by this latest rebound, the Infineon Technologies share price already reflects a lot of AI enthusiasm. The real question is how much upside the current valuation still leaves on the table.
Most Popular Narrative: 18% Overvalued
The most followed valuation narrative pegs Infineon Technologies at a fair value of €50.32, which sits below the latest close at €59.3. That gap puts the stock on the expensive side of this framework and raises the question of how much of the AI data centre story is already factored into expectations.
Main “Take aways”:
• You get a well-managed company, with a healthy balance sheet, at a fair price.
• There is more “future” than you can see in the Snowflake.
• ROE is at 17.5%, future ROE at 16.2%.
• The future earnings growth rate at 8% could misguide you. The balance sheet looks very healthy, with the company largely owned by shareholders (equity €17.2b), and only a relatively low share held by banks (debt €5.4b). With that in mind, an ROE of 17.5% is a solid result, because it would be possible to raise ROE further through the leverage effect of debt. Infineon could sell more products by increasing production capacity, which would lead to higher earnings and directly increase ROE. The funding for additional production capacity could be provided by banks, which would increase debt. That is the leverage effect: more debt (at cost x) and significantly higher earnings (at 2–5 times x). However, Infineon operates in a very moderate way, with relatively low debt compared to equity. This leads to a healthy debt-to-equity ratio of 31.3%.
See why 19 investors see Infineon Technologies as 18% overvalued.
Result: Fair Value of €50.32 (OVERVALUED)
Still, Infineon Technologies faces real pressure points if the AI excitement cools or if the heavy Dresden investment fails to translate into stronger cash generation over time.
Find out about the key risks to this Infineon Technologies narrative.
Another View On Infineon Technologies: Earnings Multiple Sends Mixed Signals
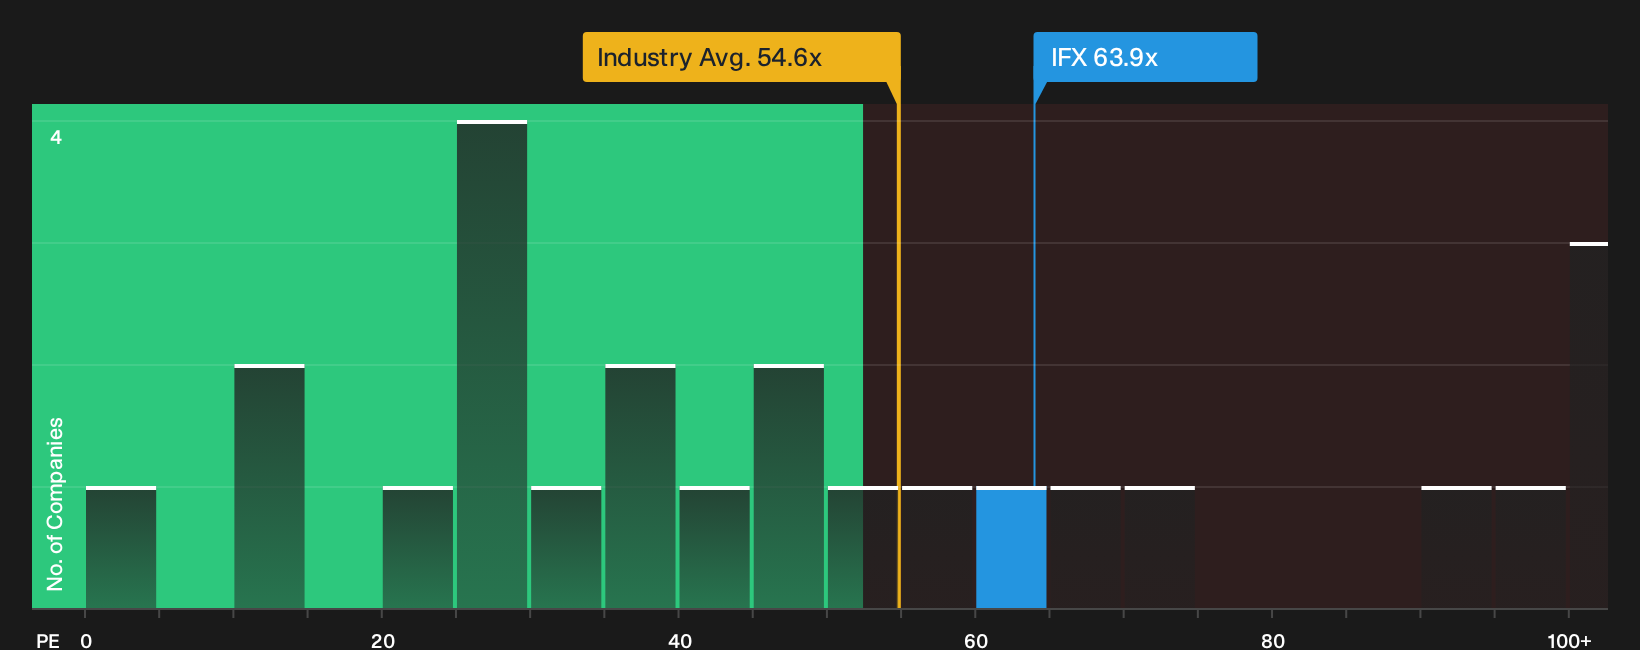
A second lens on Infineon Technologies comes from the P/E ratio. At 63.9x, it is slightly cheaper than close peers on 65.8x, yet richer than the wider European semiconductor group on 54.6x and above the 57.9x fair ratio that our model suggests the market could lean toward over time. For you as a shareholder, that mix points to some valuation risk if sentiment cools, even if near peers stay lofty.
To see what the numbers imply for that premium, and how much room there might be for sentiment to reset, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Opinion on Infineon Technologies is mixed, with both concern and optimism in play. Act promptly, review the data yourself, and carefully weigh the 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Infineon Technologies?
If Infineon Technologies has your attention, do not stop here. Fresh opportunities often emerge where fewer investors are looking, and you do not want to miss them.
- Target resilient cash generators and stress test your portfolio against volatility by scanning our 226 resilient stocks with low risk scores built to highlight companies with lower risk profiles.
- Hunt for quality at a potential discount through our 196 high quality undervalued stocks which filters for fundamentals that may not yet be fully appreciated in current prices.
- Strengthen your income stream by reviewing our 158 dividend fortresses focused on higher yielding businesses that pair distributions with balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com