
CITIC Construction Investment: Liberalizing insurance capital to invest in Hong Kong Stock Connect ETFs to help optimize cross-border asset allocation
The Zhitong Finance App learned that CITIC Construction Investment released a research report saying that the short-term performance of the securities sector was mainly affected by high market fluctuations and consolidation, but transactions remained high, financing structures were optimized, and valuation levels were low, which still supported the mid-term allocation value. In the insurance sector, allowing insurance capital to invest in the Hong Kong Stock Connect ETF has further expanded the insurance cross-border equity allocation toolbox, which helps ease QDII quota restrictions and improve allocation efficiency. It is expected to help insurance funds better consolidate long-term interest spreads through multi-asset allocation in a low interest rate environment. Hong Kong stocks and non-banks reported positive performance and undervaluation. Under a tight balance pattern in the second half of the year, there was a resonance or structural opportunity between improvements in fundamentals and valuation repairs. The release of policy dividends resonates with the delivery of technical dividends, and it is recommended to stick closely to the main line of “undervaluation+high dividend+high growth”.
CITIC Construction Investment's main views are as follows:
Securities Industry Views
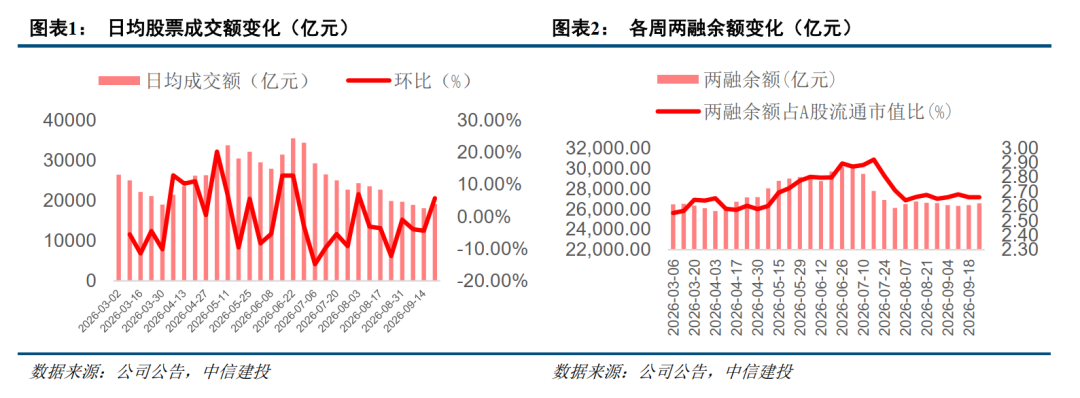
From September 21 to September 24, the average daily turnover of the A-share market was 1913.507 billion yuan, up 5.72% month-on-month from last week, and down 17.28% year-on-year. Market turnover gradually declined from the range of more than 2 trillion yuan in the previous period to around 1.9 trillion yuan, and trading activity has cooled down. Judging from the rhythm of the week, the market fluctuated and rebounded on Monday. The three major indices collectively closed and strengthened, with more adjustments in the early stages, and technology stocks rebounded; over the next few trading days, the market surged and retreated, individual stocks fell more and less, and the turnover gradually shrunk from above 2 trillion yuan. Some funds chose to wait and see until the holidays. In terms of sector rotation, the main line of industry rotation this week changed from the previous “weight and technology losing each other” to “high and low switching and style rebalancing”: active in low levels such as medicine and real estate, topics such as humanoid robots took turns, AI hardware chains such as communications and components fluctuated at a high level, and internal segmentation intensified, and part of the capital continued to rotate in the direction of dividends and cycles. Overall, the market is currently in a phase of high volatility and consolidation. The decline in volume and energy coexist with accelerated sector rotation. It is necessary to track changes in volume and energy and financial sustainability in the future.
The overall balance of the two loans has rebounded, but it is still at an all-time high. As of September 23, 2026, the balance of securities financing in the Shanghai and Shenzhen North markets reached 2,655.08 billion yuan, up about 4.50% from the beginning of the year, and slightly rebounded 0.64% from last week, accounting for 2.66% of the market value of A-shares in circulation. The overall balance of the two loans has maintained a positive growth trend since the beginning of the year, indicating that market risk appetite is still on the recovery path, and there has been no fundamental shift in leveraged capital expectations for the future market. Currently, the balance of the two loans accounts for around 2.7% of the market value in circulation. The level of leverage is basically in line with market capitalization expansion, and the risk of systemic leverage is generally manageable. In the future, if the balance of the two loans stabilizes or even regains its upward trend on the current high-ranking platform, it will further confirm the sustainability of incremental capital entry and provide additional liquidity support for the market.
IPOs and refinancing are at a steady pace, focusing on new quality productivity. In terms of IPO issuance, according to statistics from the date of issuance, a total of 18 companies were listed in September 2026 (as of the 24th), raising 20.445 billion yuan; in terms of refinancing, the total amount of corporate equity refinancing was 46.056 billion yuan. Looking at the distribution structure, the IPO market continues to be dominated by technology companies. The listing and application targets focus on new productivity core tracks such as semiconductors, artificial intelligence, and new energy, and the industry distribution is highly compatible with the direction of industrial structure upgrading. The inclusiveness of the Science and Technology Innovation Board and the GEM system continues to increase, the listing channels for unprofitable hard technology companies have been further broadened, and the review efficiency of high-quality technology companies has improved. In terms of refinancing, targeted increases still dominate equity financing. The policy level continues to be optimized around the three major directions of high-quality company support, adaptation to science and innovation enterprises, and institutional facilitation. As a tool to combine equity bonds, the function of convertible bonds in the refinancing system has been expanded. Overall, while the equity financing market maintains a steady pace, the resource allocation function is skewed towards the field of scientific and technological innovation, and the institutional foundation of the capital market serves the real economy and supports the development of new quality productivity continues to be consolidated.
In terms of public funds, the scale continued to grow, and the share of equity funds declined slightly. According to statistics from Tonghuashun, as of September 24, the net value of public funds in China reached 38.98 trillion yuan (excluding the market value of ETF-linked funds, ETFs used the latest market size), +6.06% compared to the end of 2025. Compared with the end of 2025, the share of equity funds in net worth decreased from 14.80% to 3.74pct to 11.06%, bond funds increased 1.75pct to 31.96% from 30.21%, while hybrid funds increased 2.07 pct to 12.02% from 9.95%. Since 2026, with the official completion of the three-stage rate reform, the implementation of performance comparison benchmark guidelines, mandatory disclosure of core indicators such as the share of profitable investors in the new information disclosure regulations, and the performance assessment management guidelines raising the weight of medium- to long-term assessments for more than three years to 80% and establishing a mechanism linking shareholders' dividends to investor profits and losses, the transformation of the public funding industry from “scale oriented” to “return oriented” has received institutional support. The concerted efforts of the above policies mark that China's public fund industry has fully entered a new stage with investors' interests as the core and high-quality development as the goal.
In terms of individual stocks, we continue to be optimistic about the three main lines: 1) brokerage firms with abundant technology project reserves and differentiated competitiveness in the big investment banking business; 2) leading brokerage firms and fintech targets with leading market share and revenue elasticity in the Big Wealth business; 3) leading brokerage firms that drive the upward trend in the ROE center from a medium- to long-term perspective.
External environment: The Fed is unlikely to cut interest rates in the short term, and the policy focus is still on suppressing inflation. On September 16, the FOMC meeting passed a 12-0 interest rate hike of 25 basis points, raising the federal funds rate target range to 3.75%-4.00% for the first time since July 2023. The median bitmap released on the same day showed that interest rate expectations for the end of 2026 were 4.1%, corresponding to an interest rate hike during the year or once more. It will remain unchanged in 2027, and interest rate cuts may only begin in 2028. The background supporting this path is that the CPI rose 3.4% year on year in August, the Federal Reserve raised the 2026 core PCE inflation forecast to 3.4%, and inflation stickiness still exists; while the job market remains steady, the non-agricultural sector added 162,000 new people in August, and the unemployment rate remained at 4.1%. Economic resilience provided room for the policy to maintain a restrictive stance. This week's US economic data is relatively light, focusing mainly on marginal changes in September's PMI, initial jobless claims, and durable goods orders. The opening of the window for subsequent interest rate cuts depends on the confirmation of a downward trend in inflation and a clear sign of weakening in the job market. Until then, the trend of high interest rates in the market may continue.
Insurance industry views
On September 24, 2026, according to a report by the China Securities News, the General Office of the State Financial Supervisory Administration recently issued a letter to local financial supervisory authorities, insurance group (holding) companies, insurance companies, and insurance asset management companies to clarify the supervisory standards for investing insured funds in Hong Kong Stock Connect ETFs. The document clarifies the relevant regulatory standards: insurance institutions that can invest in Hong Kong Stock Connect shares in accordance with regulatory regulations can invest in Hong Kong Stock Connect ETFs, and follow the relevant regulations for insurance funds to invest in Hong Kong Stock Connect shares. This regulatory standard came into effect on September 20. We believe that the main effects of allowing insurance funds to be invested in the Hong Kong Stock Connect ETF this time include:
First, it helps expand the insurance capital cross-border equity allocation toolbox, ease QDII quota restrictions, and improve the availability and execution efficiency of overseas allocations. In the past, insurance funds increased the allocation of overseas assets generally faced restrictions due to scarce QDII amounts. This time, insurance capital is allowed to invest in the Hong Kong Stock Connect ETF, adding a normalized overseas equity allocation path for insurance capital that does not require the use of QDII credits. Currently, the market continues to be in a low interest rate environment. The return on fixed income assets of insurance funds is thinning, and the pressure on the industry's scarce assets is prominent. However, the Hong Kong Stock Connect ETF is a standardized and highly efficient overseas equity investment instrument. On the one hand, it can enrich equity investment categories and help increase overall investment returns; on the other hand, it can further optimize the asset portfolio structure, increase the degree of asset diversification, and effectively improve the overall risk-return ratio characteristics of the portfolio. It is important to note that the investment targets of the Hong Kong Stock Connect ETF are not limited to the Hong Kong stock market. The share weight of stocks listed on the Stock Exchange and the share weight of Hong Kong Stock Connect shares in the underlying index required by the Southbound Hong Kong Stock Connect ETF is not less than 60%, and stocks from other markets can be allocated within a certain ratio. Currently, in addition to Hong Kong stocks, some products in the Southbound Hong Kong Stock Connect ETF also invest in stocks listed in other overseas markets such as the US, South Korea, and Japan.
Second, it helps to optimize the insurance portfolio construction model and improve the efficiency of insurance asset allocation and position adjustment. Compared with direct investment in individual overseas stocks, ETFs have the natural advantages of holding a basket of assets, transparent investment rules, convenient trading mechanisms, and low concentration of positions. By allocating Hong Kong Stock Connect ETFs, insurance capital can quickly establish strategic exposure to cross-border equity, flexibly adjust the weight of the combined industry, and reduce the market impact costs caused by large capital position adjustments. At a stage where the market style rotates rapidly, the pace of industry rotation accelerates, or when the asset portfolio needs to be rebalanced within insurance capital, the advantages of efficient allocation and convenient position adjustment of ETFs will be further highlighted. At the same time, relying on the decentralized nature of an ETF basket, insurance capital can effectively reduce risk exposure to a single target, reduce the non-systemic risk of the investment portfolio, and enhance the overall stability of the portfolio.
Third, leading insurers with strong capital strength are expected to benefit even more significantly. Hong Kong Stock Connect ETFs are classified as overseas equity assets. They have high capital occupancy attributes and place high requirements on the capital strength and solvency levels of insurance companies. Leading insurers have sufficient capital reserves, higher comprehensive solvency ratios, and stronger risk resilience. Overall, they have more sufficient capital space to carry out Hong Kong Stock Connect ETF allocations. They can make full use of this tool to achieve a decentralized layout of assets across markets and optimize long-term investment returns.
On September 24, 2026, the State Financial Supervisory Administration announced the monthly operating conditions of the insurance industry for August 2026. In terms of personal insurance, the original insurance premium income in January-August was -0.2%, with a cumulative year-on-year ratio of +0.04%/-10.0%/-1.08% for life insurance, accident insurance, and health insurance, respectively; in August alone, the original personal insurance premium income was -13.6%, of which life insurance, accident insurance, and health insurance were -15.1%/-6.9%/-4.6%, respectively. In terms of property insurance, the cumulative year-on-year premium income for January-August was +2.2%, with the cumulative year-on-year flat rate for car insurance and non-car insurance, respectively; in August alone, the original insurance premium income for property insurance was +1.8%, of which -0.02%/+4.5% of the same ratio for car insurance and non-car insurance, respectively. In January-August, the cumulative payout rate was +0.28 pct year on year to 58.6%; in August alone, the payout rate was +0.1 pct year over year to 75.3%.
On September 24, 2026, the State Financial Supervisory Administration issued a notice on the “Status of Motor Vehicle Traffic Accident Liability Compulsory Insurance Business in 2025”. Among them, it was mentioned that in 2025, the coverage of Jiaotong Insurance continued to expand, and the number of motor vehicles covered reached 386 million, an increase of 3.8% over the previous year. Among them, a total of 347 million cars were insured, an increase of 3.9% over the previous year. Risk protection capabilities have been effectively strengthened. The amount covered by Jiaotong Insurance reached 76.8 trillion yuan in the same year, an increase of 3.4% over the previous year. In that year, compensation expenses were 252.4 billion yuan, an increase of 11.6% over the previous year, and the effect of protecting people's livelihood increased markedly. Premium income grew steadily. In that year, Jiaotong Insurance's premium income was 285.2 billion yuan, an increase of 5.2% over the previous year. The average car premium was basically stable. In that year, Jiaotong Insurance's average premium was 762.1 yuan, a decrease of 0.1% over the previous year. Affected by factors such as the increase in personal injury compensation standards and the increase in the share of new energy vehicles, Jiaotong Insurance lost 23 billion yuan in operations that year. At the same time, the insurance industry continues to strengthen supervision, standardize disorderly competition, and promote cost reduction and quality improvement. From January to August 2026, the comprehensive cost rate of car insurance in the industry was reduced to 95.8%, and management continued to be optimized.
We believe that the main investment line in the insurance sector is expected to gradually switch to investment opportunities based on medium- to long-term value valuation repair and high dividend allocation. Looking ahead to the third quarter, the growth rate on both sides of the balance and liability side faced some month-on-month weakening pressure in the same period last year. The main upward momentum in subsequent stock prices is expected to shift from medium- to long-term value growth to valuation repair and high dividend allocation requirements based on medium- to long-term value. Strong demand for residents' savings insurance+favorable “anti-domestic” policies in the industry+channel side's efforts to expand incremental+dividend insurance transformation resonates with the quadruple benefits of excellent quality. It is clear that listed insurers are basically facing a positive trend in the long term. If subsequent macroeconomic policy increases exceed expectations, it is expected to catalyze sector valuation repair.
Overall, the insurance sector's medium- to long-term allocation value is prominent in the current position. If the potential pressure of the third-quarter performance growth rate under a high base causes short-term disturbances to stock prices, it is recommended to seize the opportunity to take advantage of a low layout and be optimistic about valuation restoration based on medium- to long-term value and high dividend allocation investment opportunities.
Views on the Hong Kong Market and the Hong Kong Stock Exchange
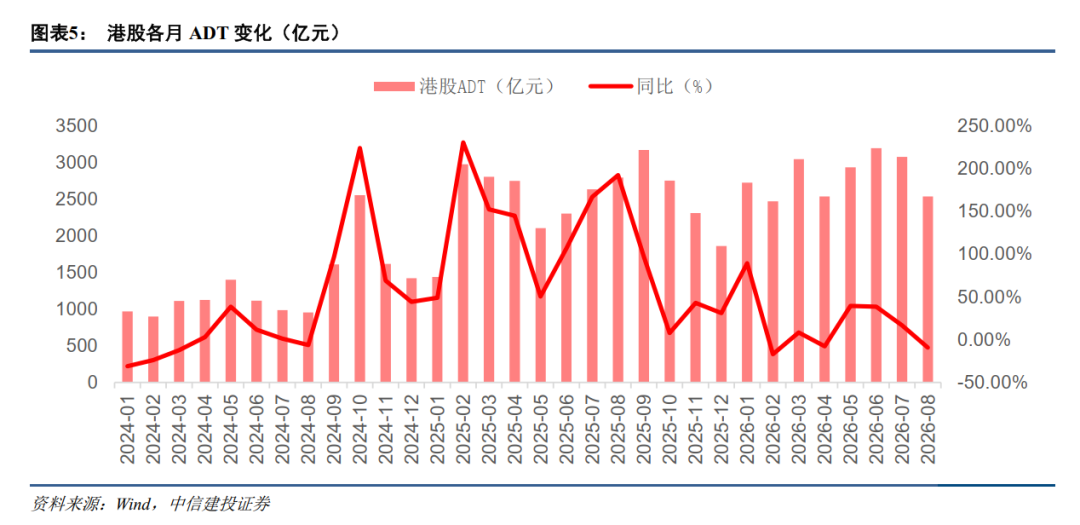
Hong Kong stocks and non-banks reported positive performance and undervaluation. Under a tight balance pattern in the second half of the year, there was a resonance or structural opportunity between improvements in fundamentals and valuation repairs. The Hong Kong stock market has adjusted since September, with the Hang Seng Index -4.13% and the Hang Seng Technology Index -6.67%. The overall Hong Kong market outperformed the MSCI World Index by 3.93%. On the asset side, as of September 25, the overall market value of Hong Kong stocks was HK$45.27 trillion, compared to -3.99% at the end of August; on the capital side, Hong Kong stock trading activity has declined since September; ADT was HK$204.888 billion, -11.05% month-on-month; of these, Southbound Capital ADT was -18.99% month-on-month, accounting for 21.21%. Derivatives turnover also declined. ADV futures were 530,000, -0.70% month-on-month and -20.44% year-on-year; options ADV was 920,000, 11.54% month-on-month, and -21.20% year-on-year.
In terms of interest rates, HIBOR interest rates have risen again since September 25; as of September 25, 6M HIBOR reached 3.51%, +0.29pct month-on-month, and +0.63pct since the beginning of the year; and as HIBOR remains high, the investment income of the Hong Kong Stock Exchange is expected to continue to rise, and the “hedging” effect is expected to be prominent.
Judging from the share of shorting transactions, Hong Kong stock shorting activity increased; in September, Hong Kong stock short sales accounted for +3.94 pct month-on-month to 20.85%; while judging from the newly updated share of Hong Kong stock short positions, as of September 25, the ratio of short positions to total market value increased 0.02% to 2.39% from the end of August.
What is the outlook for Hong Kong stock trading activity in the fourth quarter?
Hong Kong stock trading activity in the fourth quarter is likely to continue the “tight balance” pattern. The conditions for an overall upward trend are insufficient, and structural rotation is still the main trend. The Hong Kong stock market experienced a round of adjustments in the first half of 2026. The Hang Seng Index fell 10.73% cumulatively, and the Hang Seng Technology Index fell 18.92%. In the early morning of September 17, Beijing time, the Federal Reserve announced that it would raise the federal funds rate target range by 25 basis points to 3.75% — 4.00%. This is the first policy tightening since July 2023. The resolution was passed by 12 full votes. The median bitmap shows that interest rates will remain unchanged until the end of 2026 or another time. After the resolution was implemented, the 10-year US Treasury yield rebounded above 5%, the US dollar index rose above 100, and global risk assets were generally under pressure. External liquidity constraints have changed from expectations to reality, and high interest rates may last longer than previously judged, so investors are cautious. Based on current developments, Hong Kong stock trading activity in the second half of the year is more likely to show structural differentiation rather than an overall jump.
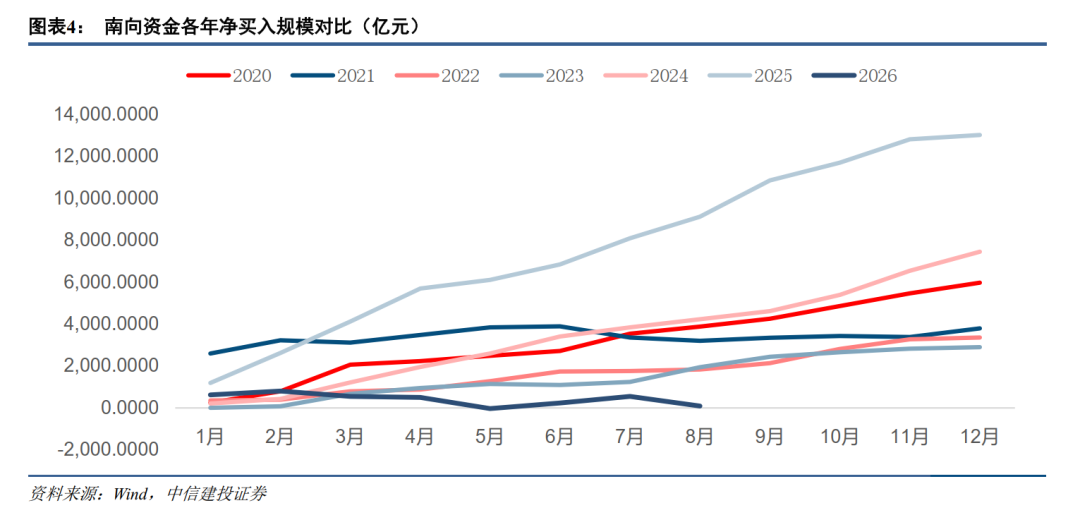
Looking at external liquidity and capital structure, valuation suppression under the Hong Kong dollar interest rate linked to the US dollar, and differentiation in domestic and foreign investment behavior are the two main lines in terms of capital. Under the linked exchange rate system, the Hong Kong dollar interest rate is generally close to the US dollar interest rate. After the implementation of the Federal Reserve's interest rate hike in September, the Hong Kong Monetary Authority immediately followed an increase in the benchmark interest rate by 25 basis points to 4.25%. The Hong Kong dollar interest rate will remain high along with the US dollar, putting a phased pressure on the restoration of Hong Kong stock valuations. In terms of domestic capital, the previous record inflow of southbound capital slowed in 2026, and the inflow pace was repeated. In terms of allocation structure, capital is characterized by “dumbbell” position adjustments, and is flowing from the highly valued Internet sector to the direction of high dividend dividends, innovative drugs, and new consumption. In terms of foreign investment, against the backdrop of uncertainty about the Federal Reserve's policy path, institutions disagree on their expectations when interest rate cuts will begin, and there are doubts about the extent to which foreign investment will be systematically replenished in the fourth quarter. Overall, southbound capital inflows in the second half of the year may be higher than in the first half of the year, and are still expected to form a major source of growth, but the capital balance is likely to remain tight throughout the year.
Looking at asset supply and profit restoration, asset structure optimization and supply-side pressure coexist, and profit verification is still a core variable. On the one hand, the listing of hard technology companies in Hong Kong continues to be popular, and listed reserve projects provide basic support for medium- to long-term liquidity; on the other hand, the lifting of the ban on restricted shares in the second half of the year combined with the centralized release of IPOs and refinancing. Supply-side expansion tested the ability to accept capital, and stock capital is facing diversion pressure. At the profit level, profit recovery in the non-financial sector of Hong Kong stocks is expected to continue in the second half of the year, but the overall profit growth rate of enterprises is still weaker than previously anticipated. The market is shifting from “valuation-driven” to “profit verification,” and we need to wait for a resonant signal of an increase in profit expectations.
Overall, whether Hong Kong stock trading activity can continue in the second half of the year depends on a triple game: First, the pace of evolution of the Federal Reserve's policy under Walsh's leadership. Interest rate hikes in September have already been implemented, but the bitmap shows that interest rate hikes are still possible during the year. The 2027 guidelines mean that external liquidity easing will ease or move backwards. Subsequent interest rate meetings and inflation data are still important observation points; second, whether the pace of capital inflows to the south remains stable; third, whether the pace of capital inflows to the south remains stable; third, the dynamic balance between the expansion of the supply of new stocks and the ability to accept capital. Under the dual constraints of tightening external liquidity expectations and slow recovery of internal profits, Hong Kong stocks are more likely to show structural activity in a “tight balance” in the second half of the year rather than an overall upward trend. The high-dividend defense sector may continue to show rotating characteristics with boom tracks such as AI applications, innovative drugs, and new consumption, while the traditional Internet and financial sectors may be under relative pressure. The substantial reversal of market trends still needs to await the resonance signals of an increase in profit expectations and an improvement in the external liquidity environment.
Consumer finance industry views
Driven by the implementation of the “Personal Loan Business Clarifying Comprehensive Financing Cost Regulations” (hereinafter referred to as the “New Comprehensive Financing Cost Regulations”), increasing consumer promotion policies, and improving the efficiency of AI technology, the consumer finance industry is shifting from a “hidden pricing game” to “explicit cost competition.” The industry is in a period of resonance between the release of policy dividends and the realisation of technology dividends. With a first-mover advantage in compliance and refined operation capabilities, such institutions can not only undertake the beta market of quantitative, price-quality repair in the industry, but also build excess revenue α through technical barriers. Currently, they are in a double-click window for performance implementation and valuation repair.
(1) Industry fundamentals: the triple resonance of “stable quantity, price increase, and excellent quality”, and the 2026 valuation repair cycle was established
Volume: Increased penetration is a hedging stock game. Macro stimulus compounded economic recovery in 2026, and the penetration rate of online credit services continued to increase. Despite stricter regulations, leading consumer finance and loan aid institutions are expected to maintain steady growth of +5%-10% year-on-year based on compliance flows and scenario advantages.
Price: The transparency of comprehensive financing costs stabilizes interest spreads. The “New Comprehensive Cost Regulation” requires that all fees be specified, eliminating the grey charging space. Although the upper limit of nominal interest rates has been suppressed in the short term, in the long run, the industry's revenue growth rate is expected to return to double digits as ABS distribution is normalized and AI technology reduces operating costs and risk costs for individual customers. Instead, transparent pricing helps leading institutions dilute costs through scale effects and ease the pressure of narrowing interest spreads.
Quality: Forward-looking indicators improved month-on-month, and asset quality differentiation intensified. Forward-looking indicators such as D1 overdue rate, D30 recovery rate, and D90 overdue rate have reached inflection points. Under uniform regulatory standards, companies that prioritize asset quality restoration will gain higher performance flexibility.
(2) In-depth interpretation of the new regulatory regulations: from “formal compliance” to “real pricing anchoring”
The scope of supervision is seamlessly connected, blocking room for arbitrage. The “New Comprehensive Financing Cost Regulations” not only cover small loan companies, but also include all business formats such as banking, consumer finance, and loan aid into a unified disclosure framework. The core is to unify the “comprehensive financing cost” calculation scale of various lenders to prevent institutions from supervising arbitrage by changing license types or splitting fee structures. This means that regardless of the licensee, as long as they lend money to the C-side, they must follow the same set of cost disclosure and pricing restrictions.
Form a “combo punch” with the new loan aid regulations to anchor the downward goal of long-term interest rates. The “New Loan Assistance Regulations” focus on “cleaning up the gray model”, eliminating hidden charges such as double financing and membership fees, and achieving transparent pricing; while the “Small Loan Guidelines” and the “New Comprehensive Finance Cost Regulations” further put forward the long-term hard requirement of “reducing LPR by 4 times” on the basis of transparency. The collaboration between the two marks a new stage in the consumer credit industry from “cracking down on irregularities” to “guiding reasonable pricing,” and has set a clear long-term interest rate ceiling for the industry.
Compliance has become a core competency, not just a cost. Under the new regulations, regulatory ratings can be upgraded for 6 consecutive months, and priority is given to tax relief, inclusive finance refinancing support, and stable credit reporting rights. Compliance capabilities are directly transformed into financing cost advantages and customer acquisition efficiency, and the Matthew effect of leading institutions will be further strengthened.
(3) Evolution of the industry pattern: stratification of customer groups and acceleration of market-based clean-up
Competition for the customer base is heating up, and the sinking market is facing a major test of commercial sustainability. The high-quality customer base (interest rate range of 12%-18%) will become the focus of competition throughout the industry, and profit margins may be further compressed. However, under the hard constraint of “comprehensive financing costs,” long-tail customer groups with high risk and high service costs will be forced to withdraw if they are unable to achieve break-even within 4 times the LPR. This forces institutions to rely on AI risk control and refined operations to expand “profitable sinking boundaries.”
Regulatory arbitrage has disappeared, and industry consolidation has accelerated. Mid-tail small loan companies that lack technological capabilities and rely on high interest spreads will expedite settlement (the number has dropped from nearly 9,000 to 5,385). Leading institutions with strong capital and leading technology will expand their share through mergers and acquisitions, fiduciary management, etc., and industry concentration will increase significantly.
Commercial banks: They are subject to dual regulation, and the maximum judicial protection limit is 24%, but the actual pricing is mostly 3%-8%. The regulation has put an end to the price war. In the future, it will focus on low-risk, high-quality customer groups such as civil servants and central government enterprises. Basically, there will be no hidden charges or violent collection issues.
Consumer finance companies: Window guidance average pricing should be below 20%, and the product range is 12%-24%. As a supplement to the bank's customer base, it covers suboptimal to long-term customers, and has diverse risk pricing strategies, which is a key level to take charge.
Small loans/Internet microfinance: Short-term is subject to 24% restrictions, and long-term (before the end of 2027) self-operated businesses need to be reduced to 4 times the LPR. Key perception correction: The essence of the loan aid business is technology services. Revenue comes from traffic and service fees, decoupled from loan interest rates, and is not limited by 4 times LPR. The position of inclusive finance remains unchanged, and it is still an important complement to banks and consumer finance. Leading institutions may experience “volume reduction” in the short term or due to compliance adjustments, but in the long term, they will benefit from market share concentration and improved profit quality after the industry is cleared.
(4) Investment strategy: avoid vulnerable players and focus on two types of “compliance winners”
Focus on two types of targets: the first is state-owned or industrial consumer finance companies with strong shareholder backgrounds and low financing costs: they naturally adapt to a low interest rate environment and have a financial advantage over the cycle. Second, it is a leading credit technology platform with outstanding fintech strength and successfully transformed into a self-operated credit technology platform. Its compliance and security are strong, and the impact of the “new comprehensive financing cost regulations” on its business within its schedule is manageable. A positive cycle has been formed, with good compliance records → improved regulatory ratings → receiving low-cost funding and credit reporting support → expanding the high-quality customer base → further consolidating compliance advantages.
Rental industry views
Core view: It has the three best characteristics of “high interest spreads, low defects, and high dividends”. The current investment value of the leasing industry (including financial leasing and financial leasing) is reflected in three core dimensions: high net interest spreads (net interest spreads of about 4% for leading companies), low non-performing rate (the overall non-performing rate of the industry is stable at around 1%), and high dividend returns (the average dividend rate of the industry exceeds 6%). This triple advantage, combined with the current industry's overall valuation at an extremely low level in history, makes it a high-quality allocation direction with both defensive attributes and deterministic returns against the backdrop of increased financial market fluctuations and continued asset scarcity.
Fundamental aspects: Interest spreads operate at a high level, and asset quality continues to improve. Specifically: (1) Net interest spreads remain at a high level. Although net interest spreads in the financial sector are generally under pressure, leasing companies still have room to buffer net interest spreads due to resilient asset-side pricing and high rental yields brought about by declining credit. According to sample statistics from the “China Financial Leasing Industry Development Report 2026”, the average net interest spread of financial leasing companies in the first three quarters of 2025 was 3.43%, which is significantly superior to the overall level of commercial banks; leading listed institutions are more resilient in terms of profit.
(2) Asset quality has been steadily improving, and the non-performing rate continues to decline. Financial leasing companies' asset quality indicators have recently improved markedly, and the share of non-performing financial leasing assets has declined. According to the industry development report issued by the China Banking Association, as of the end of 2025, the non-performing financial leasing asset ratio of the entire industry was 0.91%, a steady decline over the previous year; the asset quality performance of leading institutions was better. As of the end of June 2026, the asset quality performance of leading institutions was 0.89%, which remained low for nearly five years. The provision coverage rate reached 397.6%, and the risk compensation capacity remained adequate.
(3) High dividend attributes stand out, constituting an important margin of safety. Listed leasing companies still show high dividend undervaluation characteristics. The dividend ratio of listed financial leasing companies remained at a high level in 2025.
In terms of policy and regulation, clean up the original source and accelerate industry differentiation and concentration of leaders
(1) Systematic reshaping of the regulatory framework: Since 2025, regulatory policies have been intensively introduced to establish a dynamic supervision mechanism covering the entire life cycle: “Financial Leasing Company Regulatory Rating Measures” (January 2025): rationally adjust rating factors, optimize regulatory ratings, improve the rating process, and strengthen the direct link between rating results and capital replenishment and business entry. The “Financial Leasing Business Management Measures for Financial Leasing Companies” (issued on December 5, 2025, and implemented on January 1, 2026): A total of 8 chapters and 68 articles have been established, covering due diligence, risk assessment and approval, contract conclusion and execution, post-lease management, risk management and internal control, etc., filling some institutional gaps at the micro level of the financial leasing industry, marking a shift in regulatory logic to penetrating micro business management.
(2) Return to the roots of “fusion” and curb “credit” business: The new regulations emphasize that the primary premise of financial leasing business compliance is compliance with leased property types, strictly prohibits non-equipment after-sales leaseback and “low value and high purchase”, strengthens the eligibility review of leased property, and fundamentally blocks the “high evaluation and high loan” arbitrage space. The core goal of the policy is to push the industry back from a “credit-like” model to its “financing+finance” roots to better serve the real economy's equipment renewal and industrial upgrading needs.
(3) Industry differentiation intensifies, and resources are concentrated at the top: In the short term, rising compliance costs and inventory clean-up will cause industry pain, but in the long run, it will drive the industry to shift from “scale expansion” to “quality improvement”. Leading companies will further concentrate their market share with their specialization capabilities and compliance advantages, and small and medium-sized companies need to find living space through deep segmentation.