
How Buybacks And Pipeline Expansion At HF Sinclair (DINO) Have Changed Its Investment Story
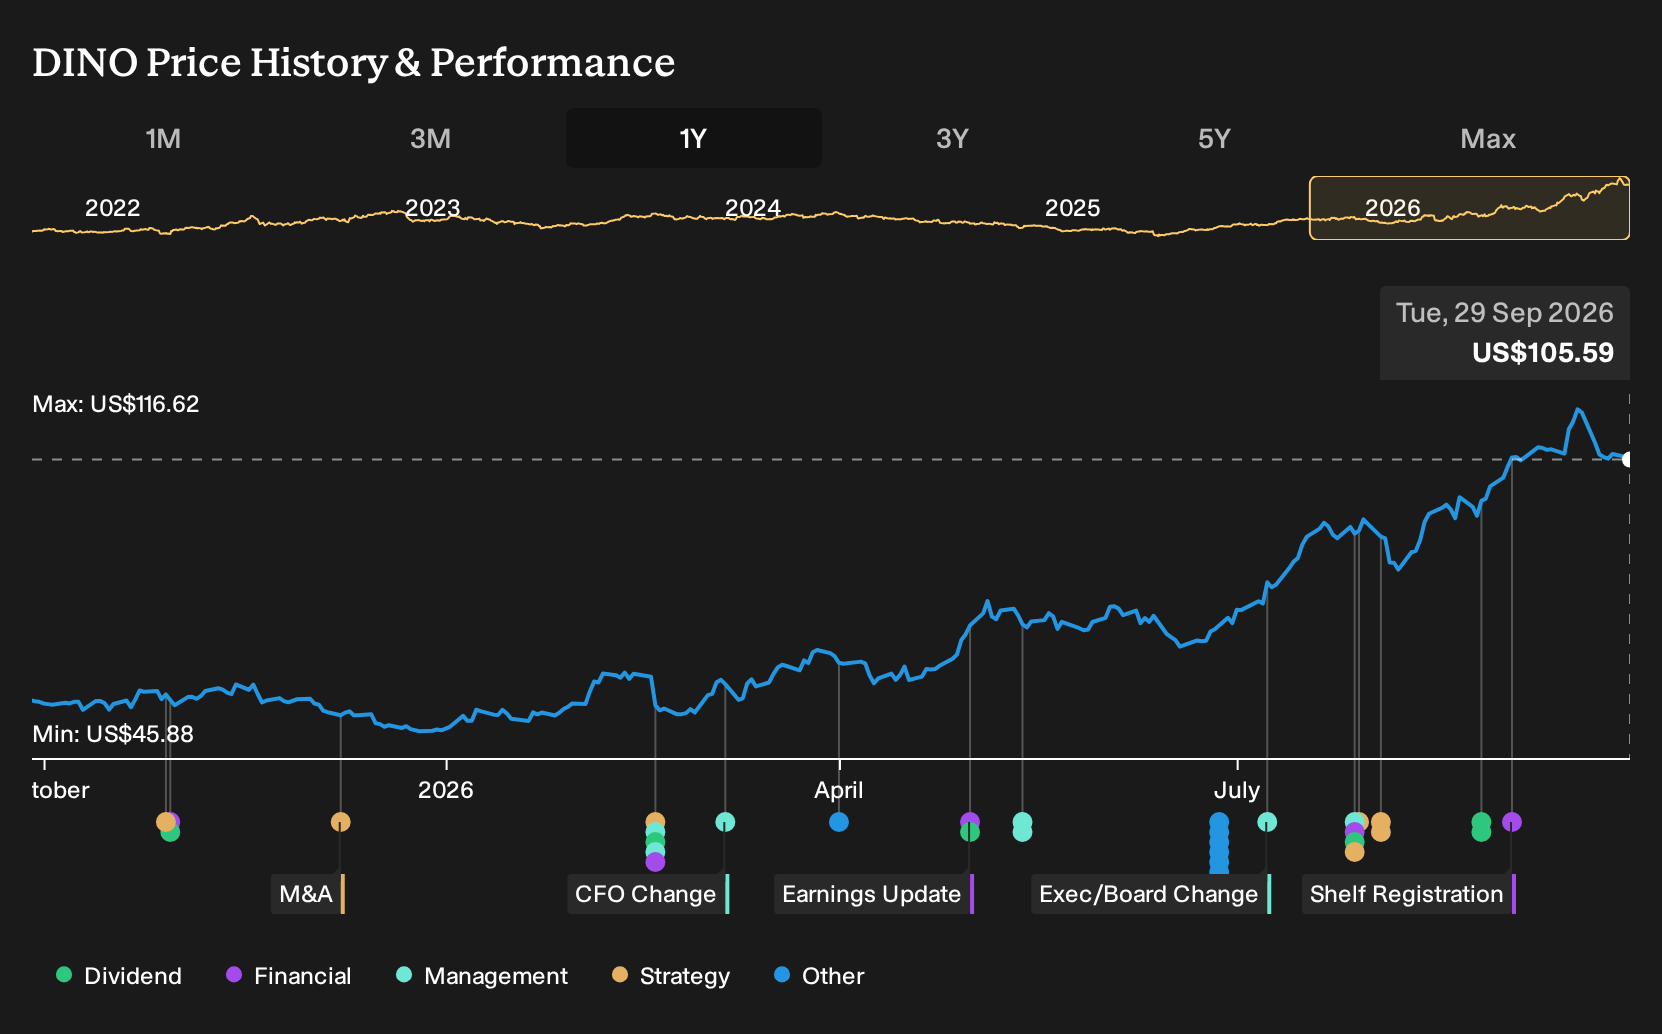
- HF Sinclair refreshed its capital return approach in August 2026 with a new US$1.5b share repurchase program and a planned spin off of its Lubricants & Specialties business, while advancing a Western Gateway Pipeline joint venture with Phillips 66 and Kinder Morgan to strengthen fuel supply to Western markets.
- The combination of midstream expansion through the DINO Go West initiative and a sharpened focus on refining, marketing, and renewables signals HF Sinclair’s push toward a more integrated, cash flow focused portfolio that leans on pipeline connectivity rather than specialty products.
- We will now explore how HF Sinclair’s expanded Western Gateway midstream joint venture could reshape its investment narrative for long term oriented investors.
Scan energy stocks that emphasize cash returns and pipeline growth by reviewing the hand picked 39 power grid technology and infrastructure stocks alongside HF Sinclair’s Western Gateway and its reset share buyback program.
HF Sinclair Investment Narrative Recap
For you to own HF Sinclair, you need to believe the refining and fuel distribution engine can keep throwing off cash even as earnings are forecast to decline 21.3% per year over the next three years and revenue is expected to contract 2.2% annually. The near term story hinges on how efficiently the refineries run, how quickly Western Gateway and DINO Go West add operational flexibility, and whether renewables move away from breakeven EBITDA. Right now, the biggest swing factor is execution on integration and cost discipline, not a single one off headline.
The most important short term catalyst is whether HF Sinclair can turn recent projects and asset reshaping into steadier cash flow, even with lower consensus earnings forecasts and an inexperienced management team at 0.2 years average tenure. The key risk sits on the other side of that equation. Aging infrastructure, high maintenance spend, regulatory pressure, and a renewable fuels business that lags peers could all absorb more cash than expected and limit flexibility, especially with earnings already projected to decline.
The US$1.5b share repurchase program announced in August 2026 is the announcement that links most directly to the current narrative. It matters because HF Sinclair already relies on returns of capital as a core part of the equity story, with the stock trading at a 9.9x P/E against both the US Oil and Gas sector at 12.5x and a peer average of 25.2x. Buybacks feed directly into per share math when analysts also expect the share count to fall 3.35% per year.
For you, the practical question is whether HF Sinclair can keep funding that expanded repurchase while earnings are projected to decline and capex needs remain elevated across refineries, renewables, and midstream. If crack spreads, renewable credits, or project execution do not line up with expectations, capital returns could become less predictable, especially with an unstable dividend record already on the table. The repurchase plan is therefore both a potential support for the equity story and a real time test of how resilient the cash engine proves to be.
HF Sinclair's narrative benchmarks revenue of US$30.4b and earnings of US$1.3b by 2029, based on analyst estimates that assume fairly flat top line performance, a decline in margins from 6.1% to 4.1%, and an earnings drop of US$600m from US$1.9b today.
Uncover why HF Sinclair's fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For HF Sinclair, the bearish twist in the story is the EV and regulation risk. The lowest analysts were already penciling in revenue sliding to about US$26.9b and earnings easing to US$859m by 2029, well before this Western Gateway and buyback news. That gap shows how far opinions can stretch. Use it as a prompt to compare several viewpoints before deciding how this new pipeline and capital return shift might reshape the narrative.
Explore 4 other HF Sinclair fair value estimates, including one that suggests as much as 20% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your HF Sinclair research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for HF Sinclair. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HF Sinclair's overall financial health at a glance.
Looking For More Investment Ideas Beyond HF Sinclair?
If HF Sinclair's mix of capital returns, refining exposure, and pipeline growth has your attention, it can help to line it up against a wider watchlist built around clear fundamentals. The Simply Wall St Screener lets you filter for the traits you care about most, so you are not relying on one stock or one story.
- For investors who want potential mispricing backed by solid balance sheets and cash flows, start with a curated set of 32 high quality undervalued stocks that might warrant a closer look.
- If income reliability matters more to you than headline growth, focus on companies in the 6 dividend fortresses that combine higher yields with a focus on payout strength.
- To prioritize resilience over excitement, consider building a watchlist around 32 resilient stocks with low risk scores that score well on financial stability and downside protection.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com