
How Investors May Respond To Banc of California (BANC) New Downtown LA Office
- Banc of California recently opened a new 40,000 square foot office in Downtown Los Angeles, with city leadership describing the move as part of a broader push to revive the local economy.
- The decision to invest in a large physical hub in Downtown suggests management sees sustained demand from local businesses and is prepared to absorb higher fixed costs in order to deepen its regional presence.
- The next consideration is how this new Downtown Los Angeles office could reshape Banc of California's investment narrative and long-term positioning.
Scan beyond Banc of California and see how other regionally focused lenders are positioning for local recoveries with the hand picked list of solid balance sheet and fundamentals (25 results).
Banc of California Investment Narrative Recap
Banc of California asks you to believe in a very specific story. A California focused lender that leans into urban markets, uses digital tools to win and keep deposits, and benefits from scale after the Pacific Western Bank merger. The new Downtown Los Angeles office fits that script but does not fundamentally shift it.
The near term swing factor still sits in execution. Integration costs, deposit pricing, and credit quality in Southern California commercial real estate remain the key levers. The Downtown build out adds fixed expense and local exposure. For now, it looks incremental to existing risks rather than a new driver of the Banc of California thesis.
One data point that ties closely to this move is the ongoing merger integration with Pacific Western Bank. Management is attempting to capture cost synergies and better economics from a larger footprint. The Downtown Los Angeles hub gives that combined platform a higher profile touchpoint with local borrowers and depositors.
For you as a shareholder candidate, the question is whether the integration benefits and digital investments can offset rising funding costs and region specific credit exposure. The bank is still unprofitable today. Execution on the merger and disciplined loan underwriting remain the operational catalysts to watch.
Banc of California's narrative projects US$1.6b revenue and US$755.2 million earnings by 2029. This implies 33.4% yearly revenue growth and an earnings increase of about US$807.5 million from a loss of US$52.3 million today.
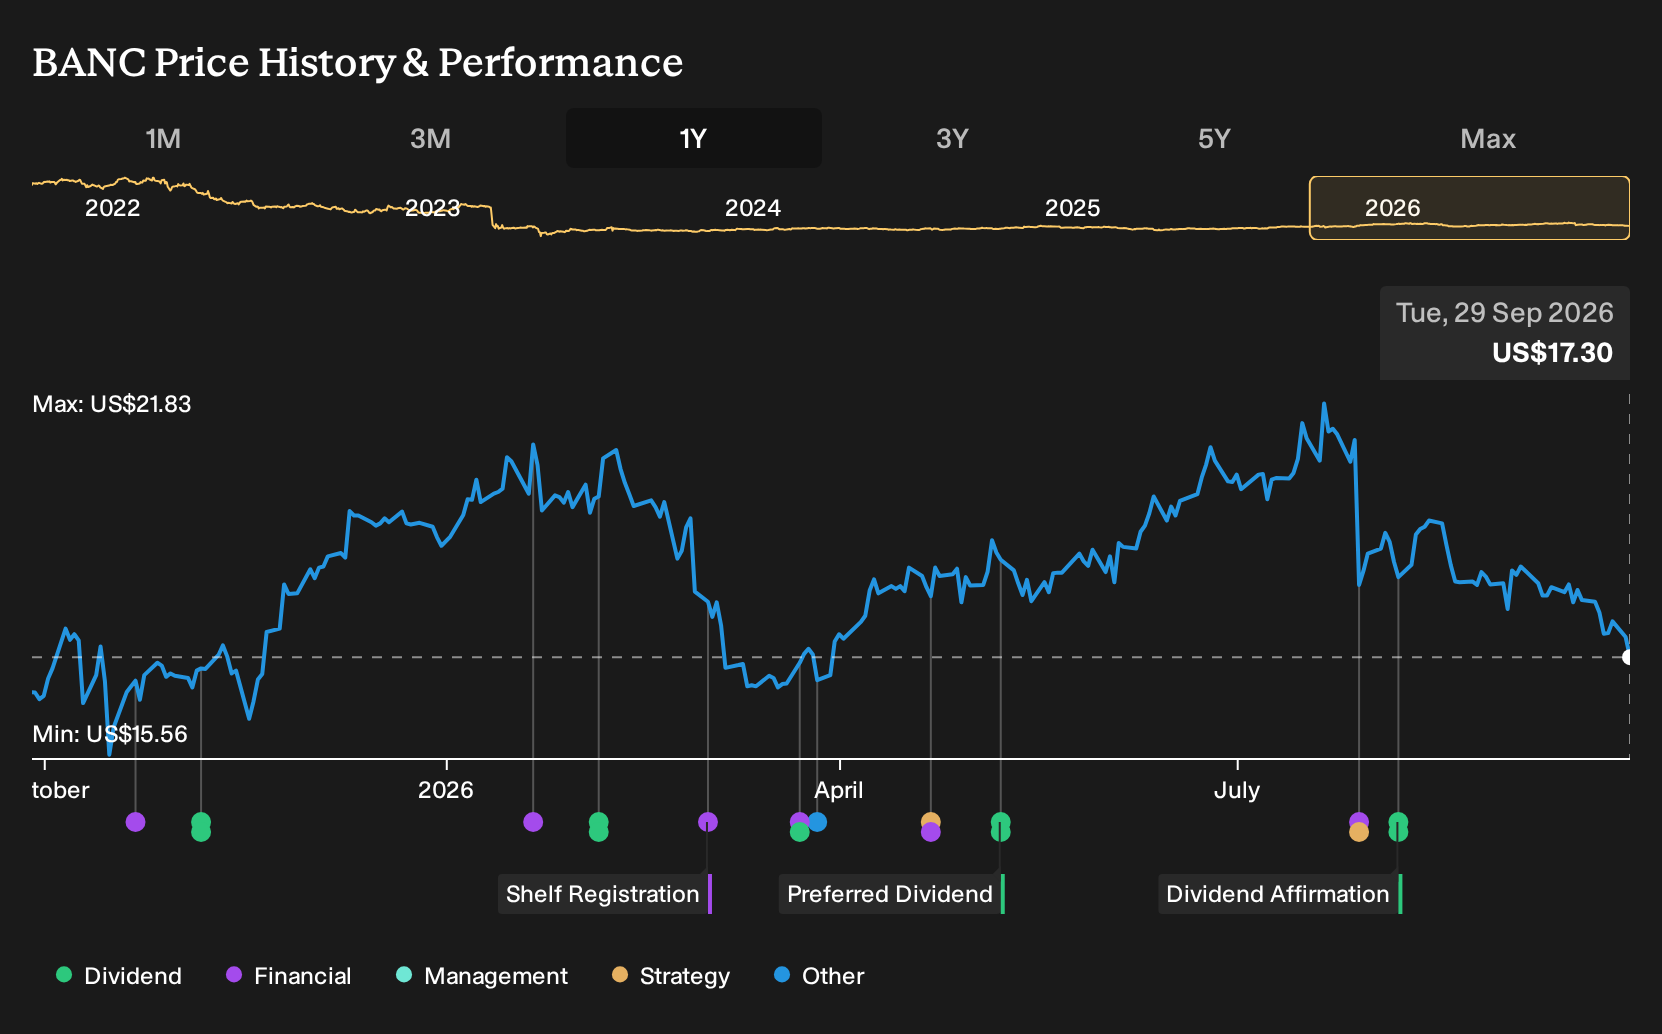
Discover how Banc of California's fair value indicates a 28% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
Some of the most optimistic analysts frame the new Banc of California office through the lens of margin expansion. Before this move, their higher end models were already working with roughly 33.6% yearly revenue growth and about US$605.3 million in earnings by 2029. Those projections did not yet weigh this Downtown Los Angeles commitment, so opinions may shift and diverge further as different scenarios are compared.
Explore 2 other Banc of California fair value estimates, including one that suggests as much as 348898% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and instincts.
- A great starting point for your Banc of California research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Banc of California. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banc of California's overall financial health at a glance.
Looking for more Banc of California style investment ideas?
If Banc of California has you thinking about where risk, balance sheet strength, and upside potential intersect, it can help to widen the lens and compare it with other businesses that fit different profiles.
- If you want companies that screen well for both quality and valuation, start with a focused group of 32 high quality undervalued stocks that already combine solid fundamentals with pricing that may appeal to value driven investors.
- If income is a priority for your portfolio, zero in on dependable payers with the 6 dividend fortresses that highlight businesses offering higher yields with an emphasis on resilience.
- If capital preservation matters most to you, narrow the field to steadier names through a curated 32 resilient stocks with low risk scores that emphasizes stronger financial profiles and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com