
Tariff Uncertainty Is Hitting Miller Industries Stock And Other US Industrial Names
Tariffs that once looked like settled policy are back in question after legal challenges to Trump era global levies on imports, and that uncertainty now sits directly on the cost base of many US consumer and industrial stocks. Import heavy businesses could see either sudden cash windfalls from refunds or more permanent pressure on margins. This article walks through three specific stocks from our screener that appear closely tied to these trade shocks and explains why their stories merit attention right now.
The three stocks highlighted next are only a starting sample from this tariff sensitive theme. The full screen surfaced 14 more companies with equally detailed import stories that are not covered below. To go beyond the shortlist and identify which import exposed US consumer and industrial stocks best fit your own thesis, analyze the full US Import-Dependent Consumer & Industrial Companies screener through the US Import-Dependent Consumer & Industrial Companies screener.
Miller Industries (MLR)
Miller Industries plugs straight into the tariff story because towing and recovery equipment built in the US often leans on imported steel and components, so shifts in trade rules can feed directly into its cost base and earnings profile.
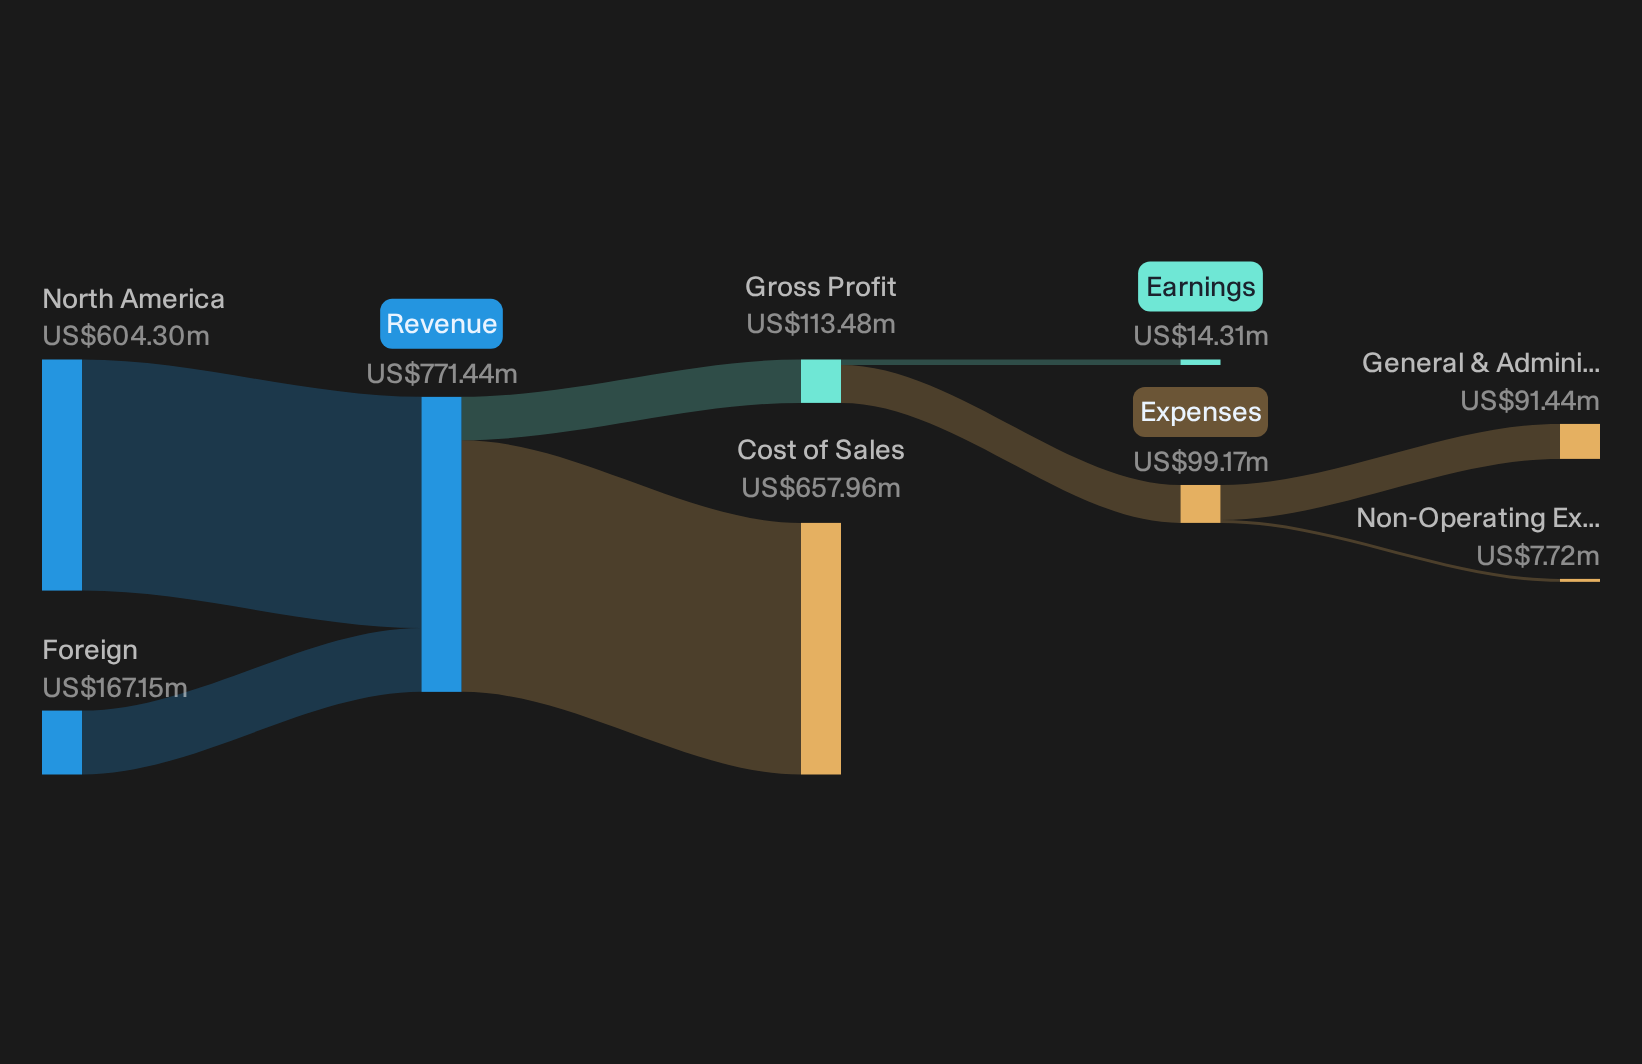
Miller Industries manufactures towing and recovery vehicles and trailers, generating about $771 million from auto manufacturers, with brands like Century and Vulcan sold across North America and overseas. With a roughly $613 million market cap, Miller Industries gives investors exposure to tariff-sensitive industrial demand.
"Miller's sustained investment in automation, advanced manufacturing, and the expansion of higher-margin heavy-duty segments create significant structural tailwinds for net margin expansion over a multi-year period, supporting compound earnings growth beyond current market forecasts."
What really matters now is how one unresolved trade cost pressure interacts with that margin story when tariff decisions finally land.
When that tariff call finally comes, read the full narrative for Miller Industries to see how Miller Industries’ import costs, pricing power, and automation push could be decoupling.
Fabrinet (FN)
Fabrinet plugs into the import theme through its global optical and electronic manufacturing chain, where high value components move across borders before landing in finished networking gear that feeds AI data centers, automotive systems, and medical devices.
Fabrinet provides optical packaging and precision manufacturing services, generating about US$4.6b from optical networking equipment, and has a market cap near US$14.7b. This places a lot of weight on how efficiently that import heavy production model converts into cash and earnings over time.
"Surging AI related data center optics and DCI demand, with data center revenue at 51% of total and Q4 FY26 DCI products at more than a 1b annualized run rate, points to a multi year build out that could keep Fabrinet’s utilization and data center revenue elevated. Persistent shortages in key components such as lasers, memory and ASICs have already limited Datacom growth in recent quarters."
What investors really have to watch now is what happens if a single assumption about that supply chain cost base stops holding up.
If that assumption breaks, read the full narrative for Fabrinet to see whether Fabrinet’s tariff exposure is quietly masking a much stronger long term earnings engine.

Power Solutions International (PSIX)
Power Solutions International sits neatly within the import dependent theme because its engines and power systems rely on sourced components, so any swing in tariffs can flow straight through into costs, pricing decisions, and how much cash the business keeps from each contract.
Power Solutions International designs and builds engines and packaged power systems, generating about $676 million from engineered integrated electrical power generation systems, and has a market cap of roughly $1.1b.
"The 62% increase in sales is positive, but the damage these sales have caused to the balance sheet is unsustainable. Inventory increased by 62% in nine months, from $93.8 million to $152.2 million, creating the risk of unsold product or a working capital trap."
What really matters now is how one unresolved cost pressure interacts with that working capital load when tariff decisions finally land.
That tariff hit and working capital squeeze could be masking something more interesting, so read the full narrative for Power Solutions International to see whether Power Solutions International’s story is quietly turning.

Seeking Fresh Alternatives Before Others?
New ideas move first, prices move next. The strongest breakouts and quiet momentum are often noticed late. Scan these fresh picks before the crowd and consider them early.
- Spot resilient balance sheets before they attract broad attention by scanning the curated list of solid balance sheet and fundamentals (25 results) while it still sits under most investors’ radar.
- Follow developments in AI-focused businesses by tracking cash generative operators drawn from 37 profitable AI stocks that aren't just burning cash before sentiment shifts and entry prices change.
- Review potential infrastructure opportunities by looking at power grid enablers filtered through 39 power grid technology and infrastructure stocks while pricing conditions may still favor early attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com