
Will New Customer Offers Change AGL Energy's (ASX:AGL) Narrative
- AGL Energy has rolled out new customer offers, including up to A$300 in bill credits on energy plans, bundling discounts across internet and mobile, and free Netflix Standard with ads for customers who remain on its Netflix Electricity Plan.
- The package pushes AGL Energy deeper into multi service bundling by using streaming perks and cross product discounts to strengthen retention and spread customer spend across more of its utilities portfolio.
- This article will examine how AGL Energy's investment narrative is influenced by its push into multi service bundling through energy and telco offers.
Scan how AGL Energy's bundling push compares with other utilities and telecom driven plays by running through the hand picked list of solid balance sheet and fundamentals (12 results) in the same space.
AGL Energy Investment Narrative Recap
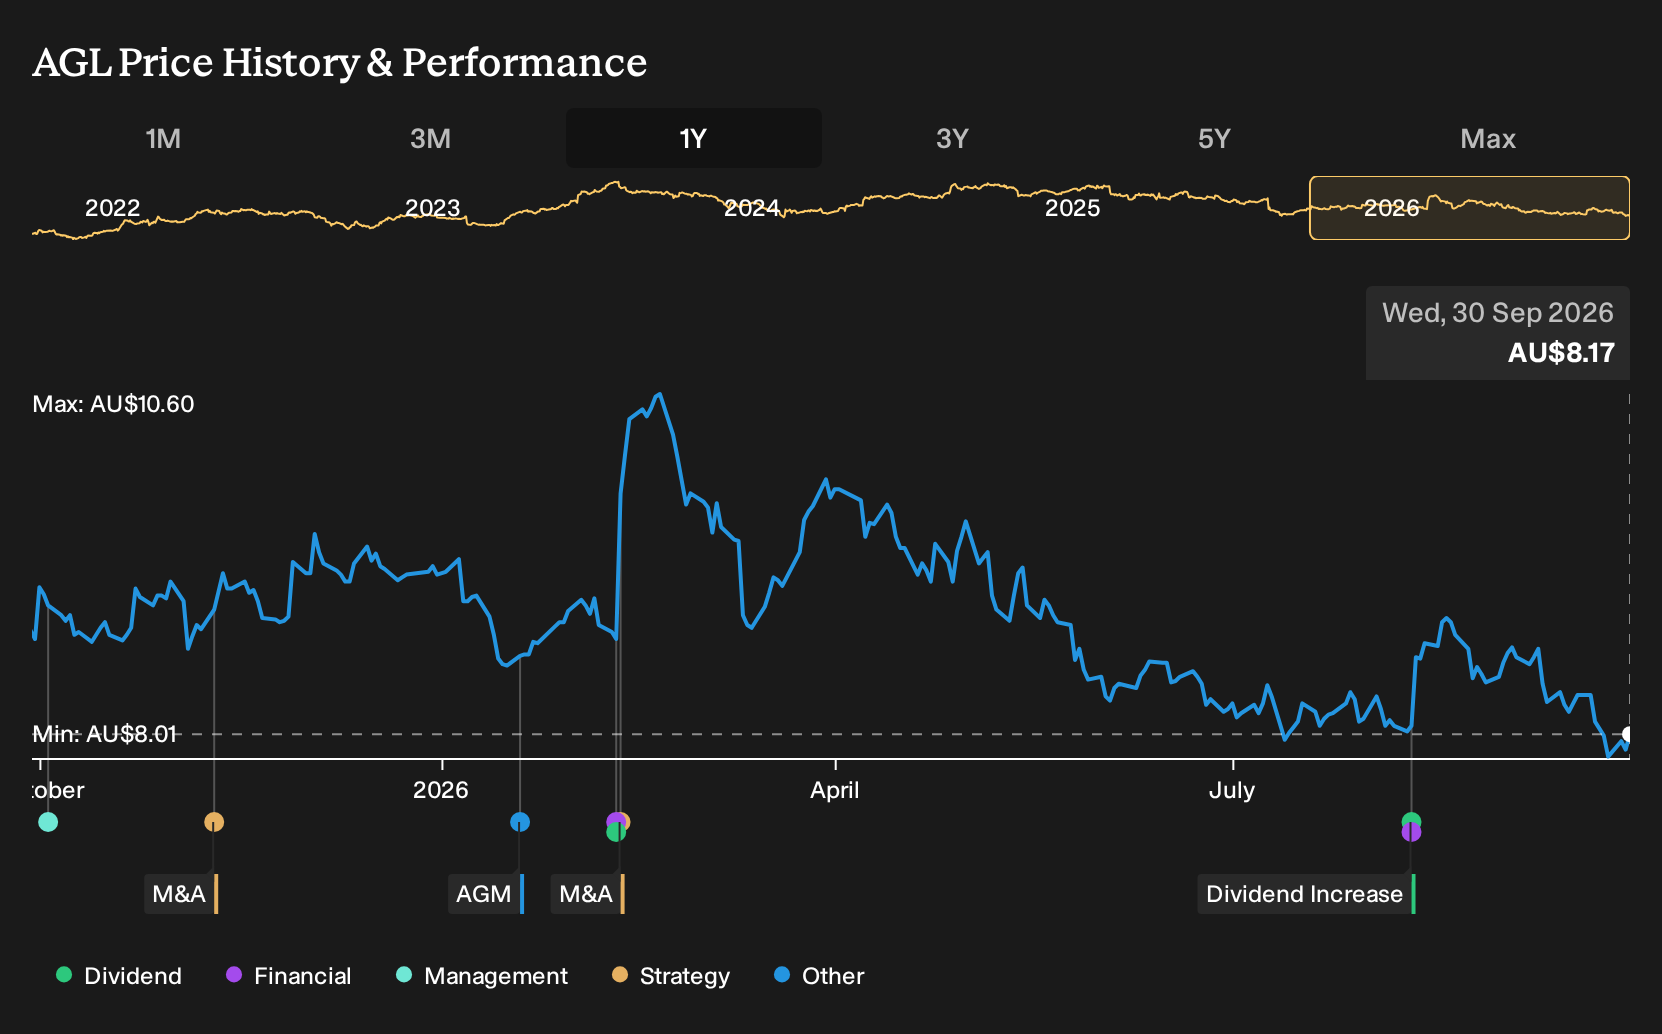
To own AGL Energy, you need to be comfortable with a business that is trying to lift customer lifetime value while working through heavy investment and an earnings outlook that consensus views as weaker over the next few years. The short term swing factor still sits in how well customer markets absorb competition and discounting pressure.
The new A$300 bill credits, telco bundling and Netflix offer look helpful for churn and cross sell, but they do not change the main near term risk. Margin compression, high capex and pressure on free cash flow remain front and centre, especially with dividends not well covered by cash generation.
The Netflix Electricity Plan and related bill credits plug directly into one of AGL Energy's key levers. Management is trying to use digital and multi product offers to keep households inside its ecosystem while larger grid scale battery and firming projects work through the cycle.
For investors, the key issue is how efficiently these bundles offset rising competition and cost to serve while the integrated energy segment transitions away from older coal and gas earnings. Execution on these customer offers sits alongside delivery of new flexible assets as the practical catalysts to watch over the next few years.
AGL Energy's narrative projects A$13.5b revenue and A$442.8m earnings by 2029. This would require revenue to decline by 1.1% per year and implies an earnings decrease of about A$313m from A$756.0m today.
Uncover why AGL Energy's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between A$9.91 and A$16.34 per share, which leaves plenty of room for disagreement on AGL Energy. Those views pre date the new bundling offers, so factor in that fresh spend and execution risk, then explore several alternative viewpoints before updating any thesis.
Explore 2 other AGL Energy fair value estimates, including one that suggests up to 100% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your AGL Energy research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for AGL Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AGL Energy's overall financial health at a glance.
Looking For More Ideas Beyond AGL Energy?
If the AGL Energy story has raised fresh questions about where to put capital to work, it can help to line it up against other companies with different balance sheet strength, income profiles, and risk levels. The Simply Wall St Screener lets you quickly filter for businesses that fit the type of return and volatility trade off you prefer.
- For investors who want potential mispricing with quality fundamentals, scan through a curated set of 5 high quality undervalued stocks that combine stronger balance sheets with appealing valuation signals.
- If reliable income matters more than rapid capital gains, focus on stocks offering solid payout profiles by reviewing a hand picked group of 3 dividend fortresses that currently clear a 5% yield hurdle.
- When capital preservation is the priority, narrow the field to companies with sturdier financial footing by working through a carefully filtered 7 resilient stocks with low risk scores that aims to keep downside in tighter check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com