
FMC (FMC) Stock May Be Below Fair Value As Stake Deal Closes
FMC Corporation has seen its stock drop sharply in recent years, and the latest leg of that slide leaves a clear question for investors who watch its sales closely. With the share price now well below where it traded for much of the past decade, the issue is how much of FMC's revenue base the current market value is really assigning.
- Over the past 5 years, FMC's share price has fallen 88.5%, which puts the focus squarely on whether the remaining market value lines up with the strength and durability of its sales.
- The recent 20% equity investment from Tessenderlo Group and the move into global field trials for RNA based bioinsecticides can reshape expectations for FMC's future revenue mix and the timing of cash flows tied to its crop protection products.
- The analysts covering FMC have run their own numbers. See what analysts think FMC's shares could be worth.
The issue now is whether FMC's current share price is appropriately reflecting the scale and quality of its sales base.
If FMC's sharp 5 year share price decline has you rethinking how much you want to rely on a single stock, a targeted screen of other 32 high quality undervalued stocks may be worth considering.
Is FMC Still Cheap on Sales?
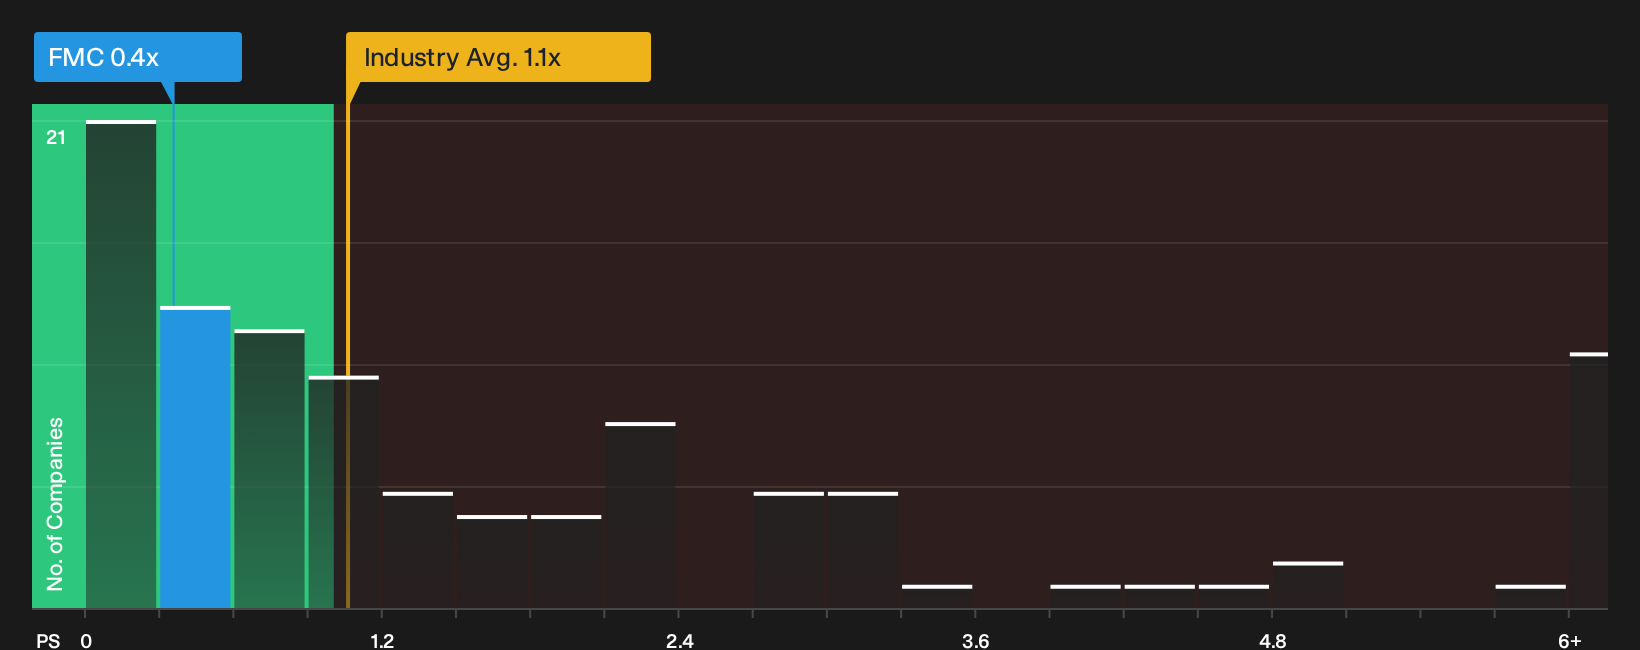
P/S fits FMC because investors are trying to judge the value of its sales when earnings are currently less useful as a guide. The stock trades on a P/S of 0.4x, using the 0.35x figure rounded, which is far below the chemicals industry average of 1.1x and the peer group on 1.3x. That puts a very low price tag on each dollar of FMC's revenue compared with many similar businesses in the sector.
The gap looks even wider when set against the tailored fair multiple that factors in FMC's size, margins and risk profile. The current 0.4x level screens as undervalued on that framework. Because Tessenderlo committed about US$403m for a 20% stake despite the share price slide, the current discount on sales suggests the market is still pricing FMC cautiously relative to both peers and that fair value marker. Explore the numbers behind FMC's P/S valuation.
The FMC Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where FMC's P/S puzzle leaves off by spelling out which combinations of future growth, profitability and earnings would need to play out for the stock to be worth sharply more or meaningfully less than it is today, and they sit on Simply Wall St's Community page. Each narrative links its number to a specific view on how FMC's growth, profitability and risk profile might evolve, giving you something concrete to test as fresh information comes through.
One of the top community narratives on FMC: 33% undervalued
"Ongoing cost transformation, including lower manufacturing costs for key products like Rynaxypyr and benefits from 2024 to 2025 restructuring, creates durable COGS reductions..."
Discover why this Narrative puts FMC at 33% undervalued.
One more angle on FMC that could change the picture
FMC's story is not only about revenue multiples and market pricing. The people steering the business and how their pay lines up with your interests can be just as important to understand. See who runs FMC and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com