
Is Honeywell International (HON) Cheap After Its 46% Slide?
Honeywell International has had a tough run year to date, and that kind of drawdown naturally puts the focus on one thing: whether the current share price still lines up with what the business earns. With the stock now trading around US$210.13, the key issue is how that market value stacks up against Honeywell's earnings power today.
- The share price is down 46.4% year to date, which puts the spotlight squarely on whether Honeywell's earnings can support the move investors have already priced in.
- Recent headlines around Honeywell's role in phase change materials and security platforms for US Marine Corps facilities can feed into expectations for future profit streams and the timing of cash flows that investors tie back to current earnings.
- There is a second opinion on Honeywell International worth weighing. See what analysts think Honeywell International's shares could be worth.
The stock's next move may depend on whether Honeywell's current earnings justify today's valuation or if the recent share price slide has pushed it away from what those profits support.
If you want a broader view of how other companies linked to this kind of thermal tech and infrastructure theme compare, it can help to line Honeywell up against 39 power grid technology and infrastructure stocks.
Is Honeywell International Still Cheap on Earnings?
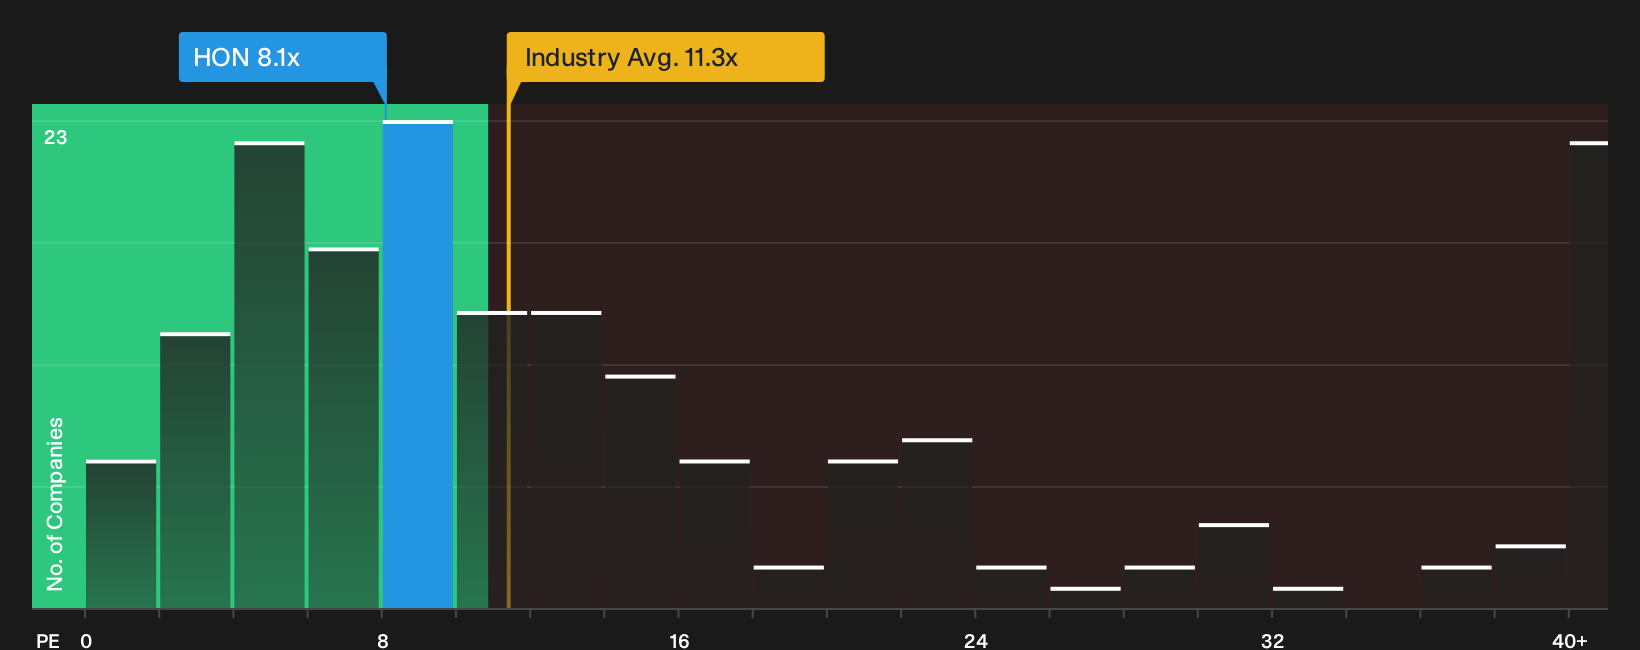
The P/E ratio suits Honeywell International because earnings remain a key anchor for how investors frame the business. On this measure, the stock trades on about 8.1x earnings. That sits below the wider Industrials sector on roughly 11.3x and well under a peer group average closer to 32.2x, which signals a marked discount on this simple earnings yardstick.
Recent attention around Honeywell's phase change materials and defense related security platforms has put fresh focus on how durable those earnings streams look. Yet the current P/E still comes in under the multiple that would typically be expected given the firm’s profile. Because of that gap, the market price today reflects a lower earnings multiple than the tailored benchmark suggests might be justified, even after baking in business risks and sector context. Explore the numbers behind Honeywell International's P/E valuation.
The Honeywell International Narrative: What Would Justify Today's Price?
Narratives on Honeywell International pick up where the valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today on Simply Wall St's Community page. Each scenario links its number to a specific view on how Honeywell International's growth rate, profitability and risk profile might evolve, giving you something concrete to revisit as fresh information comes through.
One of the top community narratives on Honeywell International: 34% undervalued
"Through its majority ownership stake in Quantinuum, Honeywell retains exposure to a technology increasingly viewed through a national competitiveness lens..."
Discover why this Narrative puts Honeywell International at 34% undervalued.
One more Honeywell International signal worth checking before you move on
Everything so far has focused on what Honeywell International looks like right now, but there is a separate set of expectations that professional analysts have mapped out for the next few years. Explore where analysts expect Honeywell International to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com