
Is Hinge Health (HNGE) Undervalued Or Is Its Rally Already Priced In?
Hinge Health (HNGE) drew fresh attention after recent share moves, with the stock last closing at $95.21. Investors are weighing that price against the digital musculoskeletal care specialist’s current scale and profitability profile.
Recent trading has come on top of a strong run for Hinge Health, with a 30 day share price return of 9.0%, a year to date share price return of 108.98% that points to building momentum, and a 1 year total shareholder return of 93.99%.
Scan other high-momentum opportunities alongside Hinge Health by reviewing the hand picked 32 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
Hinge Health now trades at a clear discount to both analyst targets and one intrinsic value estimate, even after its rally. Is that a genuine mispricing, or is the market pricing in real risks around scale and profitability?
Most Popular Narrative: 34.4% Undervalued
Hinge Health is framed as materially mispriced in the most followed narrative, with a fair value of $145.04 against a last close of $95.21.
Hinge Health has quickly distinguished itself as one of the most successful IPOs of 2025, combining rapid revenue growth, widening margins, and a scalable AI‑driven care model. The company’s focus on musculoskeletal (MSK) health, covering prevention, acute injury, chronic pain, and post‑surgical recovery, has resonated with employers and insurers, driving adoption across millions of contracted lives.
See why 1 investors see Hinge Health as 34% undervalued.
Result: Fair Value of $145.04 (UNDERVALUED)
Still, Hinge Health’s reliance on large self insured employers, along with its exposure to changing healthcare regulations, could quickly challenge the upbeat undervaluation story.
Find out about the key risks to this Hinge Health narrative.
Another View on Hinge Health’s Valuation
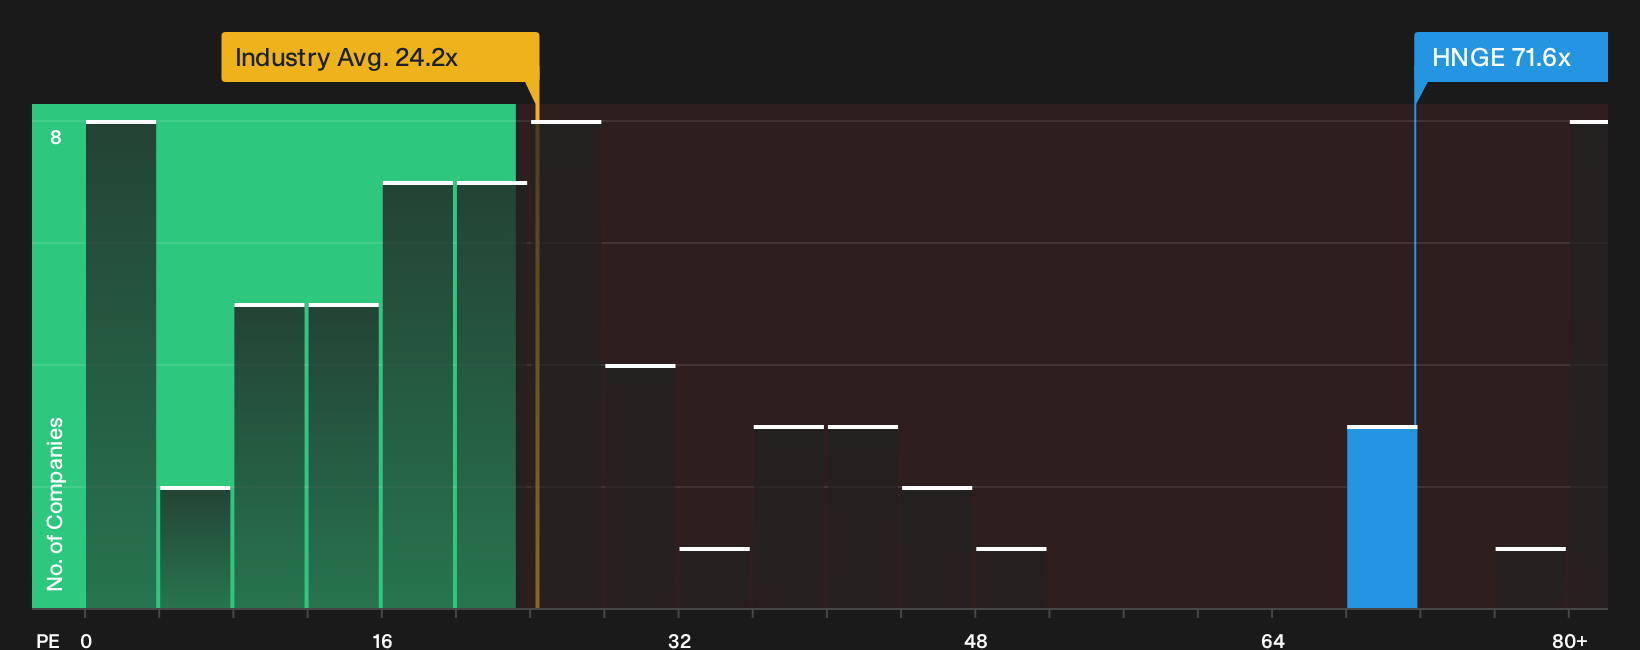
The first narrative paints Hinge Health as heavily undervalued, yet the earnings multiple tells a very different story. At a P/E of 71.6x versus 24.2x for the US Healthcare sector and a fair ratio of 38.7x, the stock trades at a steep premium that raises real valuation risk for anyone paying today’s price.
That kind of gap to both peers and the fair ratio suggests expectations are loaded with optimism. This puts the burden on future execution more than on a simple mispricing argument.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of optimism and risk around Hinge Health will not resolve itself. Act while sentiment is still forming by reviewing the 3 key rewards.
Looking for more investment ideas beyond Hinge Health?
If Hinge Health has sharpened your focus on valuation and momentum, do not stop here. Broaden your watchlist with other ideas that fit your style.
- Target dependable cash flows and balance sheet strength by reviewing the list of solid balance sheet and fundamentals (25 results) built for investors who want resilience first.
- Hunt for underappreciated opportunities by scanning the 17 high quality undiscovered gems before the wider market pays attention.
- Dial down portfolio risk and smooth out volatility by checking the 32 resilient stocks with low risk scores that filters for sturdier business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com