
Should Value Upgrade Require Action From Mercury General (MCY) Investors?
- Mercury General has recently drawn attention after analyst coverage highlighted its low P/E ratio and value-focused metrics, along with an improved earnings outlook for its personal auto and property insurance operations.
- The interesting angle for investors is how a value grade of A and rising earnings estimates intersect with a business still working through wildfire related pressures and reinsurance costs.
- We will now look at how Mercury General's investment narrative might shift given this renewed focus on its valuation metrics and earnings outlook.
Compare Mercury General's value story with other potential underpriced ideas by scanning our hand picked 32 high quality undervalued stocks that share strong fundamentals and disciplined pricing power.
Mercury General Investment Narrative Recap
To own Mercury General, you need to be comfortable with a simple idea. The core personal auto and homeowners book needs to stay disciplined on pricing and underwriting while wildfire exposure and reinsurance costs remain the swing factors. The recent focus on its low P/E and value score does not change that central requirement.
The near term hinge is whether underlying combined ratios in auto and property stay healthy enough to support capital rebuilding and premium growth. The biggest current risk is that further wildfire losses, higher reinsurance rates, or extra California FAIR Plan assessments pressure statutory surplus more than expected.
The recent attention around Mercury General’s value metrics ties directly into that backdrop. A Zacks Value grade of A and a low P/E do not fix catastrophe exposure. However, they highlight how much weight the market is putting on those risks relative to the strength in the underlying book and recent earnings growth.
For you as a shareholder, the relevant question is whether that gap between cautious sentiment and the current operating profile closes through steady underwriting results, capital generation, and any subrogation recoveries from past wildfires. Analyst recognition of the stock as a value idea simply shines a brighter light on how those catalysts and wildfire related risks play out.
Mercury General's current analyst blueprint points to forecast revenue of $6.9b and earnings of $623.9m by 2029, based on 4.1% yearly revenue growth and an earnings decline of about $215.9m from $839.8m today to that 2029 consensus figure.
Uncover why Mercury General's fair value indicates a 20% potential upside to its current price before the discount closes.
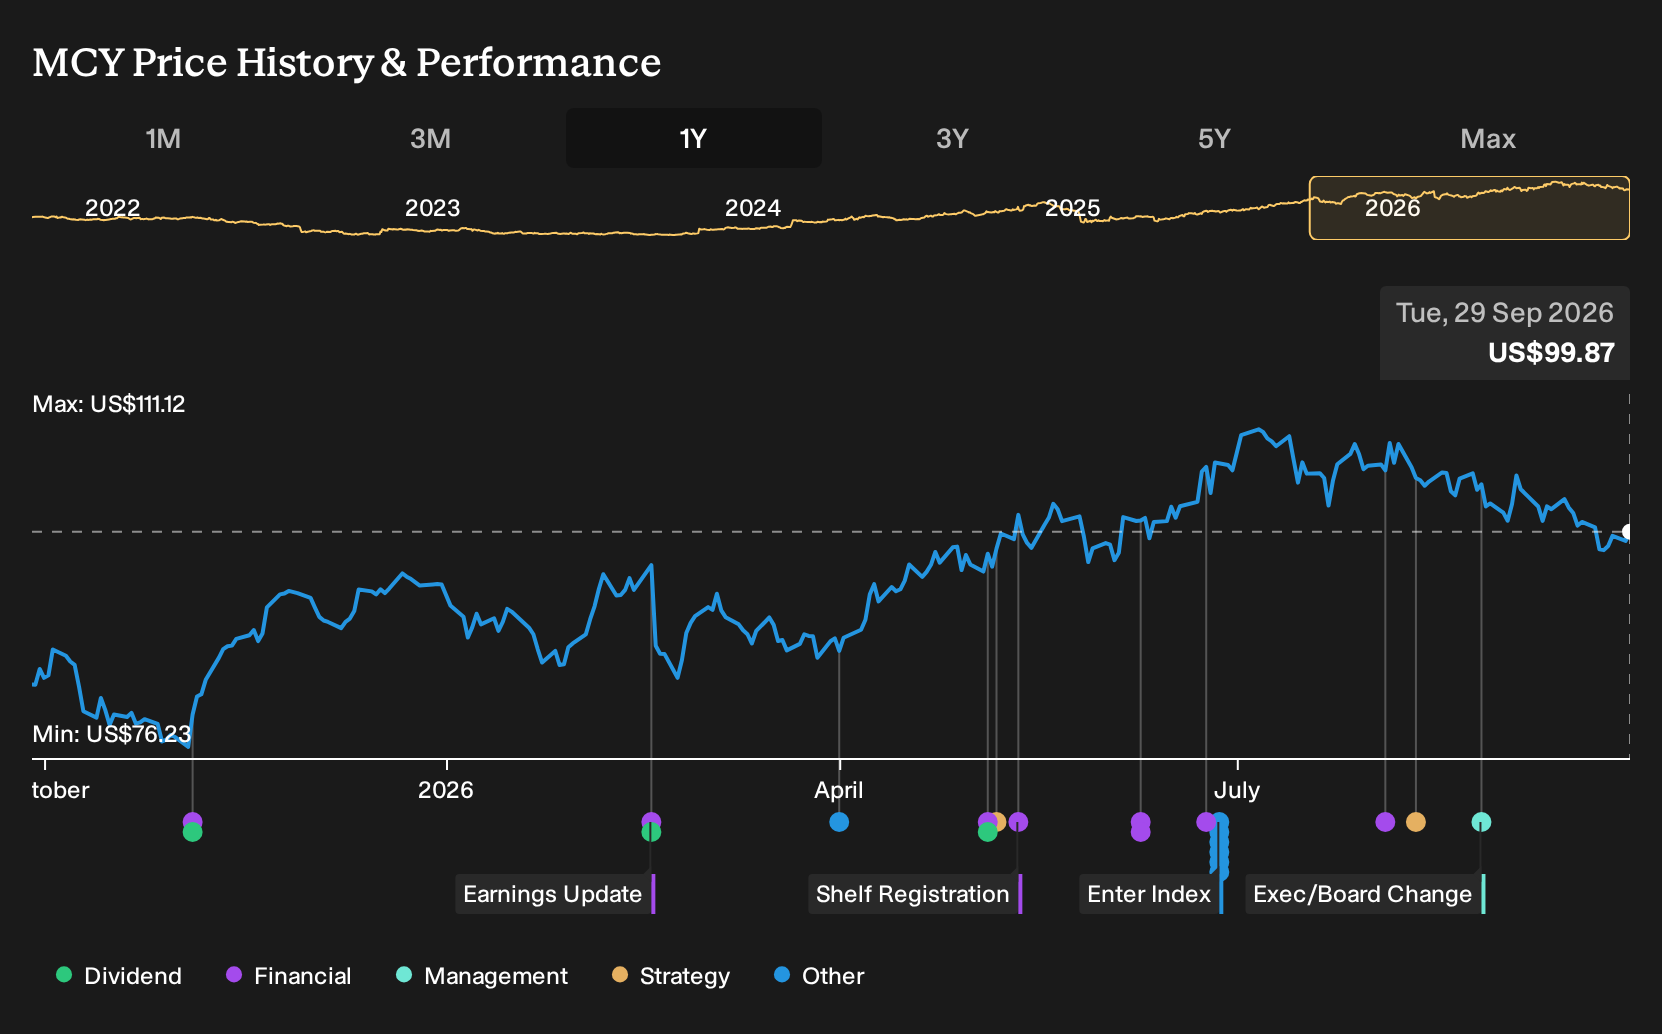
Exploring Other Perspectives
Mercury General now faces three fair value estimates from the Simply Wall St Community, with targets stretching from about $102.88 up to roughly $164.03. That wide span is a reminder of how sharply opinions can split, especially with wildfire losses, reinsurance costs, and possible subrogation recoveries all pulling future results in different directions.
Explore 2 other Mercury General fair value estimates, including one that suggests it could be worth just $102.88.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Mercury General research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Mercury General. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mercury General's overall financial health at a glance.
Looking For More Investment Ideas Beyond Mercury General?
Once you have formed a view on Mercury General, it can help to set that thesis against a wider watchlist. The Simply Wall St Screener lets you quickly scan other companies with different risk and income profiles so you can see where Mercury General fits in your broader portfolio plan.
- For investors who want income that has the potential to keep coming, review a range of stocks that our process classifies as 6 dividend fortresses and see which yields match your comfort level.
- If capital protection is a priority, focus on stability first and growth second by checking out companies flagged as 32 resilient stocks with low risk scores that may line up better with a cautious approach.
- When you are hunting for underfollowed opportunities with solid fundamentals, scan our 17 high quality undiscovered gems and see which stories you might want to research next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com