
3 US Bank Stocks Built For Higher Long Term Treasury Yields
Hedge funds now hold roughly US$2t of Treasuries, long yields sit near multi decade highs, and the usual long term buyers are stepping back. That mix can jolt discount rates and shake up which stocks investors reward. If you care about how higher 10 and 30 year yields might reprice risk, this is your moment. This article walks through three US financial and value stocks exposed to that story.
The three stocks below are a starting sample of that filter in action, and the full screen surfaced 28 more companies with equally grounded income statements, balance sheets, and interest rate stories that are not covered here.
Identify, compare, and analyze the highest conviction setups straight from the US Financials and Value Stocks Benefiting from Higher Long-Term Yields screener.
National Bank Holdings (NBHC)
National Bank Holdings fits directly into the screener’s higher long term yield theme because it is a traditional commercial bank. Lending and deposit pricing can turn interest rate moves into potential earnings power, and fee income adds a second engine to that story.
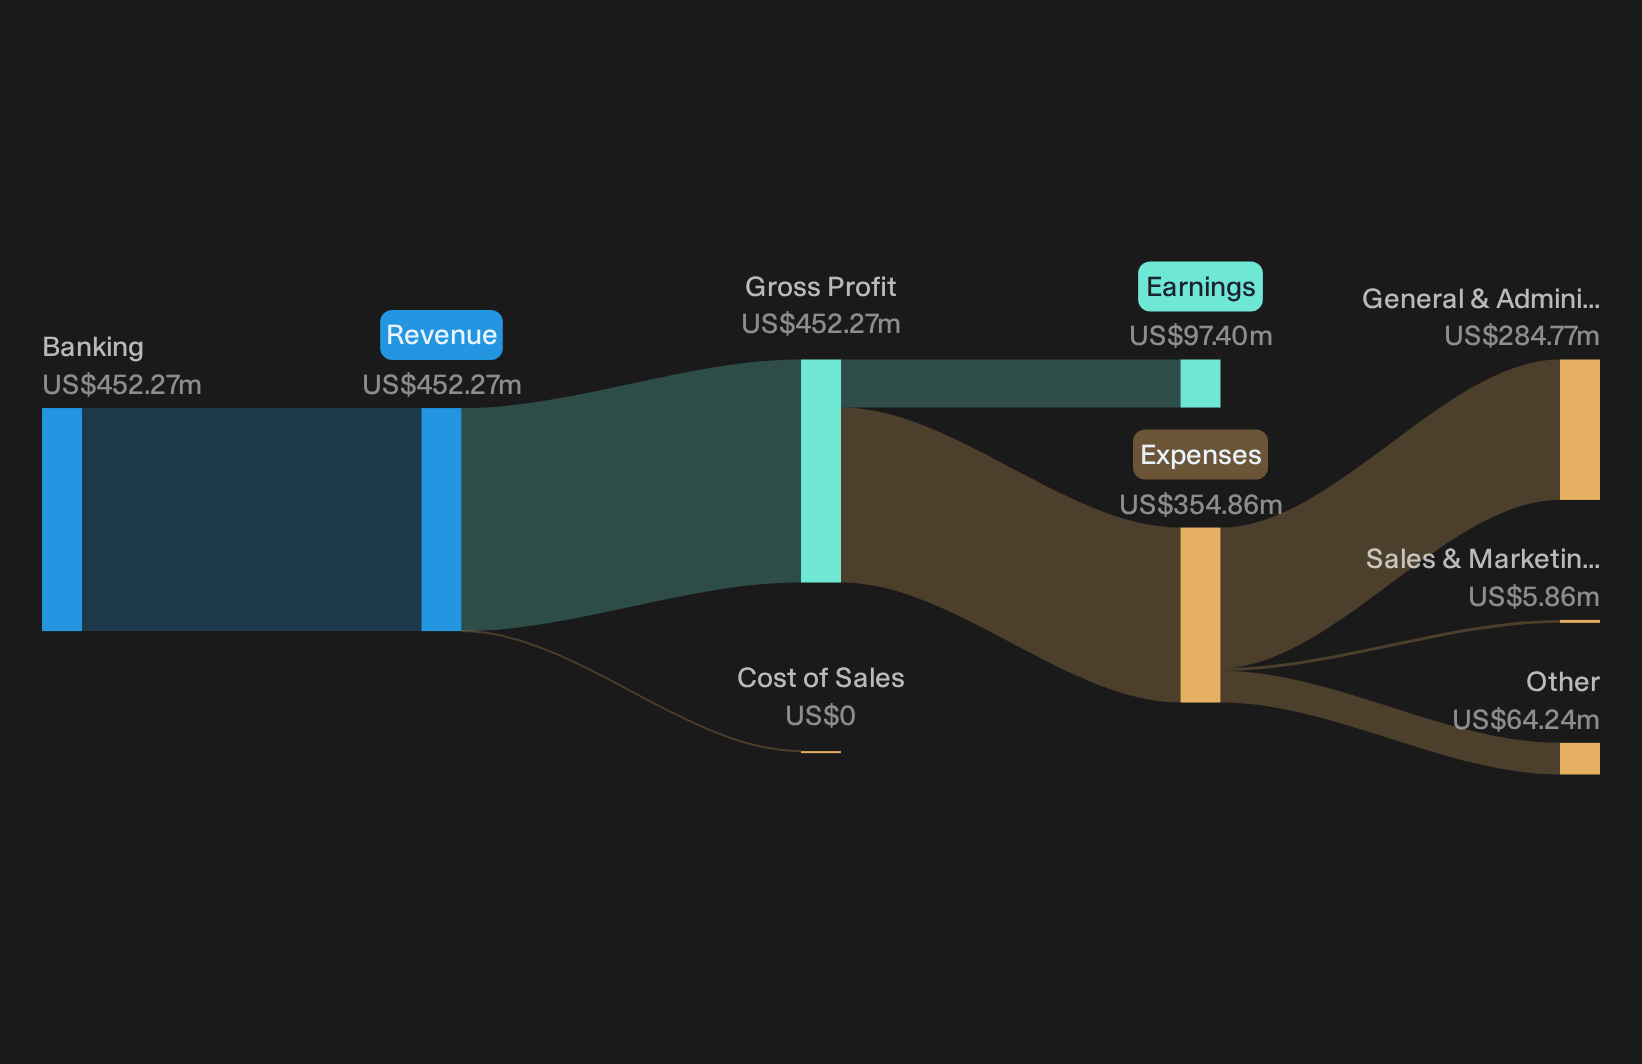
National Bank Holdings runs a regional US banking franchise focused on loans, deposits, and treasury services, generating about US$452 million from banking activities and carrying a market value near US$1.8b.
"The successful launch of the 2UniFi platform, with positive early feedback and plans for further feature expansion (including fee-based membership offerings and integrated fintech services for SMBs), positions the company to capitalize on the shift toward digital banking and technology-driven financial solutions, potentially driving incremental noninterest income and expanding high-margin fee revenue streams."
What really matters now is how one pressure point in its interest income mix shapes future margin resilience and earnings quality.
That pressure point is exactly what the full narrative for National Bank Holdings unpacks, highlighting where margin resilience could accelerate and which risks might still be masking the real story.
Bank of Marin Bancorp (BMRC)
Bank of Marin Bancorp is a regional lender built around small and mid sized business clients and commercial real estate. This profile fits the screener’s focus on financials whose earnings are closely tied to long term rates and traditional value style metrics.
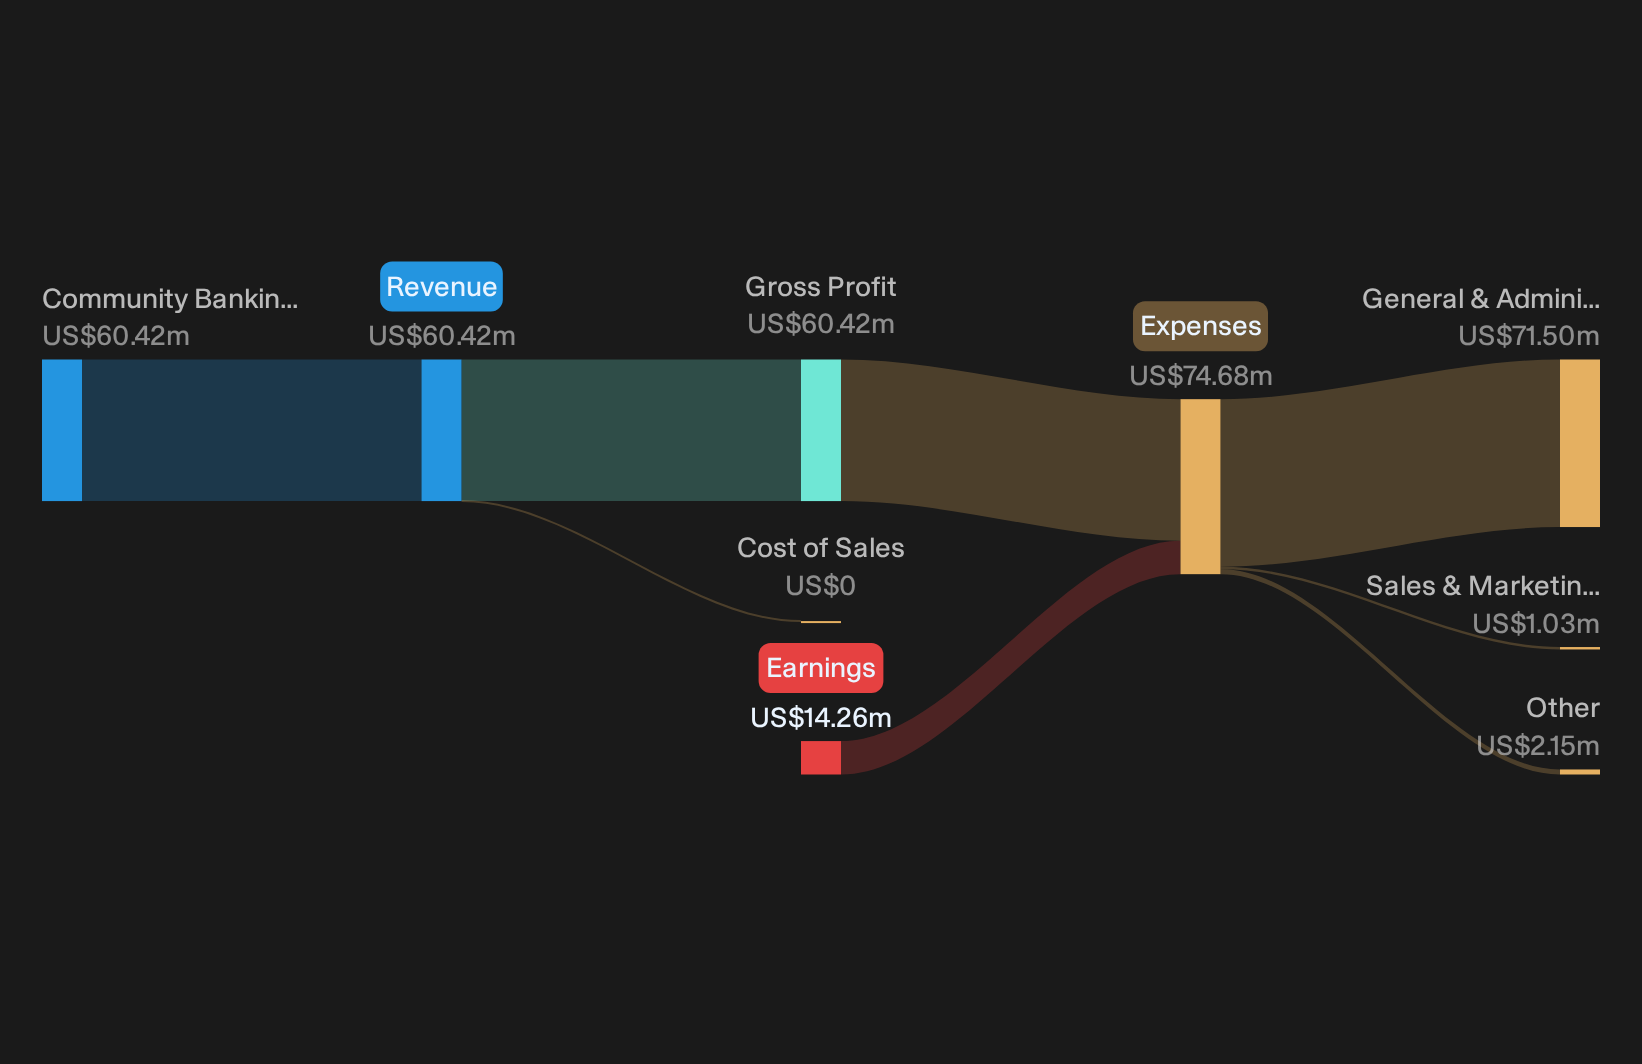
Bank of Marin Bancorp runs a community banking franchise in Northern California, generating about US$60 million from community banking and carrying a market value near US$439 million.
Higher long term Treasury yields ripple straight into funding costs and loan pricing. This makes Bank of Marin Bancorp an important test case for how a relationship driven, value leaning regional institution can turn that rate backdrop into steadier earnings power.
"Ongoing targeted investment in digital infrastructure and technology, including mobile banking and online lending upgrades, positions the bank to drive operational efficiency and improve customer engagement, which should support margin expansion and lower long-term costs."
The real swing factor is whether one quiet shift in its business mix strengthens margins fast enough to keep that value story intact.
If that quiet shift has your attention, the full narrative for Bank of Marin Bancorp explains how Bank of Marin Bancorp’s earnings profile could be accelerating or quietly stalling.
Banc of California (BANC)
Banc of California is a pure play on the screener’s higher long term yield theme, with commercial banking, treasury services, and net interest margins all tied directly to how it prices loans and deposits across its US footprint.
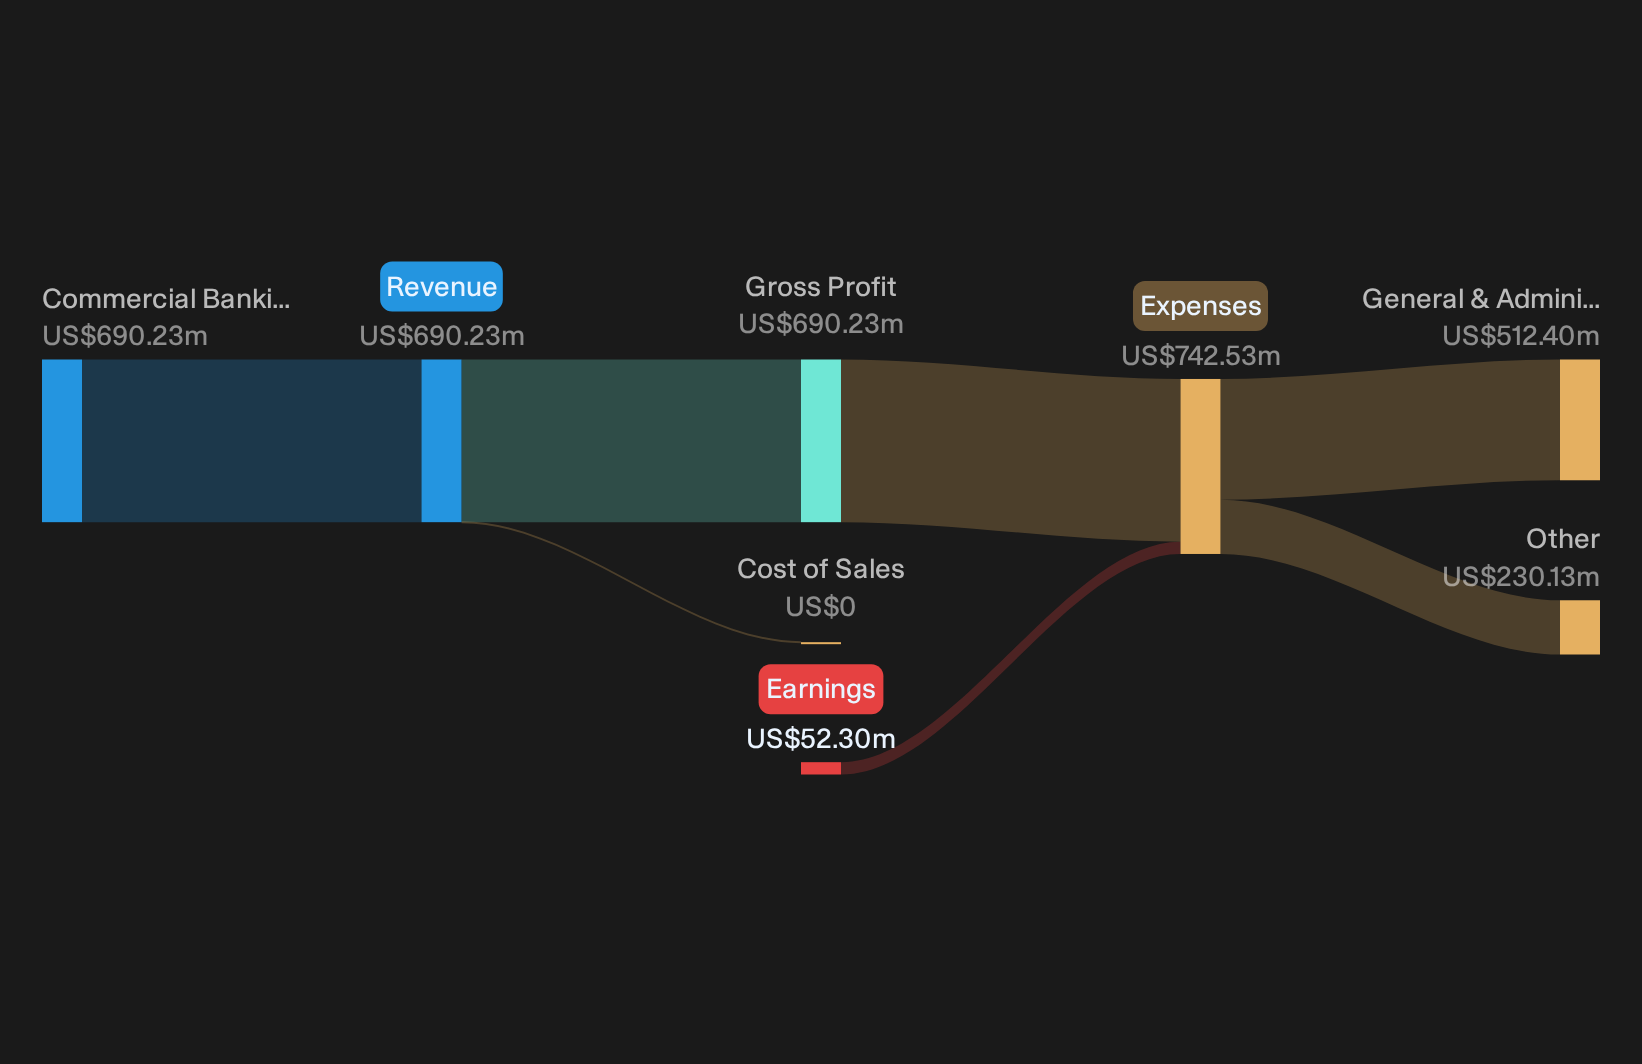
Banc of California generates about US$690 million from commercial banking in the United States and has a market value near US$2.8b.
"The ongoing shift to digital financial services across all demographics is accelerating Banc of California's ability to attract new customers, reduce its customer acquisition and operating costs, and expand core deposit growth, driving improved efficiency, net interest margins, and sustained earnings growth."
What really matters now is how one quiet shift in its loan book interacts with that deposit engine to reshape future margins.
That loan book shift is where the real inflection could emerge, and the full narrative for Banc of California shows how Banc of California’s earnings profile might be accelerating while risks stay contained.
Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum is obvious, the cleanest entry points are often gone. Scan these under the radar lists while it matters and get in early.
- Target stable cash generators and stress tested balance sheets with a curated list of solid balance sheet and fundamentals (25 results) before others catch on to their resilience and pricing power.
- Chase early momentum in specialist miners and producers by tracking the 35 best rare earth metal stocks before commodity sentiment turns and valuations start flying.
- Position ahead of potential yield shifts by reviewing the 6 dividend fortresses that focus on durable payouts that investors often seek when interest rates change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com