
How Investors May Respond To Fair Isaac (FICO) Mortgage Score Competition
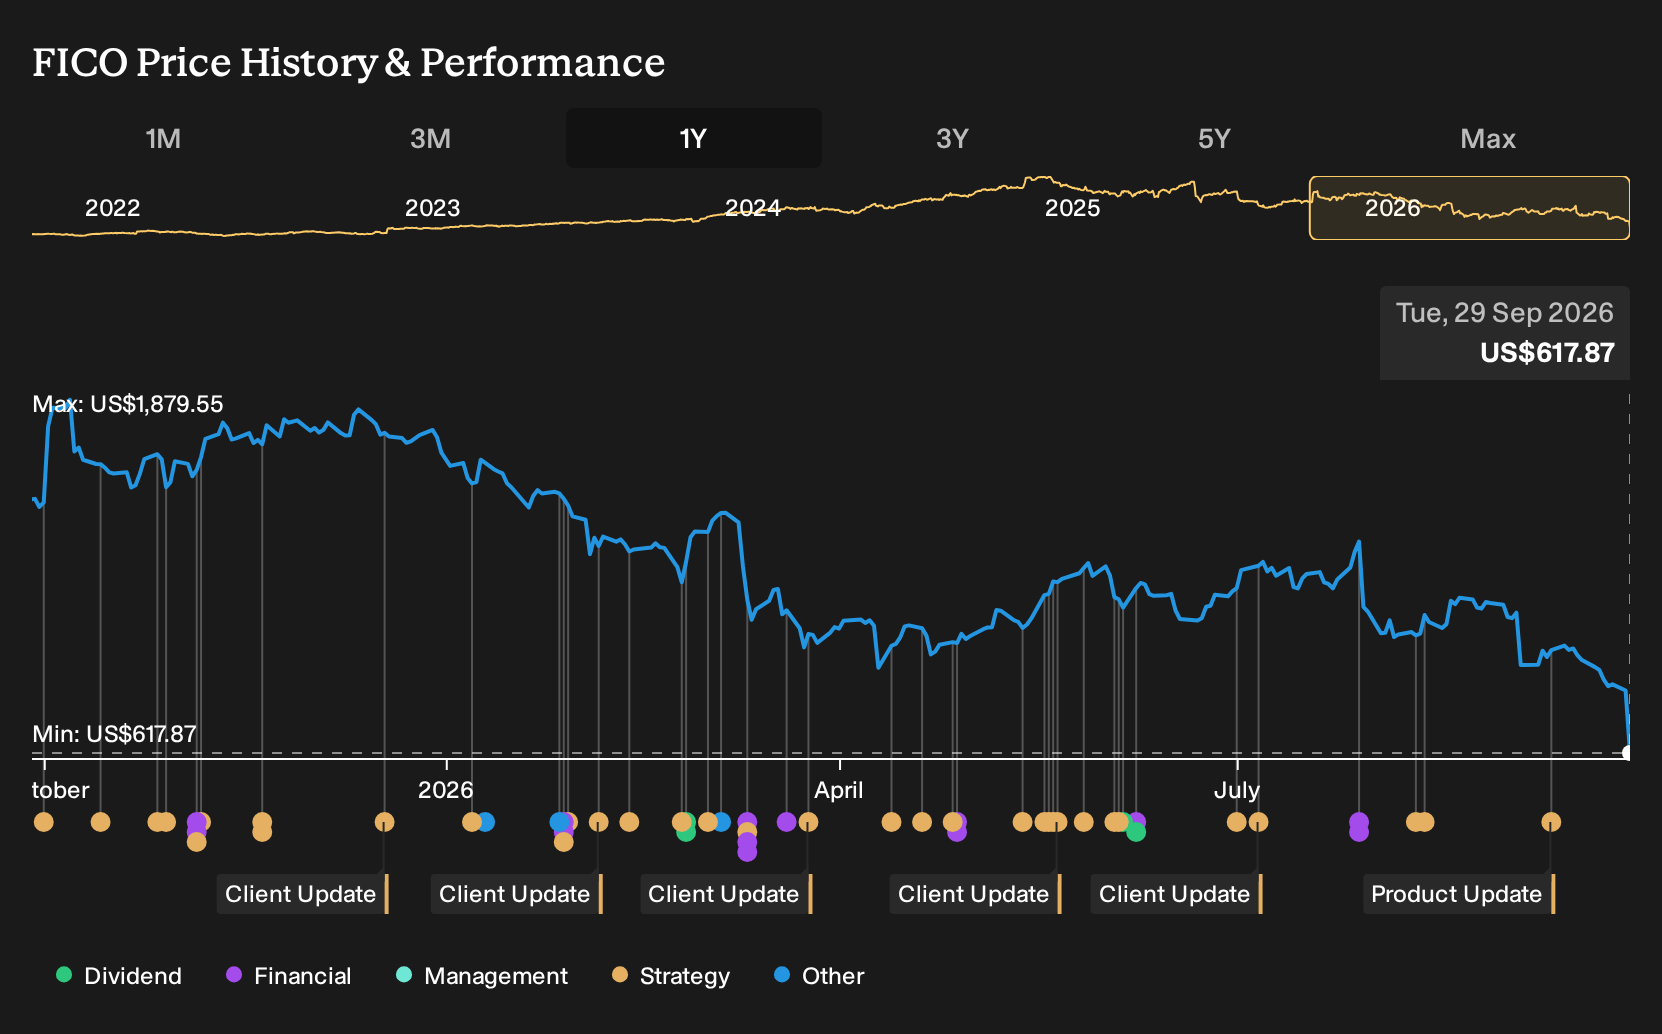
- Fair Isaac faced a regulatory jolt as the FHFA moved Fannie Mae and Freddie Mac to a single mortgage pricing grid that treats VantageScore and traditional FICO scores equally for government backed home loans.
- The shift, reinforced by Rocket Mortgage choosing VantageScore as its preferred model, directly targets Fair Isaac's long running mortgage scoring concentration and fee stream.
- We will look at how Fair Isaac's investment narrative holds up as FHFA backed credit score competition reshapes its mortgage franchise.
Compare Fair Isaac's mortgage shock with a curated group of cash generative, financially solid alternatives screened through our list of solid balance sheet and fundamentals (25 results).
Fair Isaac Investment Narrative Recap
To own Fair Isaac, you need to believe its core scoring franchise and software platform can stay relevant as lenders lean harder on data driven decisioning. The FHFA move directly touches that belief. The key near term swing factor is how much mortgage volume actually migrates to VantageScore and how quickly lenders reconfigure workflows around alternative scores.
The biggest current business risk is concentration in US mortgage scoring at a time when FICO already faces slower software growth and higher operating costs. If lenders meaningfully shift away from FICO Classic, the firm may need to lean harder on FICO Platform, international deals, and newer score versions to offset pressure on pricing and margins.
The FHFA unified pricing grid, which now puts VantageScore on equal footing with FICO for GSE backed mortgages, is the announcement that matters most here. It removes the structural advantage Fair Isaac held on those loans and creates a real test for how sticky lender behavior is when pricing and regulatory treatment stop favoring its scores.
For catalysts, watch how quickly large originators such as Rocket Mortgage embed VantageScore into underwriting, and whether banks push FICO to reprice or bundle more aggressively with software. Execution on SaaS based decisioning tools, explainable AI offerings, and international score adoption becomes more important if mortgage related score revenue faces incremental competition.
Fair Isaac's current analyst narrative points to revenue of US$3.5b and earnings of US$1.3b by 2029, built on an assumed 13.8% yearly revenue growth rate and an earnings increase of about US$485m from US$815m today.
Uncover how Fair Isaac's fair value indicates a 133% potential upside to its current price. This upside could narrow quickly if sentiment turns.
Exploring Other Perspectives
One alternate, more optimistic view treats Fair Isaac’s heavy mortgage reliance as a launchpad rather than a liability. Those bullish analysts were penciling in revenue of about US$3.9b and earnings of US$1.5b by 2029 before this FHFA shock. You can see how sharply opinions differ, and why fresh viewpoints now matter.
Explore 6 other Fair Isaac fair value estimates, including one that suggests potential upside of up to 178% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fair Isaac research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fair Isaac. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fair Isaac's overall financial health at a glance.
Looking For More Ideas Beyond Fair Isaac?
Once you have a view on Fair Isaac, it can help to broaden your watchlist with other companies that match the kind of quality or risk profile you are comfortable with. The Simply Wall St Screener can surface opportunities that fit different styles, from stability to income to higher risk, higher potential situations.
- If capital preservation and balance sheet strength matter most to you, start with a 32 resilient stocks with low risk scores that aims to keep downside in check while still offering equity upside.
- For investors who want resilient cash generation combined with sensible pricing, scan through 32 high quality undervalued stocks that pair stronger fundamentals with what our models view as discounted valuations.
- If you are hunting for smaller companies that larger funds may not focus on yet, review 17 high quality undiscovered gems that combine solid financials with lower market visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com