
What You Could Reuse From Bristol Myers Squibb's 46% Gain
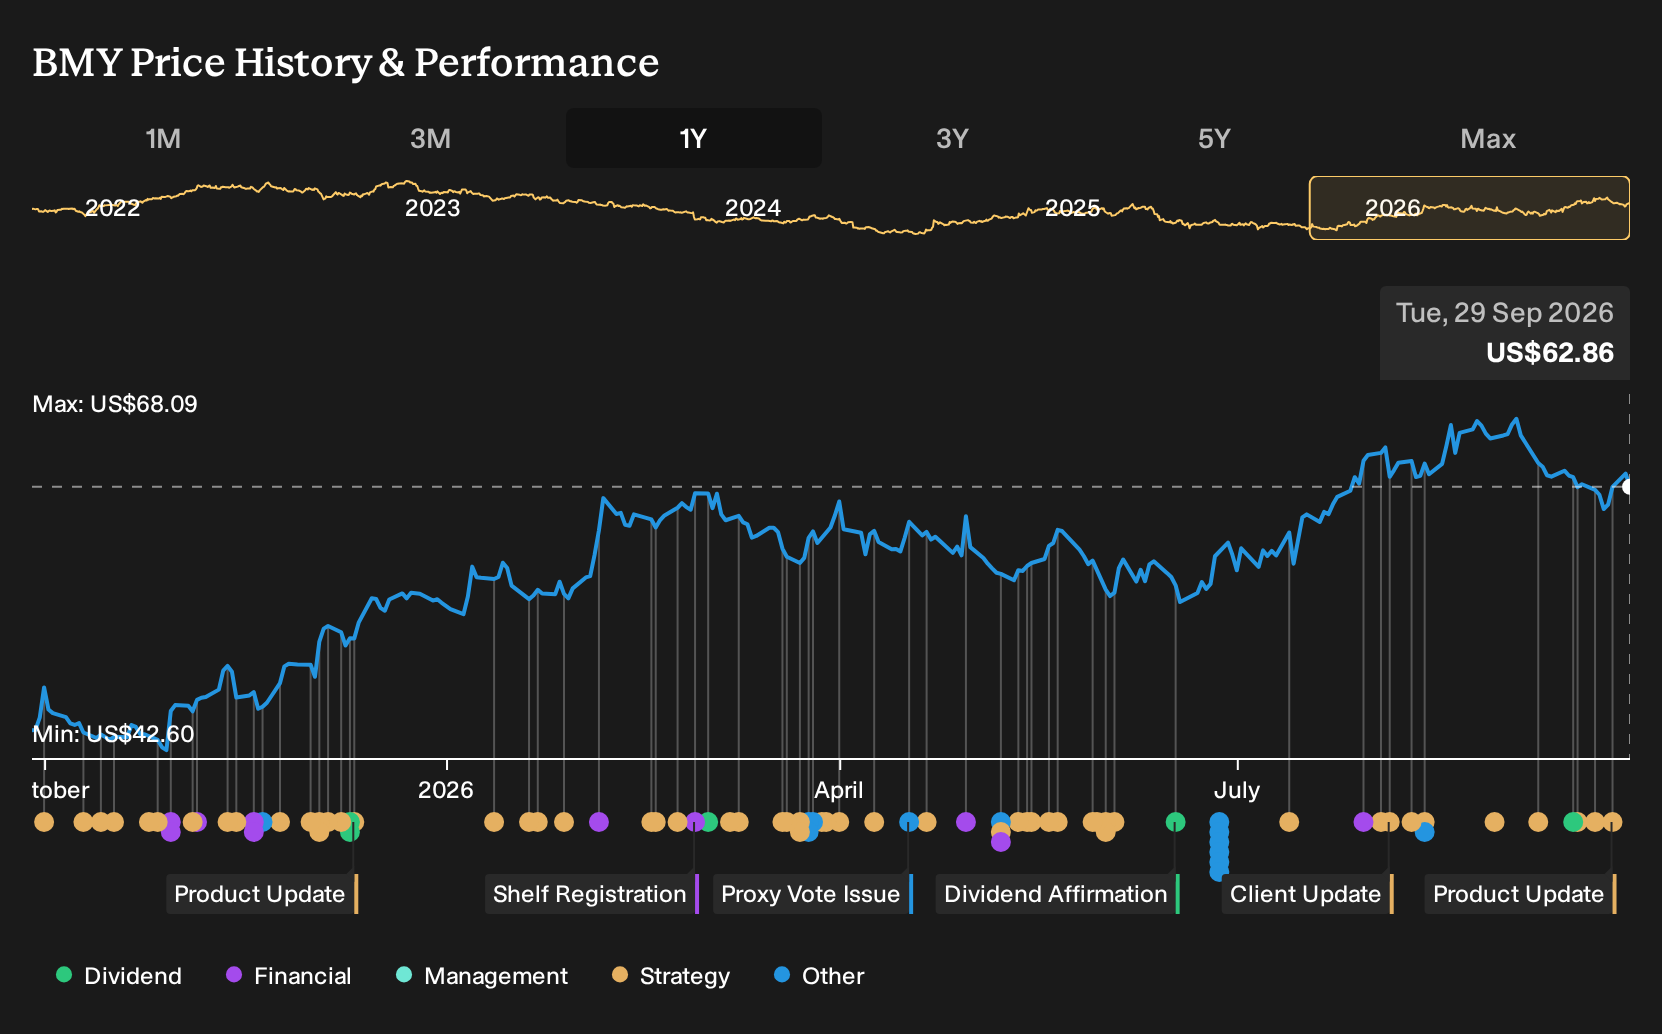
If you only glanced at Bristol-Myers Squibb headlines lately, you saw fresh oncology wins, big-ticket partnerships and a manufacturing build-out landing alongside revived litigation and merger chatter. For Bristol-Myers Squibb shareholders, the return over the past year was 46.1%, including dividends. If you had been weighing whether to buy at the end of September 2025, how could the mix of patent cliffs, debt concerns and pipeline optimism on record then have justified taking that risk?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
This theme extends beyond Bristol-Myers Squibb. See which of 35 healthcare AI stocks may still merit a closer look.
The Two Bristol-Myers Squibb Stories Investors Had To Choose Between
The shares cost US$44.15 at the start of the period, and any investor looking at Bristol-Myers Squibb then had to decide which story about the future felt more realistic.
The optimistic Narrative put Fair Value at US$53, or 20% above the start price. It leaned on aging demographics and genomics, along with an assumed revenue decline of 4.7% a year but a profit margin rising to 22.4% and a future P/E of 14.4x.
The pessimistic case fixed Fair Value at US$34, or 23% below the start price. That view focused on debt and looming patent expiries, with an assumed annual revenue decline of 6.4%, profit margin of 16.7%, and a future P/E of 13.7x.
What The Evidence Did To The Bristol-Myers Squibb Argument
The Q2 2026 report gave Bristol-Myers Squibb bulls fresh support. Revenue was US$12,973m and net income reached US$3,317m, with net margin at 25.6% compared with 10.7% a year earlier. That margin shift moved closer to the optimistic narrative, although the revived US$6.7b Celgene lawsuit and ongoing patent concerns kept the cautious case alive. Overall, the evidence cut both ways.
The hinge assumption here was future profitability, not just sales. When you assess another drug maker facing patent cliffs, track where net margin actually lands against the story you are being told, then decide what P/E you are willing to pay for that level of earnings power.
What Bristol-Myers Squibb's Run Now Asks You To Believe
Bristol-Myers Squibb trades at US$62.86, with this selected Narrative arguing that Fair Value sits above that level. The argument leans on late stage drugs and cost discipline rather than simple headline growth.
The key test for anyone paying today is whether margin gains from new oncology launches and the current cost program can truly be maintained.
"While consensus sees operational initiatives generating margin improvement, these projections understate the impact of BMS's $2 billion cost discipline program, which is being executed faster than planned, combined with asset reallocations and new gross margin tailwinds from the high-margin nature of pipeline launches, setting the stage for substantial operating margin and EPS upside."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Bristol-Myers
Bristol-Myers Squibb puts cancer and immunology in front of you. That addresses only part of the healthcare picture.
Patients on those therapies often also manage weight, blood sugar and heart risk. Your watchlist can acknowledge those linked needs.
Another large pharmaceutical group concentrates on injectable and oral drugs for obesity and diabetes. Its newer compounds try to act on several biological signals together.
The goal is straightforward. Ease weight, blood sugar and physical strain within one treatment plan.
If that multi-target approach continues to perform well, patient and physician interest could shift meaningfully.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 25% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com