
Biotest (XTRA:BIO3) Draws Fresh Attention, Is It A Bargain Or Fully Priced?
Biotest (XTRA:BIO3) has drawn fresh attention after its recent share performance, with the price closing at €28.40. Both the year-to-date and 1-year total returns are in positive territory.
Recent trading has been choppy for Biotest, with the share price falling 3.4% over the past day and the 90 day share price return also down 3.4%. At the same time, the 1 year total shareholder return of 4.94% and 5 year total shareholder return of 13.92% point to relatively modest, stop start momentum rather than a strong trend in either direction.
Scan beyond Biotest and compare its recent stop start returns with a curated group of 226 resilient stocks with low risk scores that may better match the profile you are looking for.
Biotest now trades at €28.40, and its intrinsic value estimate points slightly lower. Does that recent slip signal a small overshoot or a fair entry near the middle of the range?
Price-to-Sales of 1.8x: Is it justified?
On simple sales-based metrics, Biotest looks cheap. The stock trades on a P/S ratio of 1.8x, while its own intrinsic value estimate from the SWS DCF model sits well below the current €28.40 share price, and both peer and industry comparisons suggest the market is paying a much higher tag for similar revenue elsewhere.
P/S compares a company’s market value to its annual revenue. For a pharmaceuticals and biotech group like Biotest that is currently loss making, this metric often becomes a primary shortcut for investors who still want a sense of what they are paying for each euro of sales when earnings are not yet a reliable guide.
Here the gap is stark. Biotest trades on a P/S of 1.8x, while the peer group average sits at 23.8x and the wider European biotechs industry sits at 8.9x. Those comparisons signal that the market is attaching a far lower value to each euro of Biotest revenue than it does to similar businesses, which is a strong relative discount on sales.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Sales of 1.8x (UNDERVALUED)
Still, Biotest carries clear risks, including ongoing losses of €24.5m and the possibility that its parent, Grifols Biotest Holdings, may influence future decisions.
Find out about the key risks to this Biotest narrative.
Another View on Biotest’s Value
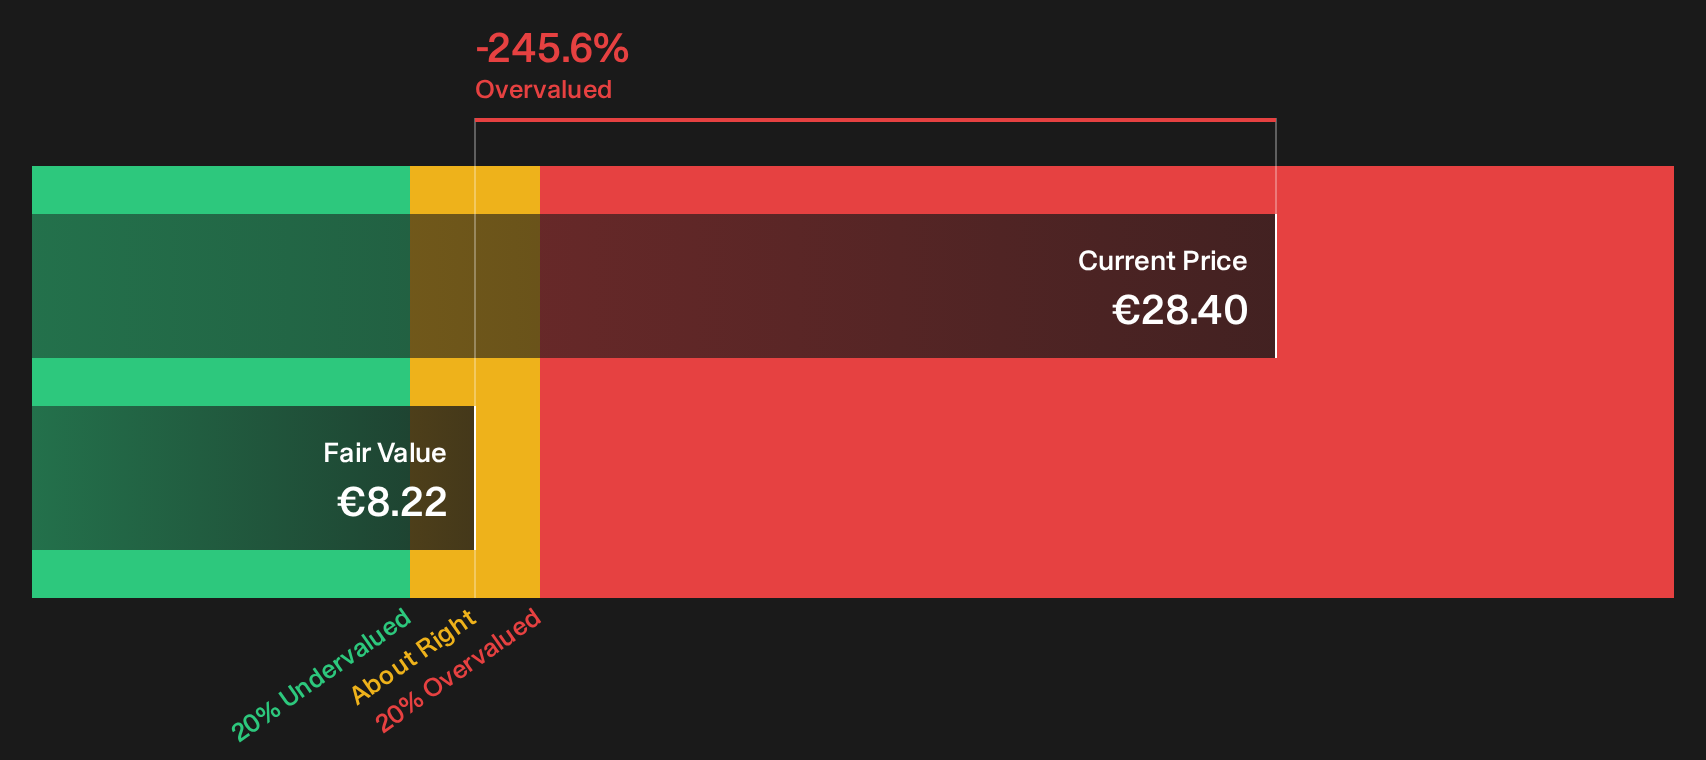
The low 1.8x P/S ratio paints Biotest as discounted. The SWS DCF model tells a different story. On that framework, the estimated fair value sits at €8.22, while the share price is €28.40. That points to Biotest trading well above this intrinsic value estimate. Which signal do you trust more?
For anyone weighing up what this kind of gap might mean for downside risk or future upside, the next step is to see how that model is built in detail. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Biotest for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 189 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If you are uncertain about what this means for Biotest and your own risk tolerance, review the red flags directly and then decide how comfortable you feel with that profile by reading the 2 important warning signs
Looking for more Biotest-sized investment ideas?
If Biotest has you thinking harder about value, do not stop here. Use focused screeners to spot other opportunities before they move without you.
- Target solid foundations by filtering for companies with strong balance sheets and dependable fundamentals through this list of solid balance sheet and fundamentals (205 results).
- Hunt for mispriced opportunities by zeroing in on companies that trade below their estimated worth with the 189 high quality undervalued stocks.
- Stack potential income ideas by scanning for resilient payers offering higher yields with the 156 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com